
Experience Co outlines Q1 FY27 revenue up 6% and Underlying EBITDA up 20%
In its October 2026 Q1 27 trading update, management at Experience Co outlined unaudited sales revenue of $32.8 million, up 6% on the prior corresponding period (PCP, being Q1 FY26). Underlying EBITDA reached $4.8 million, a 20% increase.
Underlying EBIT came in at $1.7 million, up 37%. All figures are unaudited and relate to continuing operations, which exclude the Wild Bush Luxury business unit following completion of its divestment on 1 May 2026.
Earnings grew faster than revenue, which points to operating leverage across the group. The table below sets out the headline metrics.
| Metric ($ million) | Q1 27 | Q1 26 | Change |
|---|---|---|---|
| Skydiving revenue | 13.2 | 12.1 | 9% |
| Adventure Experiences revenue | 19.6 | 18.8 | 4% |
| Sales revenue | 32.8 | 30.9 | 6% |
| Underlying EBITDA | 4.8 | 4.0 | 20% |
| Underlying EBIT | 1.7 | 1.2 | 37% |
Management’s commentary on the quarter included the following points:
- September was stronger, following more weather-impacted trading in August after a solid start in July.
- Volume performance varied by site due to differing impacts of weather, international customer visitation trends and domestic consumer sentiment.
- The group recorded a modest margin improvement.
When big ASX news breaks, our subscribers know first
Skydiving delivers strongest Q1 tandem volume in four years
The Skydiving segment generated revenue of $13.2 million, up 9% on the PCP, with total tandem volume up 7%. Management noted that Q1 is a seasonally lower volume quarter for the segment.
Skydive Australia
Skydive Australia revenue rose 12%, driven by volume growth of 7% and improved third-party maintenance and aircraft cross-hire revenue for Performance Aviation. Volume growth at drop zones in NSW, VIC and SEQ offset softer trading at the Tropical North Queensland drop zones.
Total bookings were ahead of the PCP in each month of the quarter.
Skydive New Zealand
Skydive New Zealand revenue grew 4% on volume growth of 7%. Both drop zones were unable to operate for much of the second half of August because of weather, a gap offset by a strong September.
Booking levels remain ahead of the PCP at both drop zones.
Higher revenues and volumes improved the segment’s operating leverage, which offset some margin pressures in Adventure Experiences. Annual tandem passengers across Skydive Australia and New Zealand were 114k in FY24, 119k in FY25 and 117k in FY26.
Adventure Experiences lifts revenue 4% on higher spend per customer
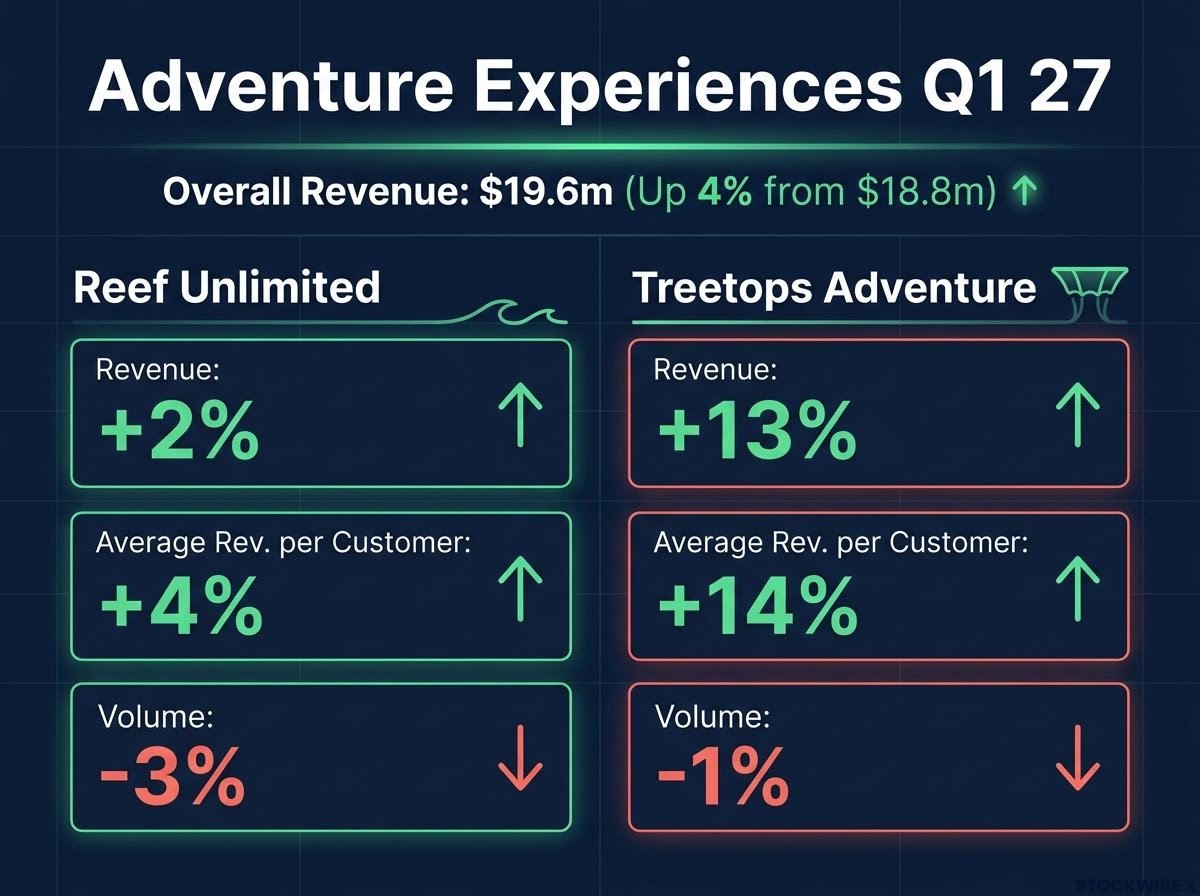
Adventure Experiences revenue reached $19.6 million, compared with $18.8 million in the PCP. Management attributed the 4% growth to higher average revenue per customer across both business units.
Reef Unlimited
Reef Unlimited revenue increased 2%. Average revenue per customer rose 4%, reflecting historical rate increases and a stronger contribution from the Reef Magic pontoon experience.
Volume fell 3%, reflecting generally less favourable weather conditions and softer Cairns/Port Douglas regional visitation.
Treetops Adventure
Treetops Adventure revenue grew 13%, with average revenue per customer up 14%. Management cited historical rate increases, site mix and a continued focus on improving ancillary customer spend, while volume declined 1% on mixed performance across sites and weather impacts.
West Beach Adventure (Adelaide) was integrated within Treetops Adventure during the quarter following its acquisition on 30 June 2026.
The West Beach Adventure acquisition cost $1.25 million and added a site with about $450,000 in pro-forma EBITDA, marking Treetops Adventure’s first entry into South Australia.
Q1 27 volume as a percentage of the PCP was 107% for Skydiving, 97% for Reef Unlimited and 99% for Treetops.
Why yield and operating leverage matter for experience operators
Operating leverage describes what happens once fixed costs are covered: additional revenue can lift earnings faster than it lifts sales. Underlying EBITDA rose 20% on revenue growth of 6%, consistent with that pattern.
Underlying EBITDA differs from statutory profit. It is a non-AAS measure that adjusts EBITDA for acquisition-related transaction costs, restructure costs and other significant items, and net gains and losses on the sale of assets. The unaudited figures are post AASB 16.
Yield, meaning revenue earned per customer, was also visible in the Treetops result, where revenue rose 13% on a 1% volume decline.
October trading and what happens next for Experience Co
The October update outlined the following trading conditions:
- Skydive Australia and Skydive New Zealand both recorded strong performance during the Golden Week trading period.
- Reef Unlimited recorded strong bookings during Golden Week, but trading is being impacted by regional visitation levels.
- Treetops Adventure volumes remain softer than the PCP to date, with management focused on yield.
Management also stated that further progress was made on negotiations with Inflite Group during the quarter. The stated upcoming events are:
The Inflite Aviation deal terms outlined in July proposed a MergeCo valued at about $110m enterprise value, with Experience Co receiving $41m cash, a $5m vendor note and a 32.5% equity stake.
- An Intractable Bargaining Determination hearing between the Australian Workers Union and Skydive Australia, scheduled for early November.
- A binding decision on that determination, due to be handed down by February 2027.
- The Experience Co AGM on 18 November 2026, where an update on the Inflite Group negotiations is to be provided.
Don’t Miss the Next Consumer Discretionary Winner
Get FREE breaking ASX news on consumer stocks delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors using Big News Blast to stay ahead of the market. Click the “Free Alerts” button to start receiving alerts the moment market-moving news breaks.