
OFX Transaction Process Deed terminates as Equals talks continue
OFX Group (ASX: OFX) has confirmed that its Transaction Process Deed with Alakazam Holdings Bidco Limited (“Equals”) has terminated and exclusivity has ended. Discussions are ongoing on a non-exclusive basis, and the company also released a 2Q27 trading update on 26 October 2026.
The deed was announced on 23 July 2026 and amended on 24 September 2026. It covered the proposed “all-cash acquisition of 100% of the issued share capital” of OFX by Equals, the direct owner of UK-based international payments company Equals Group Limited, by way of a scheme of arrangement.
Under the deed, Equals was scheduled to re-confirm on 23 October 2026 that it did not intend to withdraw or amend the terms of the indicative proposal or reduce the scheme consideration of $1.00 per share. It did not do so, and the deed terminated as a result.
The original indicative proposal valued OFX at $1.00 cash per share, a 108% premium to its undisturbed price, and carried a small cash adjustment mechanism tied to OFX’s available cash at implementation.
OFX shareholders do not need to take any action at this time, and there is no certainty that a transaction will proceed.
How a scheme of arrangement works
A scheme of arrangement is a court-approved process commonly used in Australia to complete company takeovers. If it proceeds, an acquirer takes ownership of all of a company’s shares on agreed terms.
Exclusivity is an arrangement that stops a target company from engaging with other potential bidders during a set period. With exclusivity ended, the discussions between OFX and Equals now continue on a non-exclusive basis.
When big ASX news breaks, our subscribers know first
2Q27 trading update: momentum builds despite weak business confidence
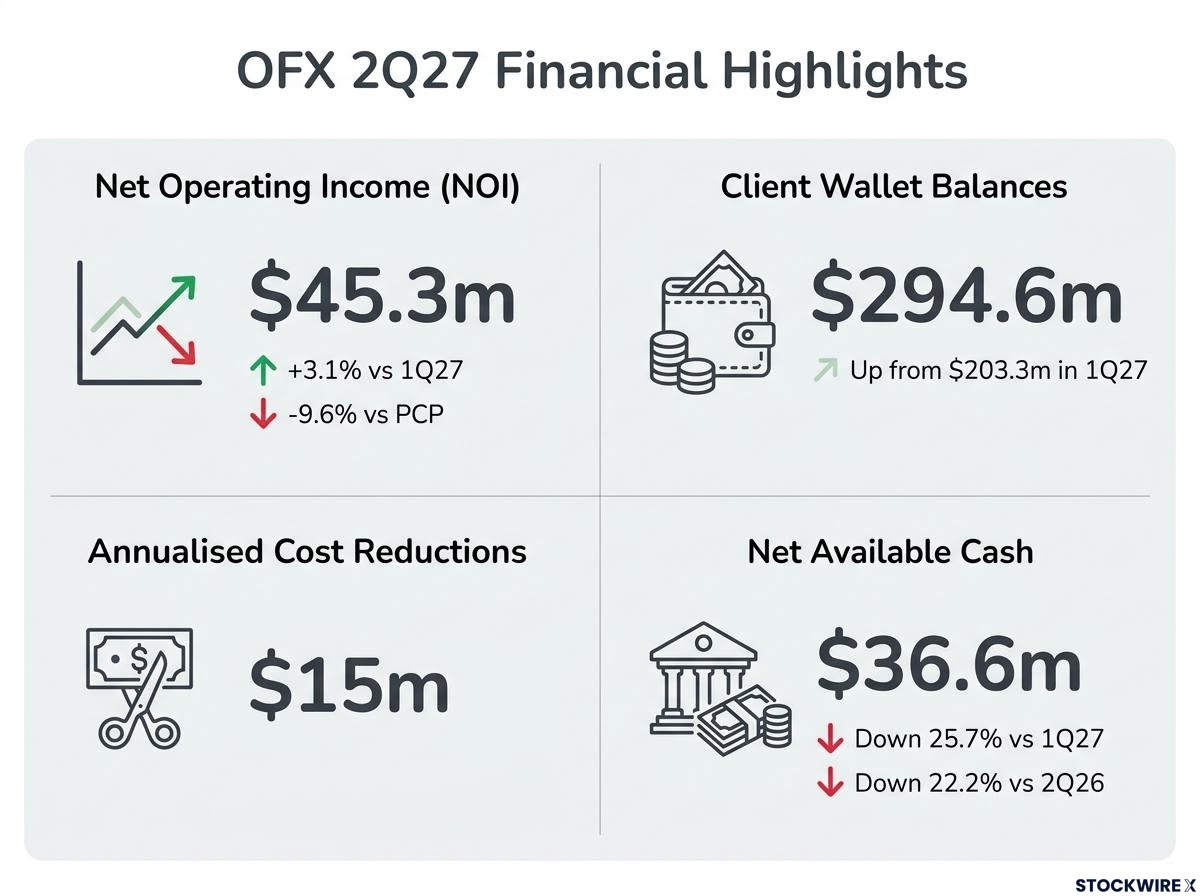
The trading update covers the second quarter of OFX’s financial year ending 31 March 2027 (2Q27). Net Operating Income (NOI) was $45.3m, up 3.1% on 1Q27 as positive trading momentum continued.
NOI was down 9.6% versus the prior corresponding period (PCP), which OFX attributed to the backdrop of low business confidence that has persisted in most of its markets.
OFX’s FY26 results showed NOI down 8.5% to $196.6m and underlying EBITDA down 56.4%, as platform investment and macro headwinds weighed on earnings, which frames the current quarter’s modest sequential recovery.
| Metric | 2Q27 | vs 1Q27 | vs PCP |
|---|---|---|---|
| NOI | $45.3m | +3.1% | -9.6% |
| Corporate revenue | $28.4m | +6.9% | n/a |
| High Value Consumer revenue | $13.3m | +2.8% | n/a |
| Enterprise revenue | $2.8m | -31.3% (against a strong 1Q27) | n/a |
| Non-FX revenue | $1.0m | +31.0% | +178.9% |
Corporate drivers
Corporate revenue reflected improved cross-currency margins, from pricing activity and improved contribution from forwards, and higher cross-currency transaction volumes. Key metrics against 1Q27:
- Cross-currency margins up 3bps to 0.6%
- Cross-currency transaction volumes up 1.4%
- Average Transaction Values (ATVs) steady quarter on quarter
- Corporate Active Clients down 5.0%, mostly reflecting the runoff of Firma and OLS clients, most of which are lower value
- Corporate Active Clients down 0.9% excluding Firma and OLS
- Transactions per Corporate Active Client up 2.0%
- Corporate Average Revenue Per Client $4.0k, up 2.7%
High Value Consumer returned to revenue growth on higher ATVs.
Non-FX growth and interest income
Non-FX revenue grew across all products versus 1Q27: Card revenue was up 31.5%, Pay by Card up 27.9% and Subscription up 33.5%. Approximately 11.7% of all active clients on the NCP now use multiple products, up 1.6% on 1Q27.
Client wallet balances were $294.6m at the end of September, up from $203.3m at the end of 1Q27. Interest income on Group cash and client wallet balances was $3.1m in the quarter, up 27.2% on 1Q27.
Cost reductions and cash position
Underlying operating expenses for 1H27 are expected to be $85m to $87m, including bad debts expense of $3.8m. That figure includes approximately $1.6m of adjustments to existing items not expected to recur, and $1.1m of Consumer losses, with additional controls implemented in the quarter to reduce Consumer losses.
The residual bad debt expense is in line with typical levels. None of these losses relate to the cyber incident.
OFX said it remains focused on disciplined cost management and continues to target positive operating leverage for FY27. At the end of the quarter, it executed approximately $15m of annualised cost reductions, which were predominantly Opex related.
The Group’s balance sheet remains healthy, although cash generation was lower versus PCP given lower revenue and continued capex investments in NCP. Net Cash Held was $63.3m.
After deducting collateral and bank guarantees, Net Available Cash totalled $36.6m, down 25.7% on 1Q27 and down 22.2% on 2Q26.
All 2Q27 and 1H27 financial information presented is unaudited and subject to external audit review.
Don’t Miss the Next Fintech Move Before the Market Does
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already receiving real-time alerts on Tech, Finance and other non-resource sectors. Click the “Free Alerts” button at Big News Blast to stay ahead the moment market-moving announcements break.