
Westpac flags $41 million RAMS litigation item and credit disclosure changes ahead of FY26 results
In an ASX release dated 19 October 2026, Westpac Banking Corporation flagged items that will impact its Westpac FY26 results, scheduled for Monday, 2 November 2026. The items are a $41 million (pre-tax) Notable Item, revised stressed exposure categories, and a reclassification of some hardship arrangements.
The update gives investors early visibility of changes intended to improve alignment between credit quality and provisioning disclosures. The announcement is unaudited and all amounts are in Australian dollars.
When big ASX news breaks, our subscribers know first
RAMS litigation matters: $41 million Notable Item in 2H26
Westpac recognised a Notable Item of $41 million (pre-tax) in 2H26 for the expenses related to the RAMS litigation matters and associated legal costs.
The announcement does not disclose case background or outcomes. Because the amount is quantified and isolated as a Notable Item, investors can separate it from underlying performance when the full results arrive.
The RAMS portfolio sale completion to Pepper Money, KKR-managed credit funds and PIMCO managed funds lifted Westpac’s CET1 ratio by about 23 basis points, though the sale price and any accounting gain or loss were not disclosed.
Revised credit quality reporting explained
What is changing in stressed exposures
Westpac said the categories within stressed exposures have been revised to improve alignment between credit quality and provisioning disclosures. The changes are:
- A new category has been created for individually assessed exposures, which includes exposures with an individually assessed provision.
- The impaired exposures category will no longer be reported.
- Former impaired exposures have been allocated across individually assessed exposures, non-performing 90+ days past due, and non-performing less than 90 days past due.
Stressed exposures are loans where the borrower shows signs of difficulty, grouped by credit grade. TCE is the base used to express these exposures as a percentage, in the same way the announcement presents them. Aligning these categories with provisioning (money set aside for expected loan losses) can help investors judge how loan book risk compares with the buffers held against it.
Revised comparatives
Attachment 1 of the announcement summarises the revised comparatives. Stressed exposures by credit grade, as a % of TCE, were as follows:
| Metric (% of TCE) | As at 31 March 2026 | As at 30 Sept 2025 | Change |
|---|---|---|---|
| Individually assessed | 0.08% | 0.07% | Up 0.01 percentage points |
| Non-performing, 90+ days past due | 0.34% | 0.38% | Down 0.04 percentage points |
| Non-performing, less than 90 days past due | 0.30% | 0.32% | Down 0.02 percentage points |
| Watchlist and substandard | 0.44% | 0.51% | Down 0.07 percentage points |
| Total stressed exposures | 1.16% | 1.28% | Down 0.12 percentage points |
Total stressed exposures were lower at 31 March 2026 than at 30 September 2025, declining from 1.28% to 1.16% of TCE.
Westpac’s 1H26 stressed exposures and mortgage delinquencies both improved in the half-year result, alongside a 10 basis point impairment charge as the bank revised its economic forecasts.
Individually assessed exposures and hardship reclassification
Individually assessed exposures movement
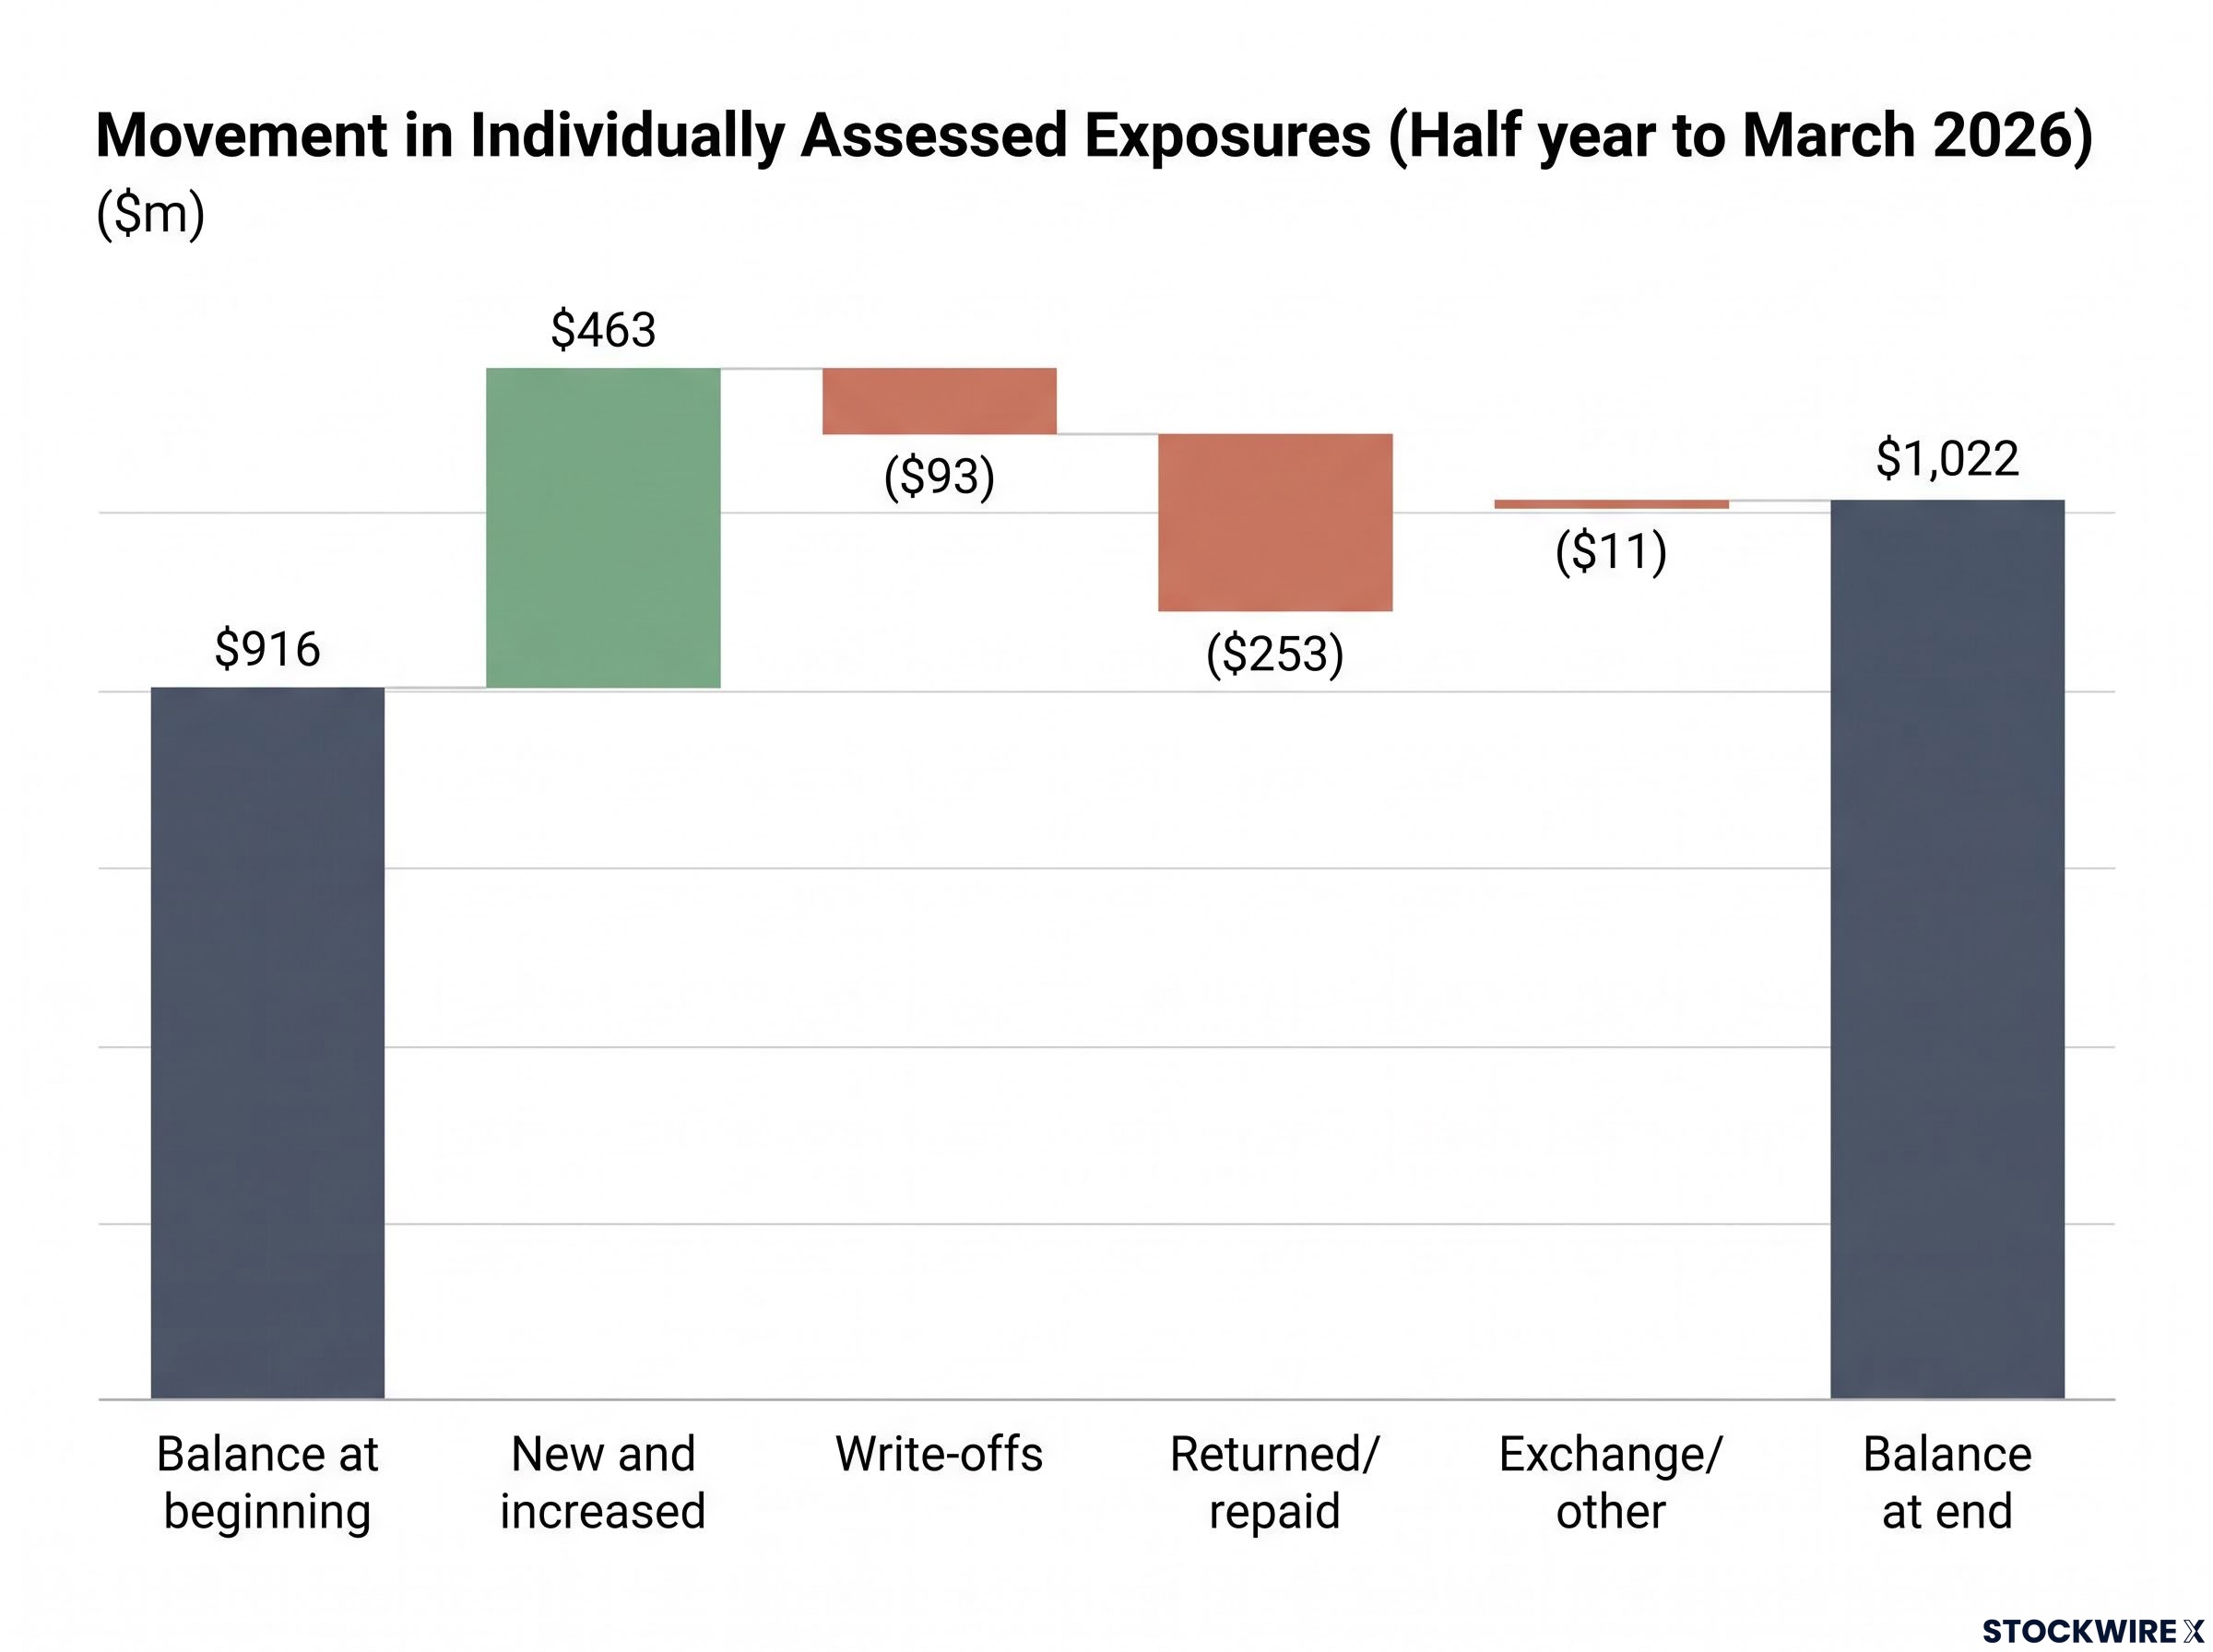
For the half year to March 2026, the movement in individually assessed exposures (in $m) was:
- Balance at beginning of the period: $916 million
- New and increased: $463 million
- Write-offs: $93 million
- Returned to performing or repaid: $253 million
- Exchange rate and other adjustments: -$11 million
- Balance at end of the period: $1,022 million
For the full year to September 2025, the balance moved from $663 million to $916 million.
Individually assessed provisions to individually assessed exposures were 59.68% at March 2026, compared with 58.81% at September 2025. Individually assessed exposures to gross loans were 0.11% at both dates.
By segment, individually assessed exposures to TCE were:
- Business & Wealth: 0.31% (versus 0.24% at September 2025)
- Institutional: 0.08% (versus 0.09%)
- Westpac New Zealand: 0.13% (versus 0.14%)
Hardship arrangement reclassification
A reclassification of some hardship arrangements impacted 90+ day mortgage delinquencies. Westpac stated the impacts to credit quality, credit provisioning and capital were immaterial, and comparatives have not been restated.
For comparability, the Mortgage 90+ day delinquencies presented in the FY26 Investor Discussion Pack will be revised. The revision will include an increase of 3bps at September 2025 and 5bps at March 2026.
What investors should watch on 2 November
Westpac’s Full Year 2026 results are scheduled to be announced on Monday, 2 November 2026. The revised credit metrics and the RAMS Notable Item are the items flagged ahead of that release.
The announcement does not address profit, dividends or guidance. It was authorised for release by Sarah Donnelly, Company Secretary.
Contacts for further information
Hayden Cooper, Group Head of Media Relations: +61 402 393 619
Justin McCarthy, General Manager, Investor Relations: +61 422 800 321
Get Banking News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX news from Big News Blast within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button to get the next major financials update in your inbox the moment it breaks, so you stay ahead of the market.