The Food and Drug Administration (FDA) approved 46 novel drugs in 2025. By 9 October 2026, it had matched that figure again. Over the same stretch, the Center for Drug Evaluation and Research (CDER), the division that reviews most new drugs, went through its fifth director, and the commissioner left.
That gap is the signal many investors may be misreading. FDA leadership turnover has not stopped decisions from arriving, but strong output is not the same as predictable reviews.
Marty Makary left on 12 May 2026. Kyle Diamantas is acting commissioner, and Heidi Overton is the reported nominee awaiting Senate confirmation. Permanent directors for CDER and the biologics division (CBER) were only named in September 2026.
For small-cap biotech holders, that matters. A few months of process friction can decide whether a company raises money on good terms or bad ones.
Here are the regulatory-health signals worth tracking, plus two live small-cap cases that show where process risk actually bites.
Who is running the FDA now, and how unusual is the churn?
Start with the count. In 2025, the agency lost three CDER directors and two CBER directors. Veteran oncology regulator Richard Pazdur retired at the end of that year after a brief stint leading CDER.
The churn in one number CDER reached its fifth director since January 2025, according to BioPharma Dive (1 April 2026).
Then the commissioner went. Makary left after about 13 months, with reports split on whether he resigned or was pushed out. Reuters also reported that Stephen Hahn and Brett Giroir had been floated as replacements. BioPharma Dive reported on 29 May 2026 that layoffs and departures had raised questions about whether the agency had the staff for labour-intensive new policies.
The current roster:
- Kyle Diamantas: acting commissioner, formerly deputy commissioner for food
- Heidi Overton: White House policy aide, reported nominee; sources differ on whether she is formally nominated or a reported candidate, and Senate confirmation is required
- Michael Davis: permanent CDER director, named September 2026
- Karim Mikhail: permanent CBER director, named September 2026
The centre directors are the newest change. The commissioner seat is the unresolved one.
For you, a permanent director ends the acting-leader era but does not by itself restore the consistent signals companies depend on. Treat September’s appointments as a starting point, not a verdict.
When big ASX news breaks, our subscribers know first
Has the output actually slipped? What the numbers show and what they hide
On the headline numbers, the answer looks like no. CDER approved 46 novel drugs in 2025 despite an 18% reduction in force, and met or exceeded its review deadline for 44 of 46 (96%). The 2026 running list hit 46 by 9 October, with Hovilpri as the latest; a DCAT review had counted 40 through 11 September.
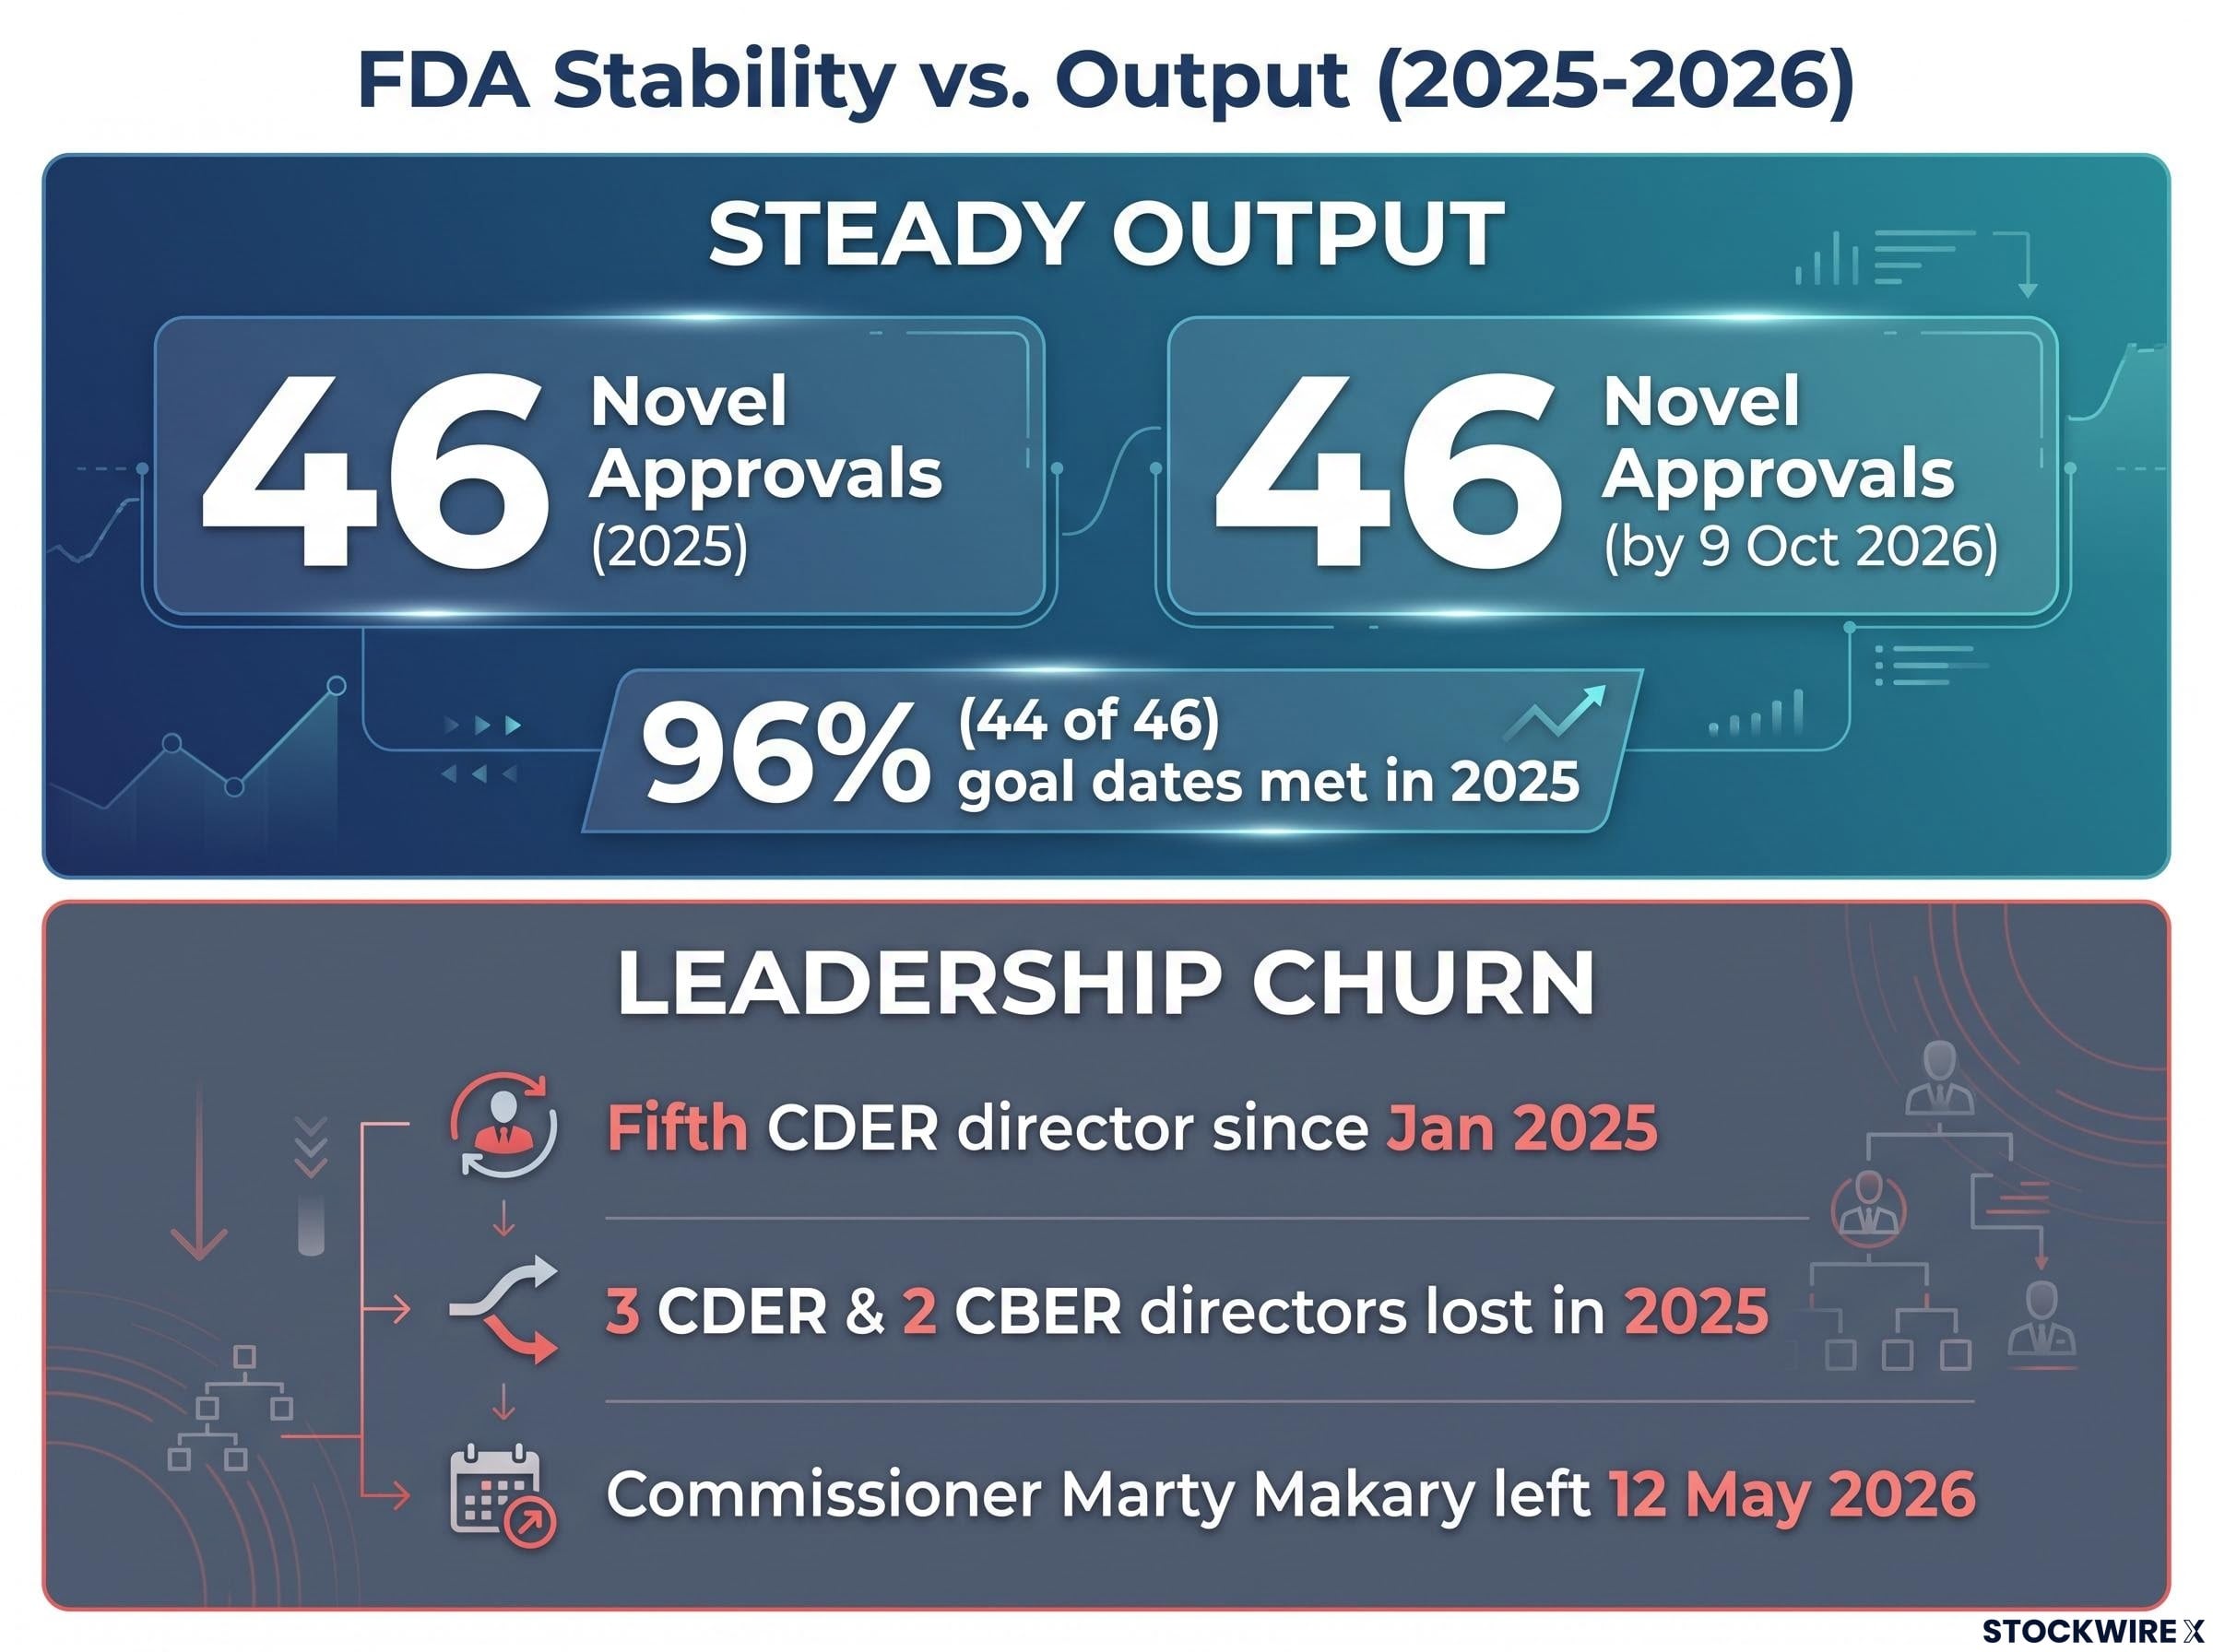
That deadline is the PDUFA goal date, the target date by which the FDA commits to act on an application under the Prescription Drug User Fee Act. Meeting it means the agency made a decision on time. It does not mean the decision was an approval.
The FDA’s PDUFA performance reports to Congress are the primary record of goal date results, so investors can check the 96% on-time figure against official data rather than relying on secondhand summaries.
| Metric | What it measures | What it misses | Current reading |
|---|---|---|---|
| Novel approvals | Total output | How many cycles each took | 46 (2025); 46 by 9 Oct 2026 |
| Goal dates met | Action by deadline | First-cycle approval | 96% in 2025 |
| PDUFA extensions | Deadline slippage | Reasons for delay | No authoritative aggregate found |
| Complete response letters | Rejections pending fixes | Severity of issues | No CDER-wide count found |
What the data cannot yet tell you
A complete response letter (CRL) is the FDA’s formal notice that it cannot approve an application in its current form. No authoritative public tally of CRLs or extensions exists, and one claim that extensions doubled in 2025 could not be independently confirmed. The available evidence does point to manufacturing-related CRLs: an August 2026 review in the American Journal of Health-System Pharmacy counted three for non-oncology therapies since its prior update.
The approval count tells you the agency is still producing decisions. Only CRL and extension trends can tell you whether those decisions arrive cleanly, so you should track all three.
Why throughput held, and why 2027 may be the real test
If leadership churned this hard, why did output hold? Four structural buffers carried the load.
The buffers
- User-fee funding. PDUFA VII, authorised through FY2027, pays to retain and hire review staff.
- Career reviewer continuity. Scientists, project managers and division staff keep active files moving regardless of who sits at the top.
- Workload shifting. Divisions redistribute work, preserving formal actions but creating handoffs and less predictable communication.
- Deadline incentives. Goal dates push the agency to act on time.
The timing debate
One view holds that applications already assigned simply keep flowing, so 2026 counts would not reveal much. The opposing view says staffing losses hit consultation quality, inspection scheduling, meeting availability and hard cases first, with effects surfacing later. One market commentator suggested 2027 may be when change becomes visible; for now, he described it as business as usual.
The sources support the existence of this debate, not a consensus that 2027 is decisive. No attributable KFF or Brookings estimate of the effect was found, and PDUFA VIII talks are already underway.
A calm 2026 should not lull you into assuming stability. The stress points most likely to hurt a small-cap name are exactly the ones that lag.
Aldeyra and Unicycive: how process friction lands on small caps
These two companies stall in different ways. One is disputing the agency’s reasoning; the other is waiting on a vendor’s inspection.
Aldeyra: appealing to a higher office
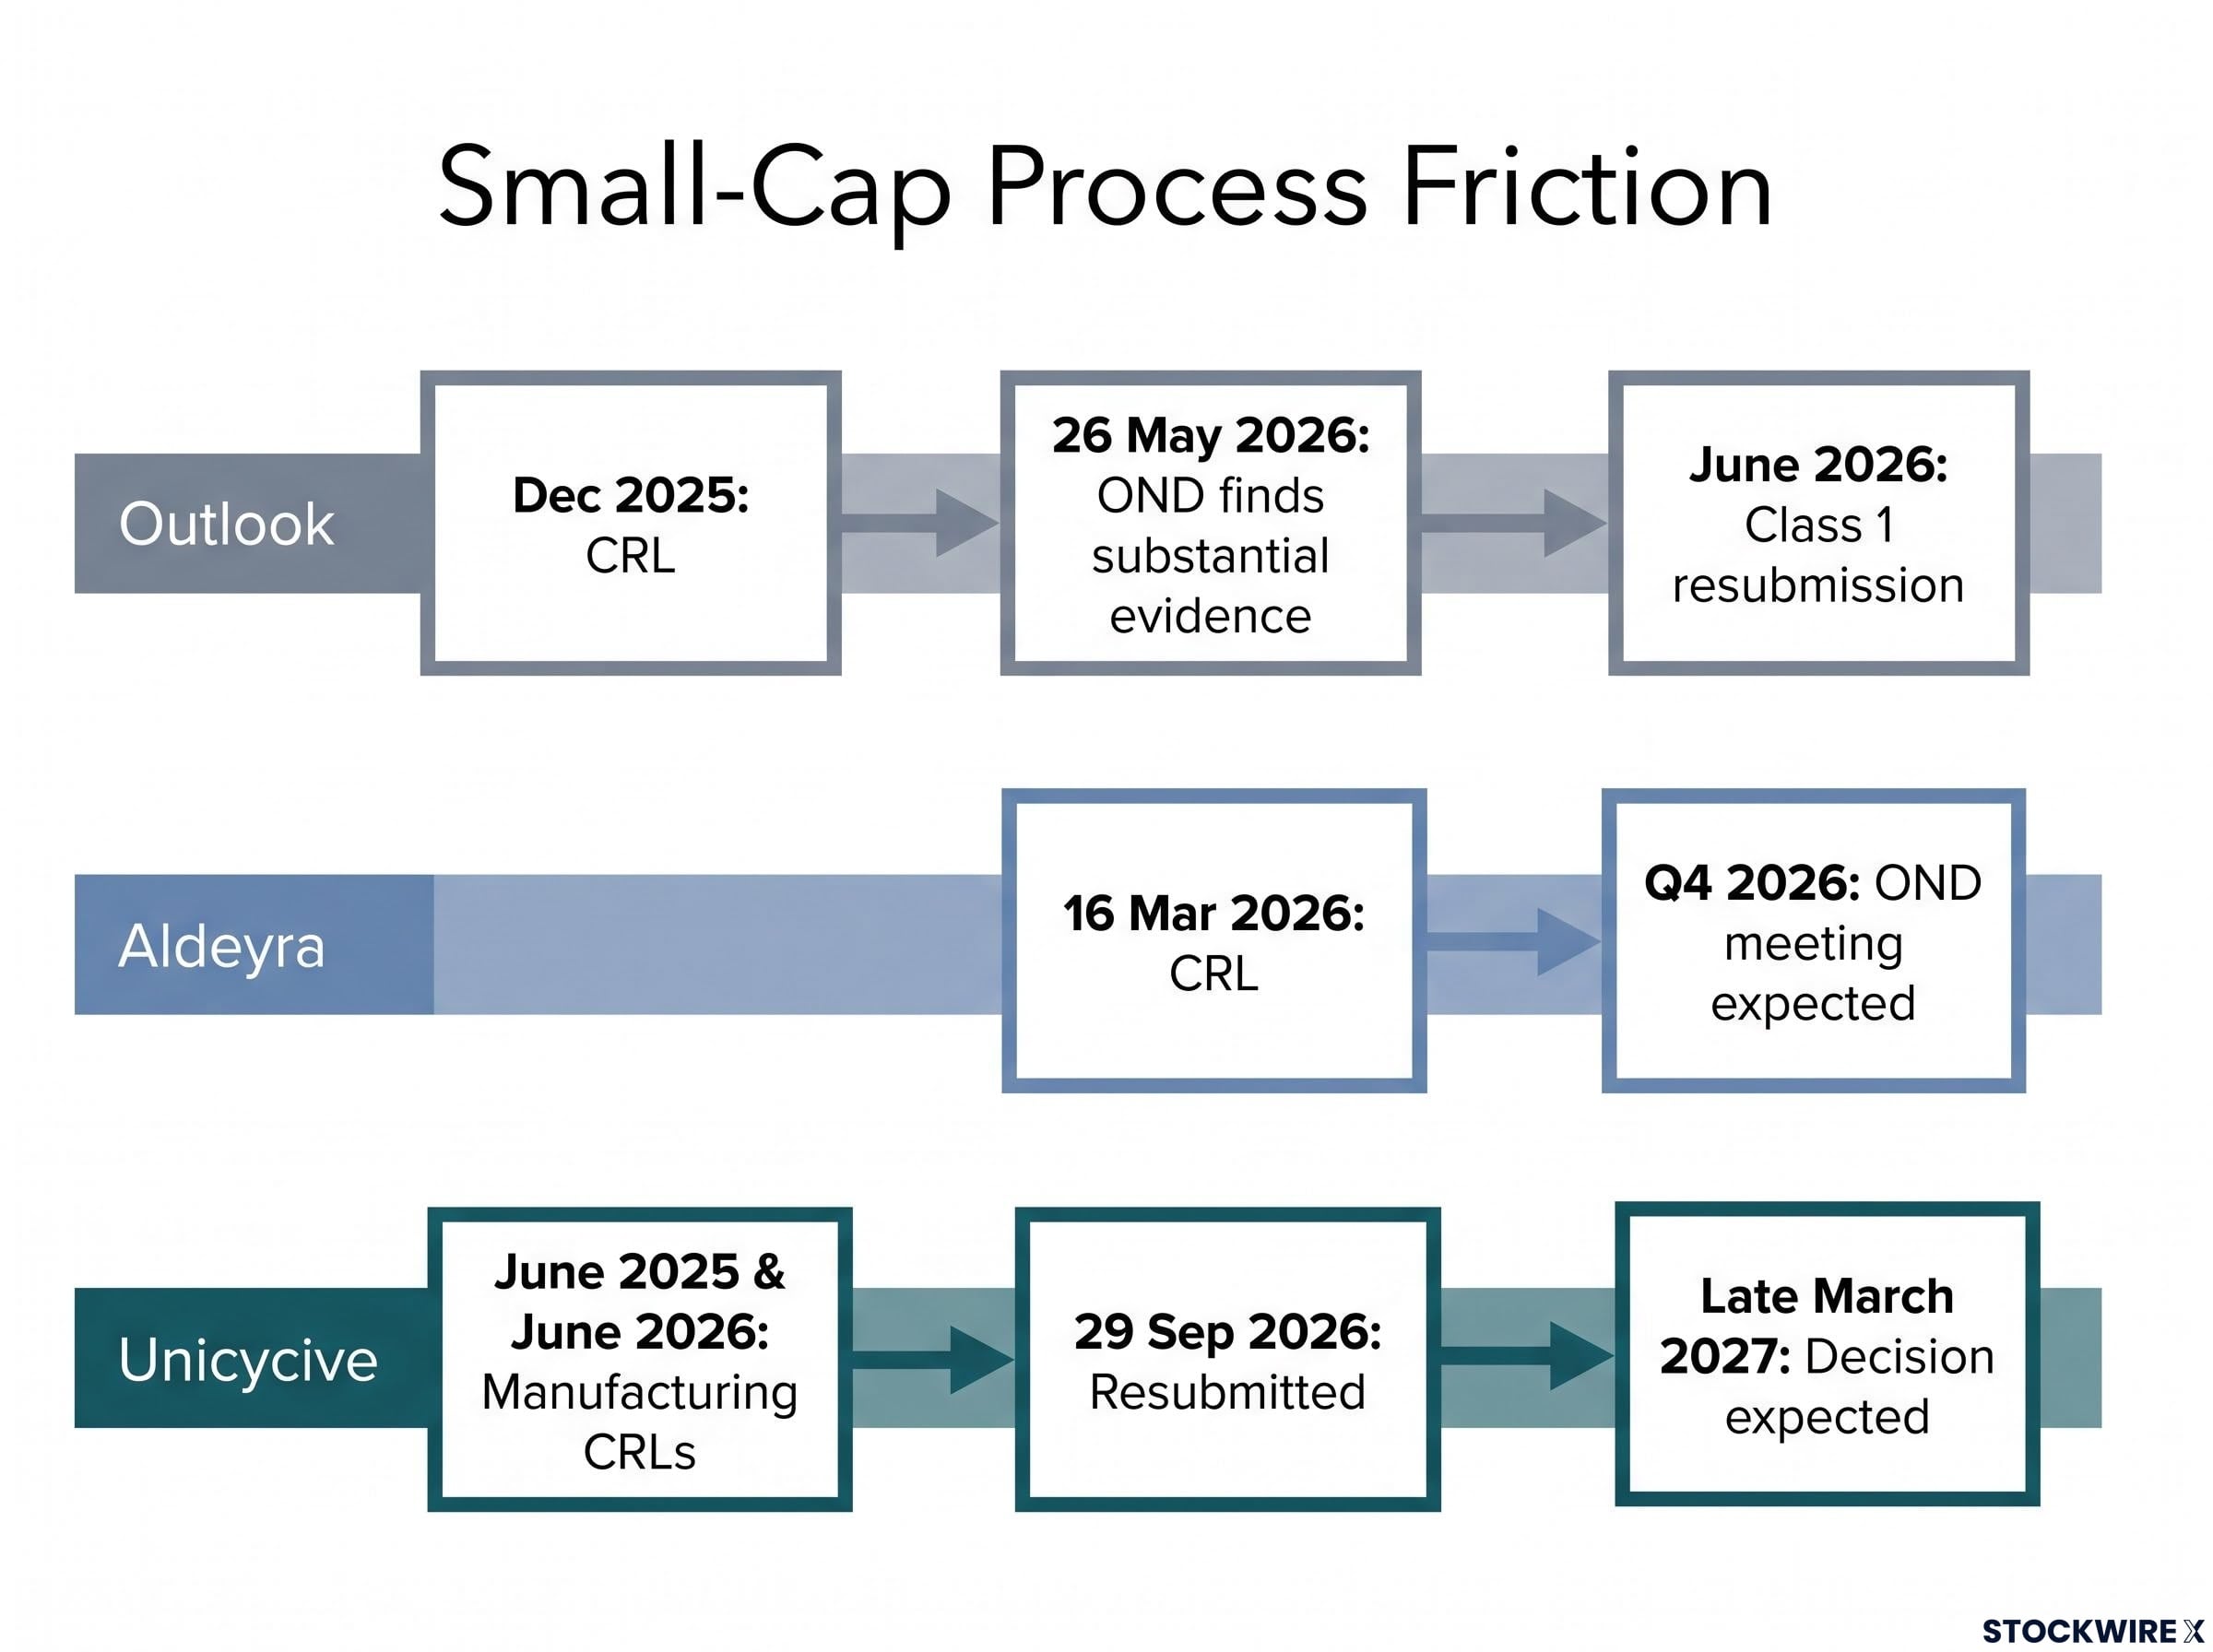
Aldeyra Therapeutics received a CRL for its dry eye drug reproxalap on 16 March 2026. According to the company, five of nine phase 3 studies hit statistical significance, and the FDA said no new trials were needed but wanted deeper analysis. After Type A and Type D meetings left it dissatisfied, Aldeyra said it would file a Formal Dispute Resolution Request with the Office of New Drugs (OND), with a meeting expected in Q4 2026.
The stakes are concrete. AbbVie holds an opt-in, with a $100 million payment tied to approval, and the stock traded around $0.80 per the original source.
The precedent is Outlook Therapeutics. After a December 2025 CRL, OND found on 26 May 2026 that substantial evidence of effectiveness had been established, and the FDA acknowledged a Class 1 resubmission in June 2026. Final approval was not confirmed in the research, and one source’s claim that Outlook “was approved after three CRLs” conflicts with filings. A commentator who owns Aldeyra sees a lower hurdle than Outlook faced and projects approval around early January; that is opinion, not fact.
Unicycive: the vendor problem
Unicycive received CRLs in June 2025 and June 2026, both tied to its original third-party manufacturing site rather than efficacy or safety. On 29 September 2026 it resubmitted with a second manufacturer, rated “No Action Indicated” after an FDA inspection in March 2024, adding chemistry and manufacturing data, 12 months of stability data and bridging data. The original site’s inspection had still not occurred, and the company expects a decision around late March 2027.
| Case | Friction | Status | Investor implication |
|---|---|---|---|
| Outlook | Dec 2025 CRL | Appeal won; resubmitted | Reversible, but another cycle |
| Aldeyra | 16 Mar 2026 CRL | Dispute pending | Outcome unresolved |
| Unicycive | Two manufacturing CRLs | Resubmitted 29 Sep 2026 | Inspection drives timetable |
Keep three milestones separate:
- Appeal granted: the FDA’s reasoning is overturned, not the drug approved
- Application accepted: review begins on a new clock
- Product approved: the drug can be sold
The question to ask of a small-cap biotech is not only whether its data are good, but whether it has cleared its manufacturing, inspection and dispute dependencies.
Regulatory risk investing is not unique to biotech: a single rule change can reprice a company overnight, and the lesson is to map which decisions, inspections or appeals a business depends on before they resolve.
Faster approvals or looser safeguards? Reading the risks on both sides
Before weighing the arguments, get the terms straight:
- Action by PDUFA date: the FDA decided on time, either way
- First-cycle approval: approved on the first submission
- CRL: a rejection listing issues to fix before resubmission
- Formal dispute resolution: an appeal to a higher FDA office
The distinction headlines blur A 96% on-time rate measures action by the PDUFA date. It says nothing about how many drugs won first-cycle approval.
Critics, citing former staff, saw Makary as favouring speed over caution. On that side, the risks are inadequate inspections, unresolved manufacturing deficiencies and immature efficacy evidence; the three manufacturing CRLs in the August review show those checks still bite.
Industry argues the opposite. The U.S. Chamber of Commerce, in 15 October 2026 comments on PDUFA VIII, said too many CRLs go to applications that could be approved. That is an industry position, not an FDA finding.
Outlook’s appeal win does not guarantee Aldeyra’s, and cash burn continues through each extra cycle. For you, a CRL is not automatically proof a drug failed, and speed is not automatically proof of quality.
Because a manufacturing CRL can land as an overnight gap-down that no stop-loss can catch, position sizing is the one risk variable a holder controls before a dated catalyst arrives, and it matters most when each extra review cycle burns cash.
What to watch while the commissioner search continues
Turn the unease into dated checkpoints:
- Commissioner decision: a choice is possibly before the new year; watch for Senate action on Overton while Diamantas acts. A steady leader should eventually show up in extension and CRL patterns.
- Aldeyra’s OND meeting, Q4 2026: a direct test of whether disputes reverse CRLs.
- Unicycive filing acceptance: expected within 30 days of resubmission.
- PDUFA VIII negotiations: they shape funding beyond FY2027.
Company-level checkpoints
Unicycive’s original-site inspection remains the swing factor ahead of its expected late March 2027 action date. Exact action dates for Unicycive and Outlook were not found, so verify them in company filings. If deeper effects appear, 2027 is the likeliest window.
Each item is checkable, which tells you whether risk is rising or fading.
Reading regulatory health without overreacting to the headlines
The FDA is still producing decisions. The real variables are leadership continuity and how predictably individual applications move, and the strain may not show until 2027.
For small caps, the risk sits in manufacturing, inspection and dispute dependencies, not the approval tally. Before sizing a position, check where the company stands on each and what its next dated catalyst is.
This is analysis, not a recommendation. Forward-looking views here are speculative and subject to change based on regulatory developments and company performance.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.