
FY26 earnings guidance reinstated at $2.4m to $2.7m Underlying Group EBITDA
Mayfield Childcare (ASX: MFD) has reinstated its FY26 earnings guidance, now expecting Underlying Group EBITDA of $2.4 million to $2.7 million for the year ending 31 December 2026. The update follows completion of its head office restructure and nine months of actual trading.
The range compares with $2.3 million reported in FY25, an increase of 4% to 17%, notwithstanding challenging operating conditions across the early childhood education and care sector. The guidance sits below the original FY26 guidance announced on 27 February 2026, which was withdrawn on 10 July 2026.
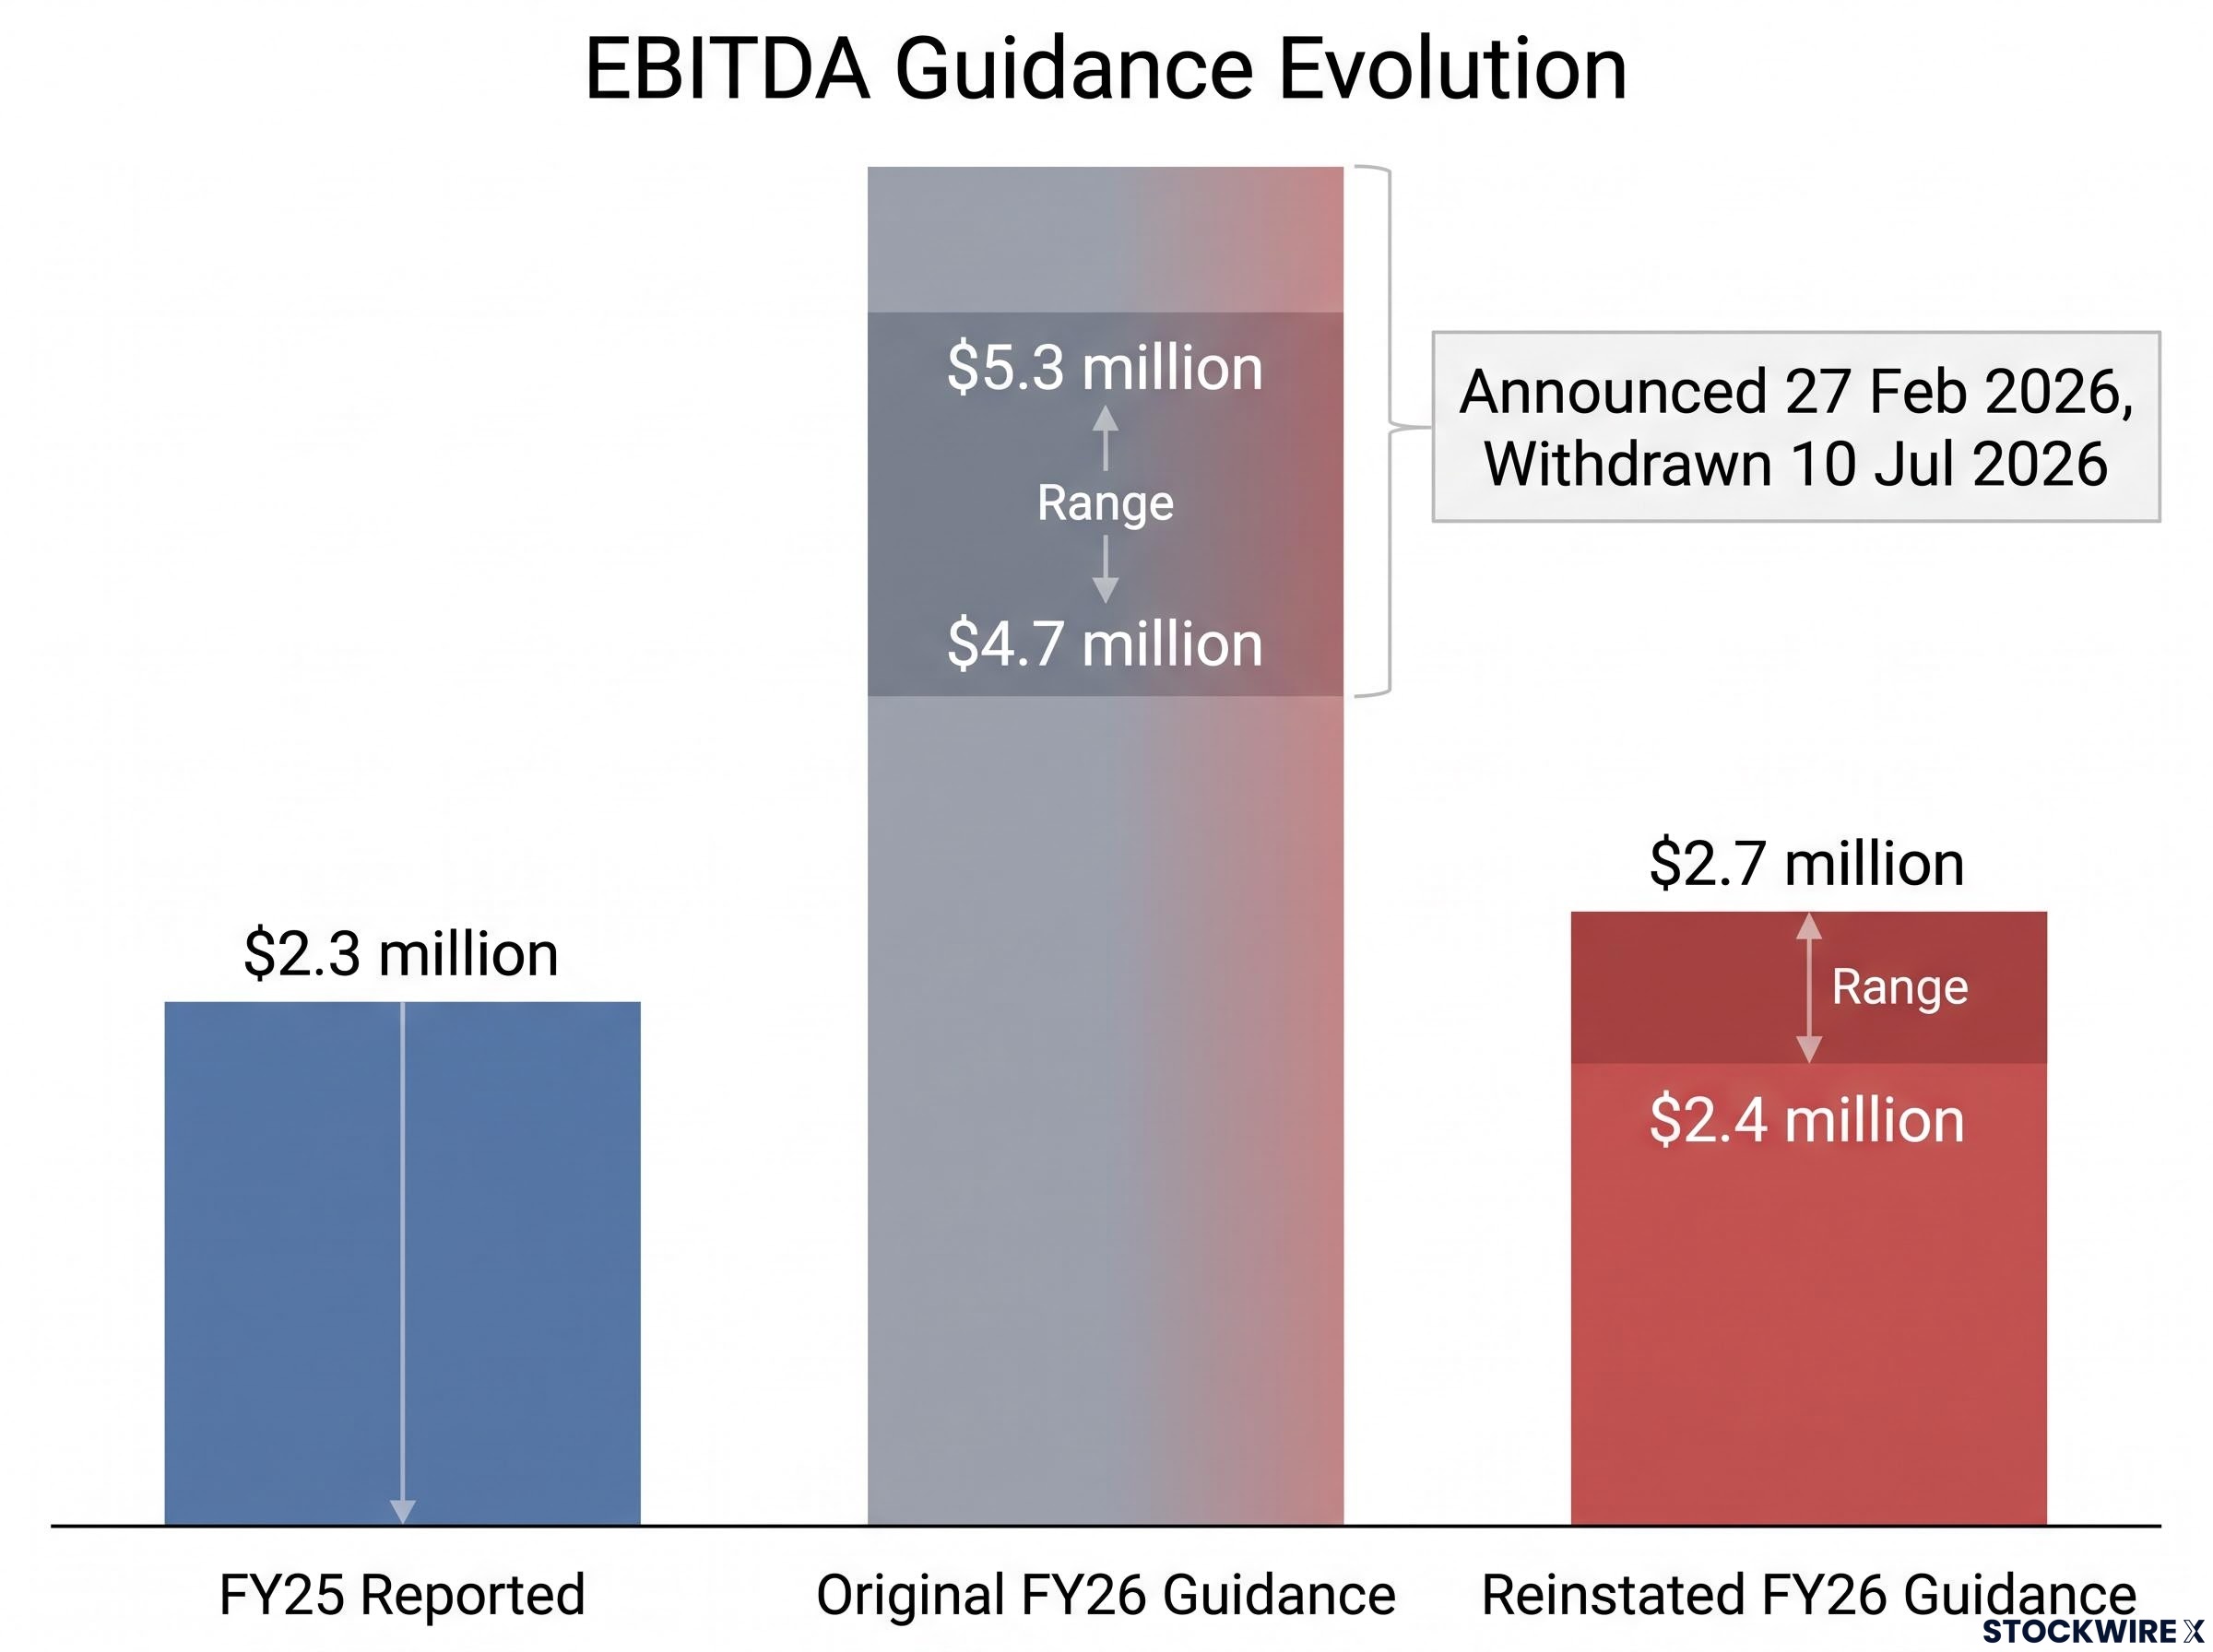
The FY26 guidance includes approximately $0.4 million of one-off restructuring and takeover-related costs. Excluding these costs, FY26 Underlying Group EBITDA would be $2.8 million to $3.1 million.
The Company states that disclosing this adjusted measure gives shareholders additional information on the impact of these expenses on expected FY26 operating performance. The announcement was re-lodged on 15 October 2026 with footnotes and definitions that were omitted through administrative oversight.
For investors, the return of guidance following the July withdrawal provides a defined baseline for FY26 earnings, built on actual trading results.
When big ASX news breaks, our subscribers know first
Why guidance sits below the original $4.7m to $5.3m
Mayfield withdrew its guidance on 10 July 2026 due to evolving and challenging market and operating conditions affecting the factors and assumptions underpinning it. At that time, the Company did not have a reasonable basis for revised guidance, including on the timing and benefit of planned cost reductions.
Actual trading for the nine months ended 30 September 2026, together with greater certainty over the timing and benefit of cost reductions, now provides that basis. The original guidance was $4.7 million to $5.3 million.
That original range was issued alongside the FY25 results, which showed revenue up 4.9% to $91.4 million and a second-half EBITDA recovery of $6.1 million.
The announcement identifies three principal factors, with the approximate impact of each on FY26 Underlying Group EBITDA relative to the original guidance shown below.
| Factor | Approx. EBITDA impact vs original guidance | Detail |
|---|---|---|
| Occupancy | $1.7M | Forecast FY26 average Group occupancy approximately 2.6 percentage points below the original assumption, following a decline in new enquiries between February and April 2026 that has not been fully recovered |
| Fee increases | $0.6M | Increases implemented later than assumed in the original forecast, with network-wide increases now implemented |
| One-off costs | $0.4M | Restructuring and takeover-related costs not included in the original guidance |
Current occupancy data points include:
- Group Spot occupancy is 56%, down from 59% in the prior period.
- Spot Occupancy excludes centres marked for divestment, as at the week commencing 5 October 2026.
The main drivers of the reduction are therefore identified and quantified, and network-wide fee increases are now in place.
Head office restructure to deliver $1.5m in annualised savings
Mayfield has completed its head office restructure, exiting 12 head office roles, ceasing selected service contracts and returning responsibility for selected activities to centres. The timing of expected savings is as follows:
- The restructure is expected to deliver approximately $1.5 million in annualised savings, including on-costs.
- Approximately $0.5 million is expected to be realised in FY26 and is included in the revised guidance.
- The full monthly saving is expected to be achieved from November 2026.
- The full annualised benefit is expected to be reflected in FY27.
The one-off restructuring expense is expected to be approximately $0.2 million, included in the approximately $0.4 million of restructuring and takeover-related costs. The balance comprises corporate advisory and legal costs incurred in connection with the off-market takeover offer by Embark Early Education Limited (ASX: EVO), which closed on 5 March 2026.
Embark’s unconditional takeover offer, declared in February 2026 after it had built a 20.45% stake, set the timeline for the advisory and legal costs now flowing through Mayfield’s FY26 earnings.
Because the restructure was implemented during FY26, the revised guidance reflects only a partial-year benefit from the reduced head office cost base. The full annualised benefit is expected to be reflected in FY27.
What is Underlying Group EBITDA?
Underlying Group EBITDA represents the Group’s earnings before interest, tax, depreciation and amortisation, calculated excluding the impact of AASB 16 Leases. In simple terms, it measures operating earnings before financing costs, tax and certain accounting charges.
It is a non-IFRS financial measure not prescribed by the Australian Accounting Standards. The Directors consider that it assists in understanding the Company’s operating performance and is consistent with internal management reporting.
The FY26 guidance has been prepared on the same basis as the FY25 comparative and the original FY26 guidance. This allows like-for-like comparison, while the adjusted figure shows the impact of one-off costs.
Key assumptions and outlook
The revised guidance was prepared by management using actual results for the nine months ended 30 September 2026 and forecasts for the three months ending 31 December 2026. The key assumptions include:
- Group occupancy averaging approximately 52.3% for the quarter ending 31 December 2026, taking into account the anticipated seasonal reduction in occupancy during December.
- No further fee increases assumed for the remainder of FY26.
- No further material changes to employee remuneration costs assumed for the remainder of FY26.
- No material changes to Child Care Subsidy arrangements or other relevant government funding or regulatory settings during the remainder of FY26, other than changes already announced and reflected in the forecast.
- Trading results of centres approved for divestment included until their anticipated dates of divestment, with any gains or losses from those divestments excluded from Underlying Group EBITDA.
The guidance has been reviewed and approved by the Board. The forecast financial information has not been audited or reviewed by the Company’s auditor, and the guidance is subject to risks and uncertainties, including changes in occupancy, operating costs and market conditions, which may cause actual results to differ materially.
Company priorities
Mayfield’s priorities for the remainder of FY26 and into FY27 are to rebuild occupancy through improved enrolment conversion and local marketing, maintain centre-level labour efficiency, and realise the full benefit of the completed head office restructure.
Mayfield will provide a further update on trading and the outlook for FY27 with its full year results.
Don’t Miss the Next Consumer Discretionary Winner
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive alerts the moment market-moving consumer news breaks.