

PointsBet flags H1 FY27 group revenue of approximately $113m
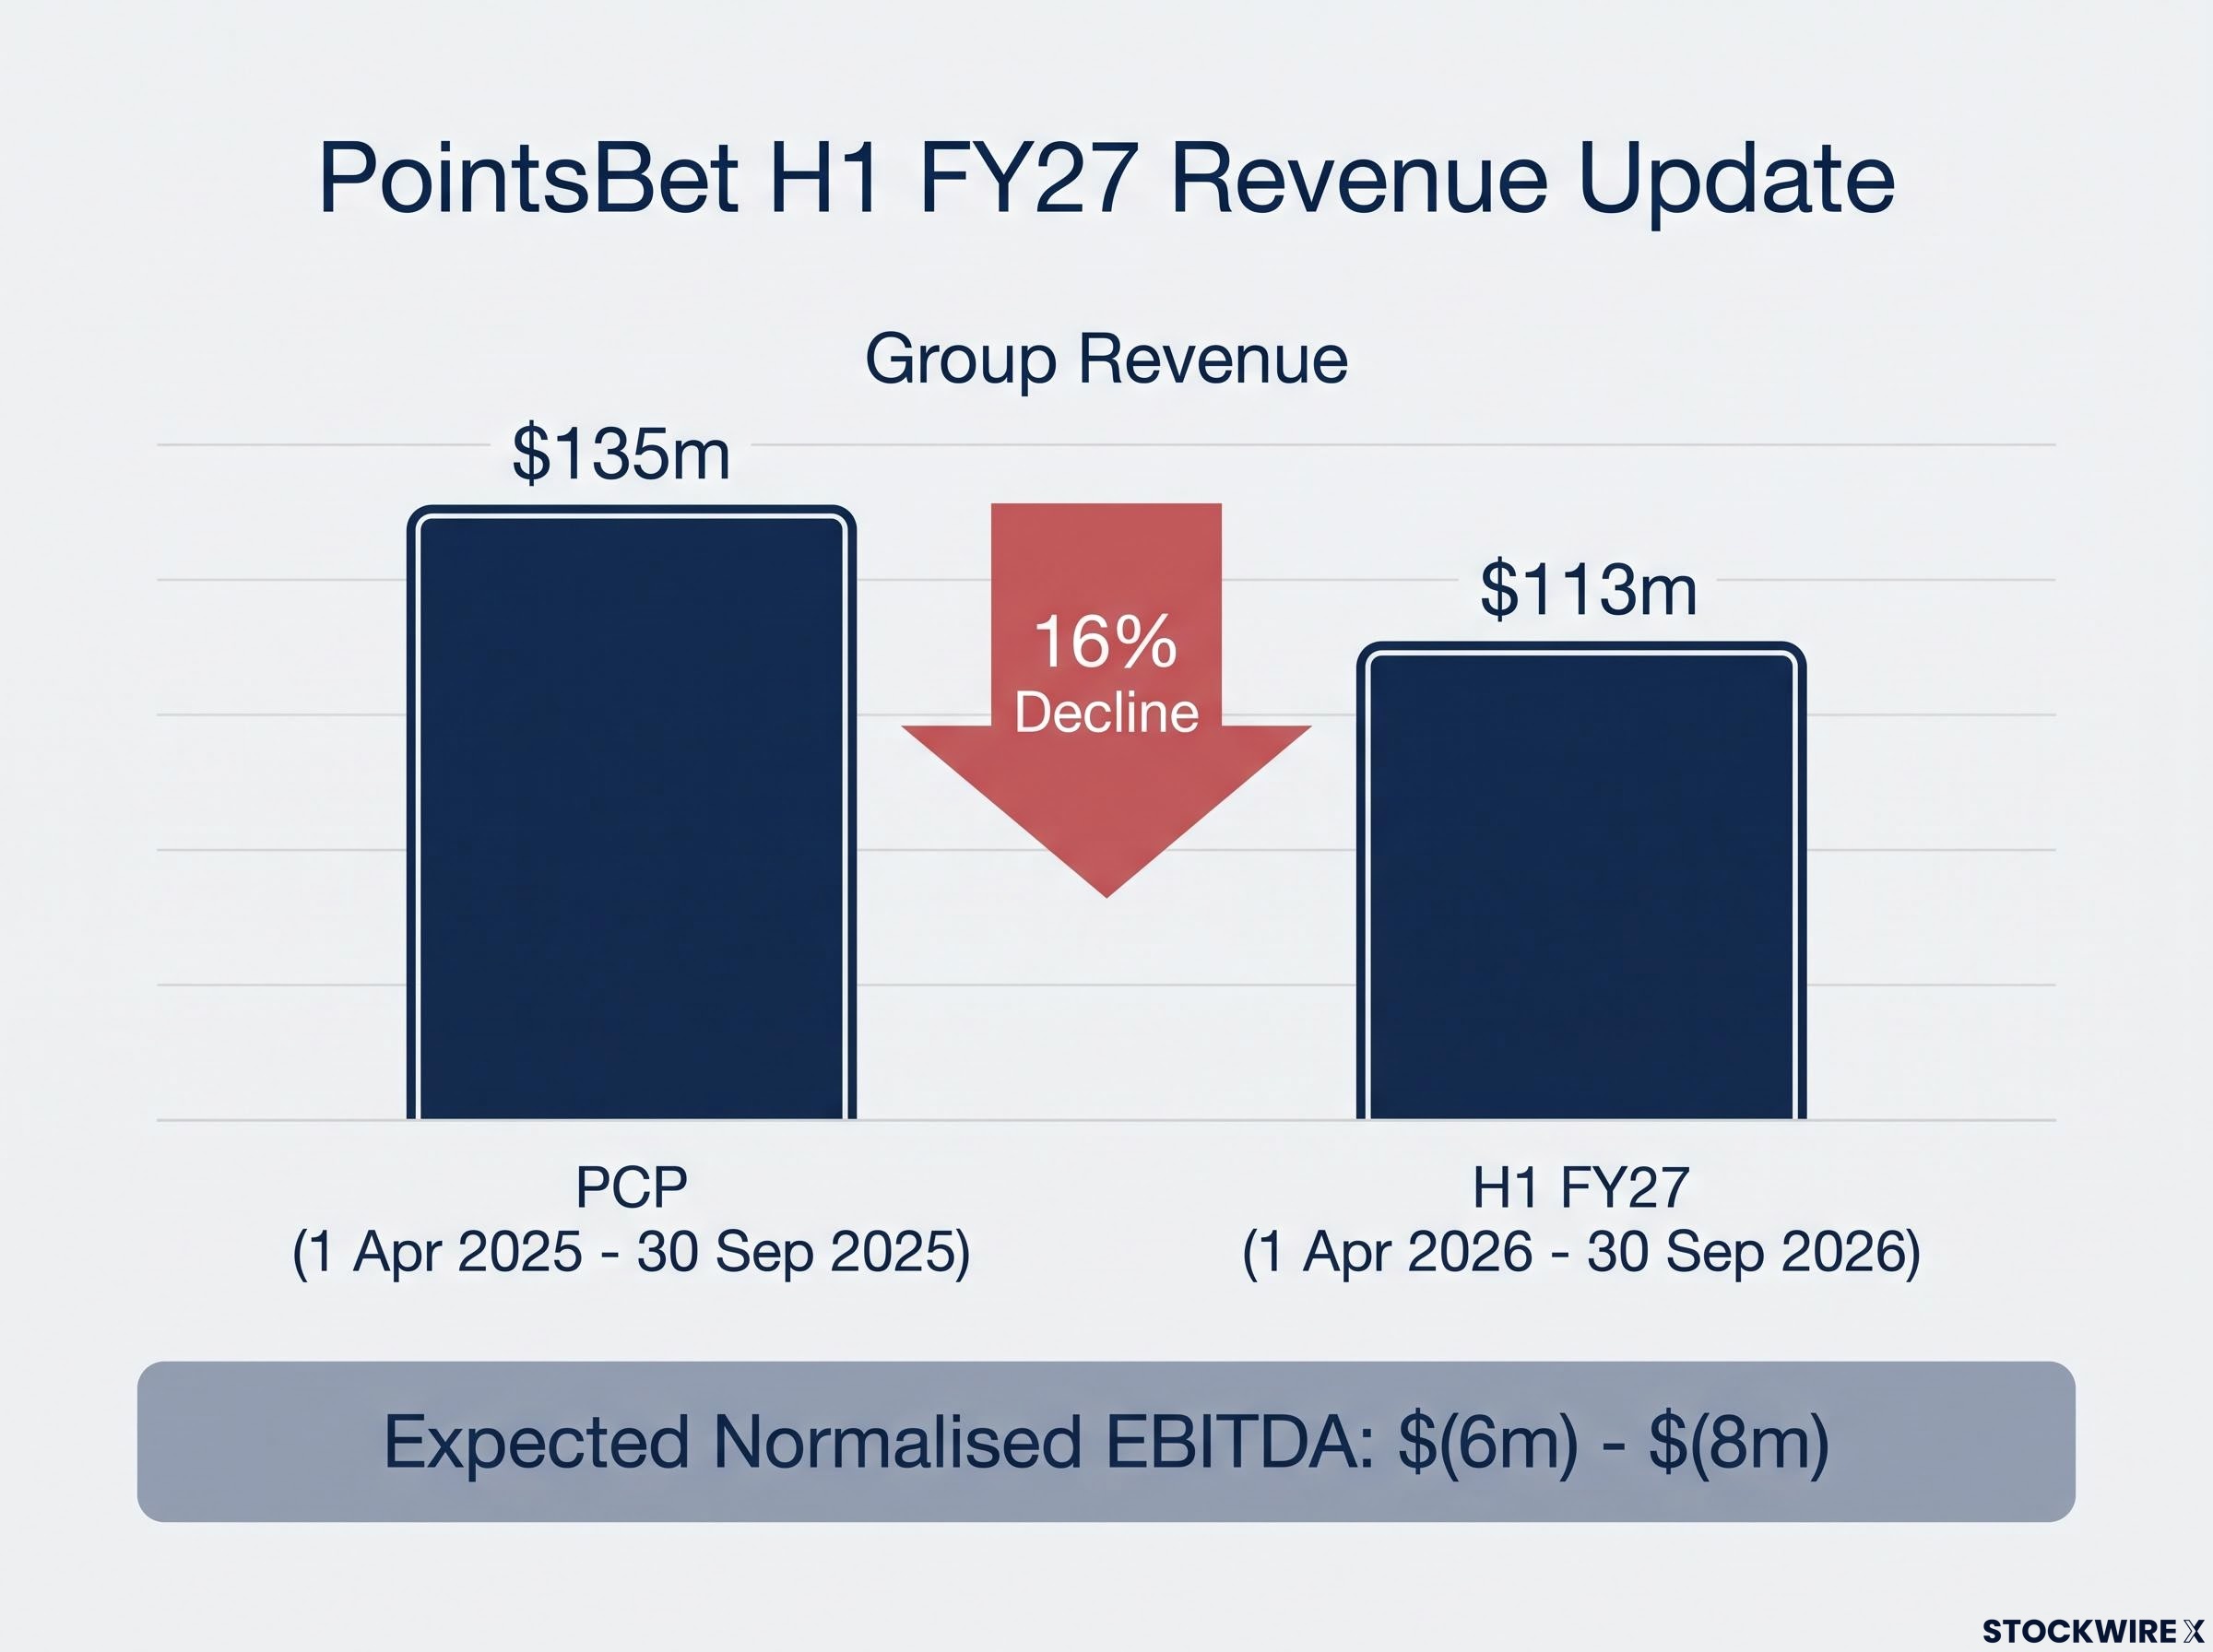
PointsBet Holdings Limited (ASX:PBH) expects H1 FY27 group revenue of approximately $113m for the period 1 April 2026 to 30 September 2026, according to a trading update dated 13 October 2026. The H1 FY27 trading update also guides to Normalised EBITDA of $(6m) – $(8m).
The revenue figure compares with approximately $135m in the prior corresponding period (PCP) of 1 April 2025 to 30 September 2025, a decline of approximately 16%. PointsBet revenue declined because of the Australian business, according to the company.
Full H1 FY27 results are due on 30 October 2026, which is the next catalyst for the market. The announcement does not provide separate figures for the Canadian operations.
| Metric | H1 FY27 | PCP | Change |
|---|---|---|---|
| Group revenue | Approximately $113m | Approximately $135m | Decline of approximately 16% |
| Normalised EBITDA | $(6m) – $(8m) (expected) | Not disclosed | Not disclosed |
When big ASX news breaks, our subscribers know first
Two themes behind the Australian revenue decline
PointsBet attributed the decline to a continuation of two key themes identified at its FY26 AGM. One relates to compliance, the other to a deliberate shift in customer focus.
Compliance standards strengthened
The company pointed to a sustained trend of double-digit turnover and revenue declines versus PCP throughout H1 from its “highest value client cohort”. PointsBet attributed this trend to proactive compliance actions as it continued strengthening its compliance standards.
Management described these as important decisions in the context of an increasingly complex regulatory environment in Australia. For investors, the update suggests the company has prioritised regulatory standards over revenue from that client cohort in the half.
PointsBet had already flagged regulatory and product costs consuming 48.7% of Australian Net Win in its H1 FY26 results, the first reported under MIXI ownership.
Accelerating mass market sports actives
The second theme is a deliberate choice to accelerate growth in mass market sports actives, which PointsBet said can lead to short-term volatility in Net Win margins. The company outlined the following effects for the half:
- Consistent gains in mass market sports Actives, Turnover and structural Net Win margin versus PCP.
- These gains were eroded by negative variance in actual Net Win margin throughout the half.
- Adverse results for key sports in August and September, primarily AFL.
The announcement does not quantify the gains in actives, turnover or structural margin.
PointsBet
“We believe these have been important decisions to make in the context of an increasingly complex regulatory environment in Australia.”
Net Win margin explained for investors
Net Win margin is the share of customer turnover that a bookmaker retains after paying out winning bets. It varies from period to period because it depends partly on sporting results.
The announcement distinguishes between two measures:
- Structural Net Win margin: the expected underlying margin, which PointsBet said improved versus PCP.
- Actual Net Win margin: the margin that actually occurred, which was negative versus expectations across the half, with adverse AFL results cited.
Short-term margin swings can obscure underlying customer growth. Investors may therefore watch actives and turnover alongside revenue.
What to watch at the 30 October results
The full H1 FY27 results on 30 October 2026 are expected to give the market more detail. Questions investors may want answered include:
- How did the Australian and Canadian segments each perform?
- What are the trends in mass market Actives and Turnover?
- What is the cash position, and what is the path from the guided Normalised EBITDA range of $(6m) – $(8m)?
The announcement does not disclose cash or outlook data. Investor enquiries can be directed to Alister Lui, Group Chief Financial Officer.
Get Consumer News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX news within minutes of release, complete with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to get real-time alerts the moment the next consumer sector announcement breaks.