
Q1 FY27 highlights: double-digit growth, $300 million revenue target on track
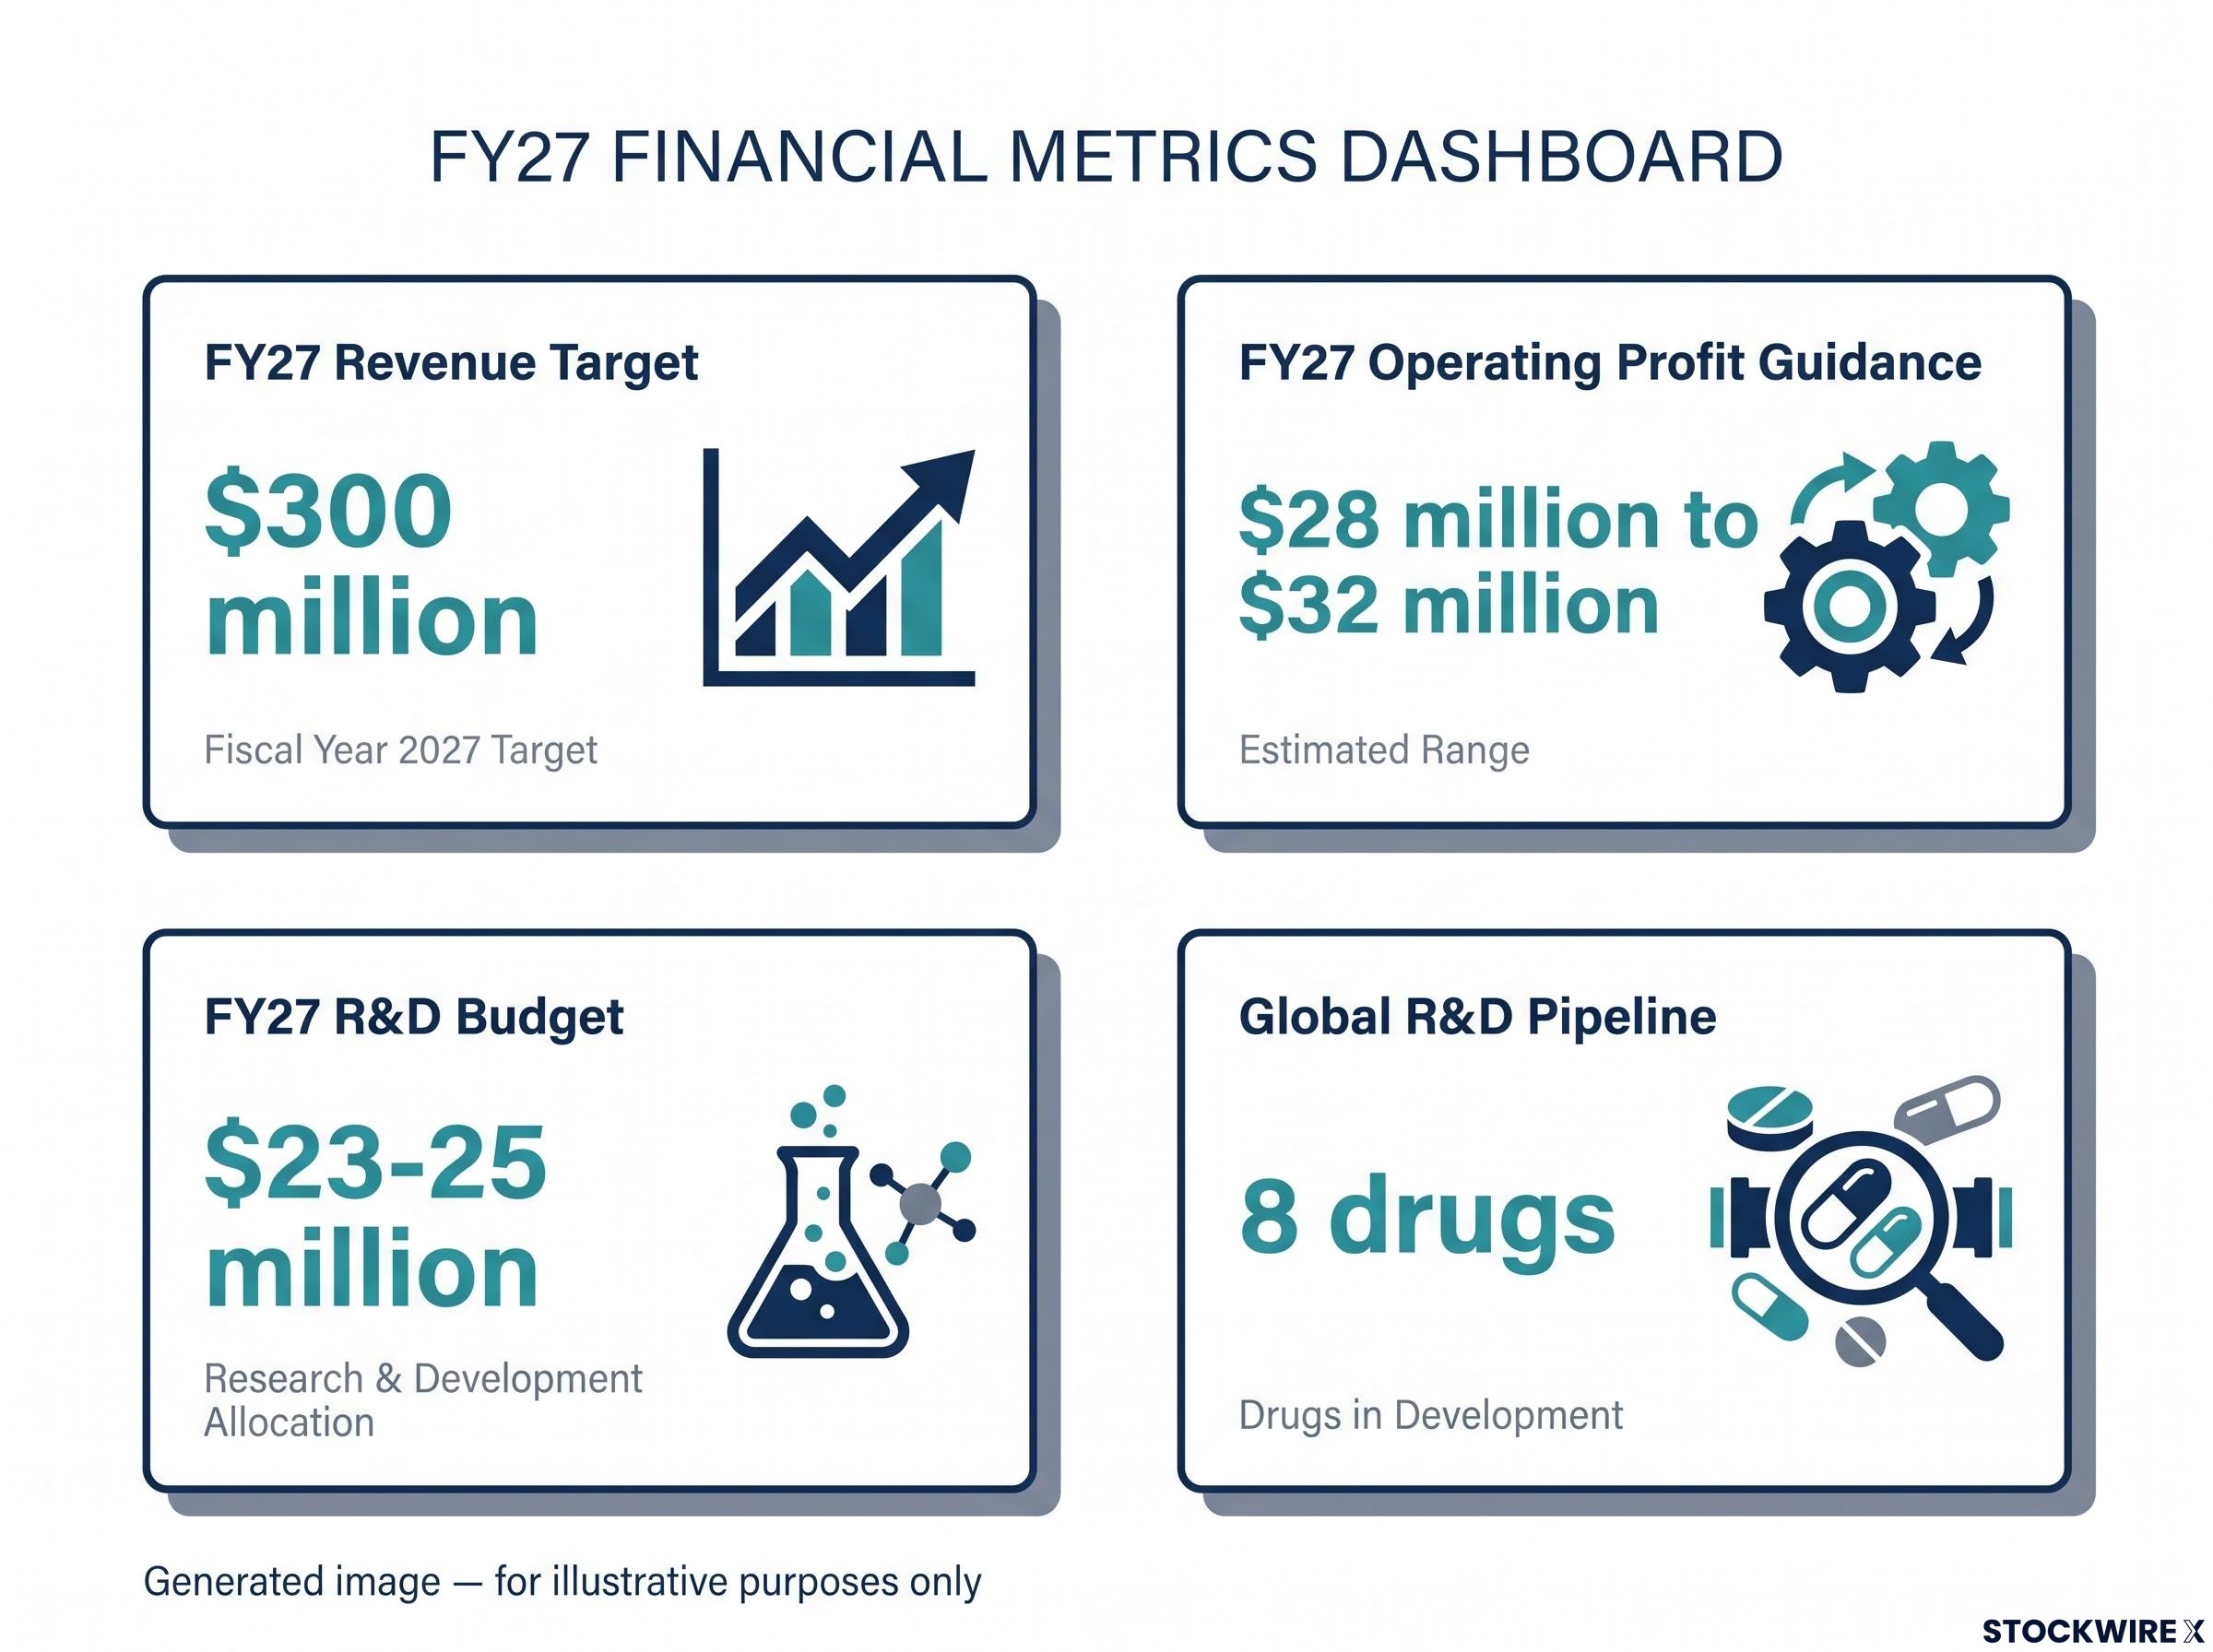
In its September quarter investor update (Q1 FY27, released 6 October 2026), AFT Pharmaceuticals (ASX: AFP) reported sustained double-digit revenue growth across all divisions in 1H FY27. The company said it remains on track to deliver its FY27 revenue target of $300 million.
FY27 operating profit guidance was affirmed at $28 million to $32 million. The update did not disclose actual revenue figures or growth percentages.
Dr Hartley Atkinson, Managing Director
“We are pleased with our half year sales progress… We are looking to the remainder of the financial year with confidence.”
The affirmed guidance range gives investors a stated earnings reference point for the remainder of the financial year.
Key highlights from the update:
- Maxigesic IV out-licensed in Japan and the Philippines
- Third US FDA approval for a patented product, with tentative approval of Scomara
- First study sites activated for Feramyl IV, a novel iron injectable product
- Successful launch of Maxigesic (Combogesic) Rapid in the US with Mark Cuban’s Cost Plus Drugs Company
When big ASX news breaks, our subscribers know first
Pipeline progress: Scomara, Maxigesic IV and Feramyl IV
Scomara tentative FDA approval
AFT achieved its third US FDA approval for a patented product with tentative approval of Scomara, a treatment of Facial Angiofibromas in Tuberous Sclerosis (FA in TSC). An existing product in the US market maintains a market exclusivity provision under US orphan drug regulations until early 2029, which will delay the launch.
AFT pointed to two competitive advantages over that product: ambient temperature storage and once-a-day application. The company also cited little regulatory or R&D risk.
Maxigesic IV and Feramyl IV
Maxigesic IV was out-licensed to Japan’s MIKASASEIYAKU CO., and to Indonesia’s Kalbe Farma for the Philippines. AFT described Japan as the world’s third largest pharma market, offering significant potential upside following the generation of additional Japanese patient clinical data.
AFT also completed a 240-patient clinical study demonstrating therapeutic equivalence for an OTC product, which will enable regulatory filings in the key Australian market. The company said the product has significant sales potential in a A$50M plus segment.
The large 1,366-patient Feramyl IV study is starting in the first trial centres. It is planned to include sites in New Zealand, Armenia, India, China, Korea, Japan, the US and Europe.
AFT said the novel iron product offers entry into a market worth as much as US$7.4 billion by 2033, with the first launch expected around the end of the 2029 calendar year.
| Product | Milestone | Market opportunity | Expected timing |
|---|---|---|---|
| Scomara | Tentative US FDA approval (FA in TSC) | Not disclosed | Launch delayed by orphan drug exclusivity of an existing product until early 2029 |
| Maxigesic IV | Out-licensed in Japan and the Philippines | Not disclosed | Not disclosed |
| OTC product (Australia) | 240-patient therapeutic equivalence study completed | A$50M plus segment | Not disclosed |
| Feramyl IV | 1,366-patient study starting at first trial centres | As much as US$7.4 billion by 2033 | First launch expected around end of 2029 calendar year |
Together, these programmes extend the pipeline beyond the FY27 targets.
For readers wanting to follow the Feramyl IV programme further, our full explainer on the injectable iron Phase III clearance covers the FDA IND decision, the global study design and the role of development partner Hyloris Pharmaceuticals.
Fridge-free medicines: what StablePharma’s Lancet validation means
Fridge-free medicines are products designed to be stored without refrigeration. Many vaccines and medicines normally need a cold chain, meaning they must be kept cold from manufacture to patient. AFT said its partner’s technology promises to simplify vaccine and medicine distribution, reduce wastage, save costs and improve access.
StablePharma, AFT’s UK/Spanish R&D partner, had positive results from its own first-in-human study published in The Lancet. The Phase I study found the freeze-dried tetanus-diphtheria booster SPVX02 produced immune responses and a safety profile broadly comparable with conventional refrigerated vaccines.
The results of this small initial trial were also highlighted in the British Medical Journal.
AFT said its partnership utilises similar technology for non-refrigerated medicines and offers access to a market worth as much as US$6 billion.
The company also signed a letter of intent for the distribution of SPVX02 in the UK, Canada, Australia and New Zealand, with an option to extend to Singapore and Hong Kong. A letter of intent is not a binding agreement.
AFT is presently advancing the first two fridge-free medicine formulations under an existing R&D development agreement. It expects the first product under the agreement to come to market in 2029.
US launch, R&D spend and outlook
AFT described the US launch and partnership with Mark Cuban’s Cost Plus Drug Company as the most notable launch progress. Management said the US is a complex market, entry is relatively late in its global expansion, and a positive result could significantly lift sales, with progress to be clearer by the end of FY27.
Launches continue in Singapore, Hong Kong, South Africa, Canada and the UK. In Canada, AFT employed a Key Account Manager to handle several OTC launches. Additional launches across affiliates outside the core Australian and New Zealand markets are expected to lift growth, but demand both focus and promotional investment.
The FY27 R&D budget (capitalised and expensed) is expected to be between $23-25 million, and the global R&D pipeline comprises eight drugs.
AFT’s self-funded R&D model is paid for from operating earnings rather than new capital, with R&D spend forecast to rise from $18 million in FY26 to $27 million in FY28 as the pipeline matures.
Issuer-sponsored research
AFT recently engaged Pitt St, an Australian based research organisation providing issuer-sponsored equity research on ASX-listed life sciences companies since 2016. Its evaluation of the existing business and three of the eight key R&D projects reached a valuation of between NZ$12.63 and NZ$16.42 (base to bull case).
This is issuer-sponsored research, not an AFT forecast.
Outlook
Dr Atkinson said the outlook for FY27 remained positive across all business regions. He also said AFT continues to maintain higher inventory levels to help manage uncertainties from the geopolitical situation and ensure certainty of supply to customers.
Dr Hartley Atkinson, Managing Director
“We are seeing continued growth across our operations and ongoing strong demand.”
Management said significant resource and focus continues to be directed towards the R&D pipeline, alongside new product in-licensing and market development, to support longer term growth.
Don’t Miss the Next Healthcare Breakout
Get FREE breaking ASX healthcare news delivered to your inbox within minutes of release, complete with in-depth analysis and the full announcement. Join 20,000+ investors already staying ahead of the market. Click the “Free Alerts” button at Big News Blast to receive alerts the moment market-moving news breaks.