The Reserve Bank of Australia just lifted its cash rate for the fourth time this year, pushing it to 4.60 percent, the highest level in roughly 15 years. The Australian dollar fell anyway.
Not because the hike surprised anyone. Not because markets missed the decision. The currency slid because something larger was pulling in the opposite direction, and it had nothing to do with Australia.
On 30 September 2026, with AUD/USD trading near 0.6910, US 10-year Treasury yields were pushing toward 5.34 percent, a level not seen since 2007. American jobs numbers were coming in strong, GDP had been revised upward, and manufacturing prices were climbing. The Federal Reserve was still signalling it might tighten further. Against that backdrop, a single RBA hike simply did not have the weight to move the pair.
This was not a failure of Australian policy. It was a demonstration of how currency markets are actually structured, where AUD USD interest rates are priced against each other rather than in isolation.
Here is what you will be able to recognise after reading: why two central banks delivering identical-sounding rate hikes can produce opposite currency outcomes, depending on where each sits in the global monetary hierarchy, and which signals tell you which force is winning.
The paradox in plain terms: why did a rate hike send the currency down?
Start with what you have probably been taught. Higher interest rates attract foreign capital, because investors chase better returns on their money. That capital inflow bids up demand for the domestic currency, so the currency rises. A rate hike should, by this logic, strengthen the currency that just got the hike.
That is the standard expectation. It is also, in this case, exactly what did not happen.
What actually happened
The RBA moved its cash rate from 4.35 percent to 4.60 percent on 30 September 2026, the fourth 25 basis point increase of the year. Rather than recovering, AUD/USD kept sliding, reaching roughly 0.6910 on the day, a fall of around 0.48 percent, with RBA exchange rate data recording 0.6949 as at 4:00 pm on 1 October 2026. Either reading sits at a multi-month low.
The RBA’s September 2026 rate decision confirmed the Board’s assessment that inflation remained elevated and that further tightening could be warranted, framing the guidance in conditional terms that markets interpreted as a signal the tightening cycle was approaching its end.
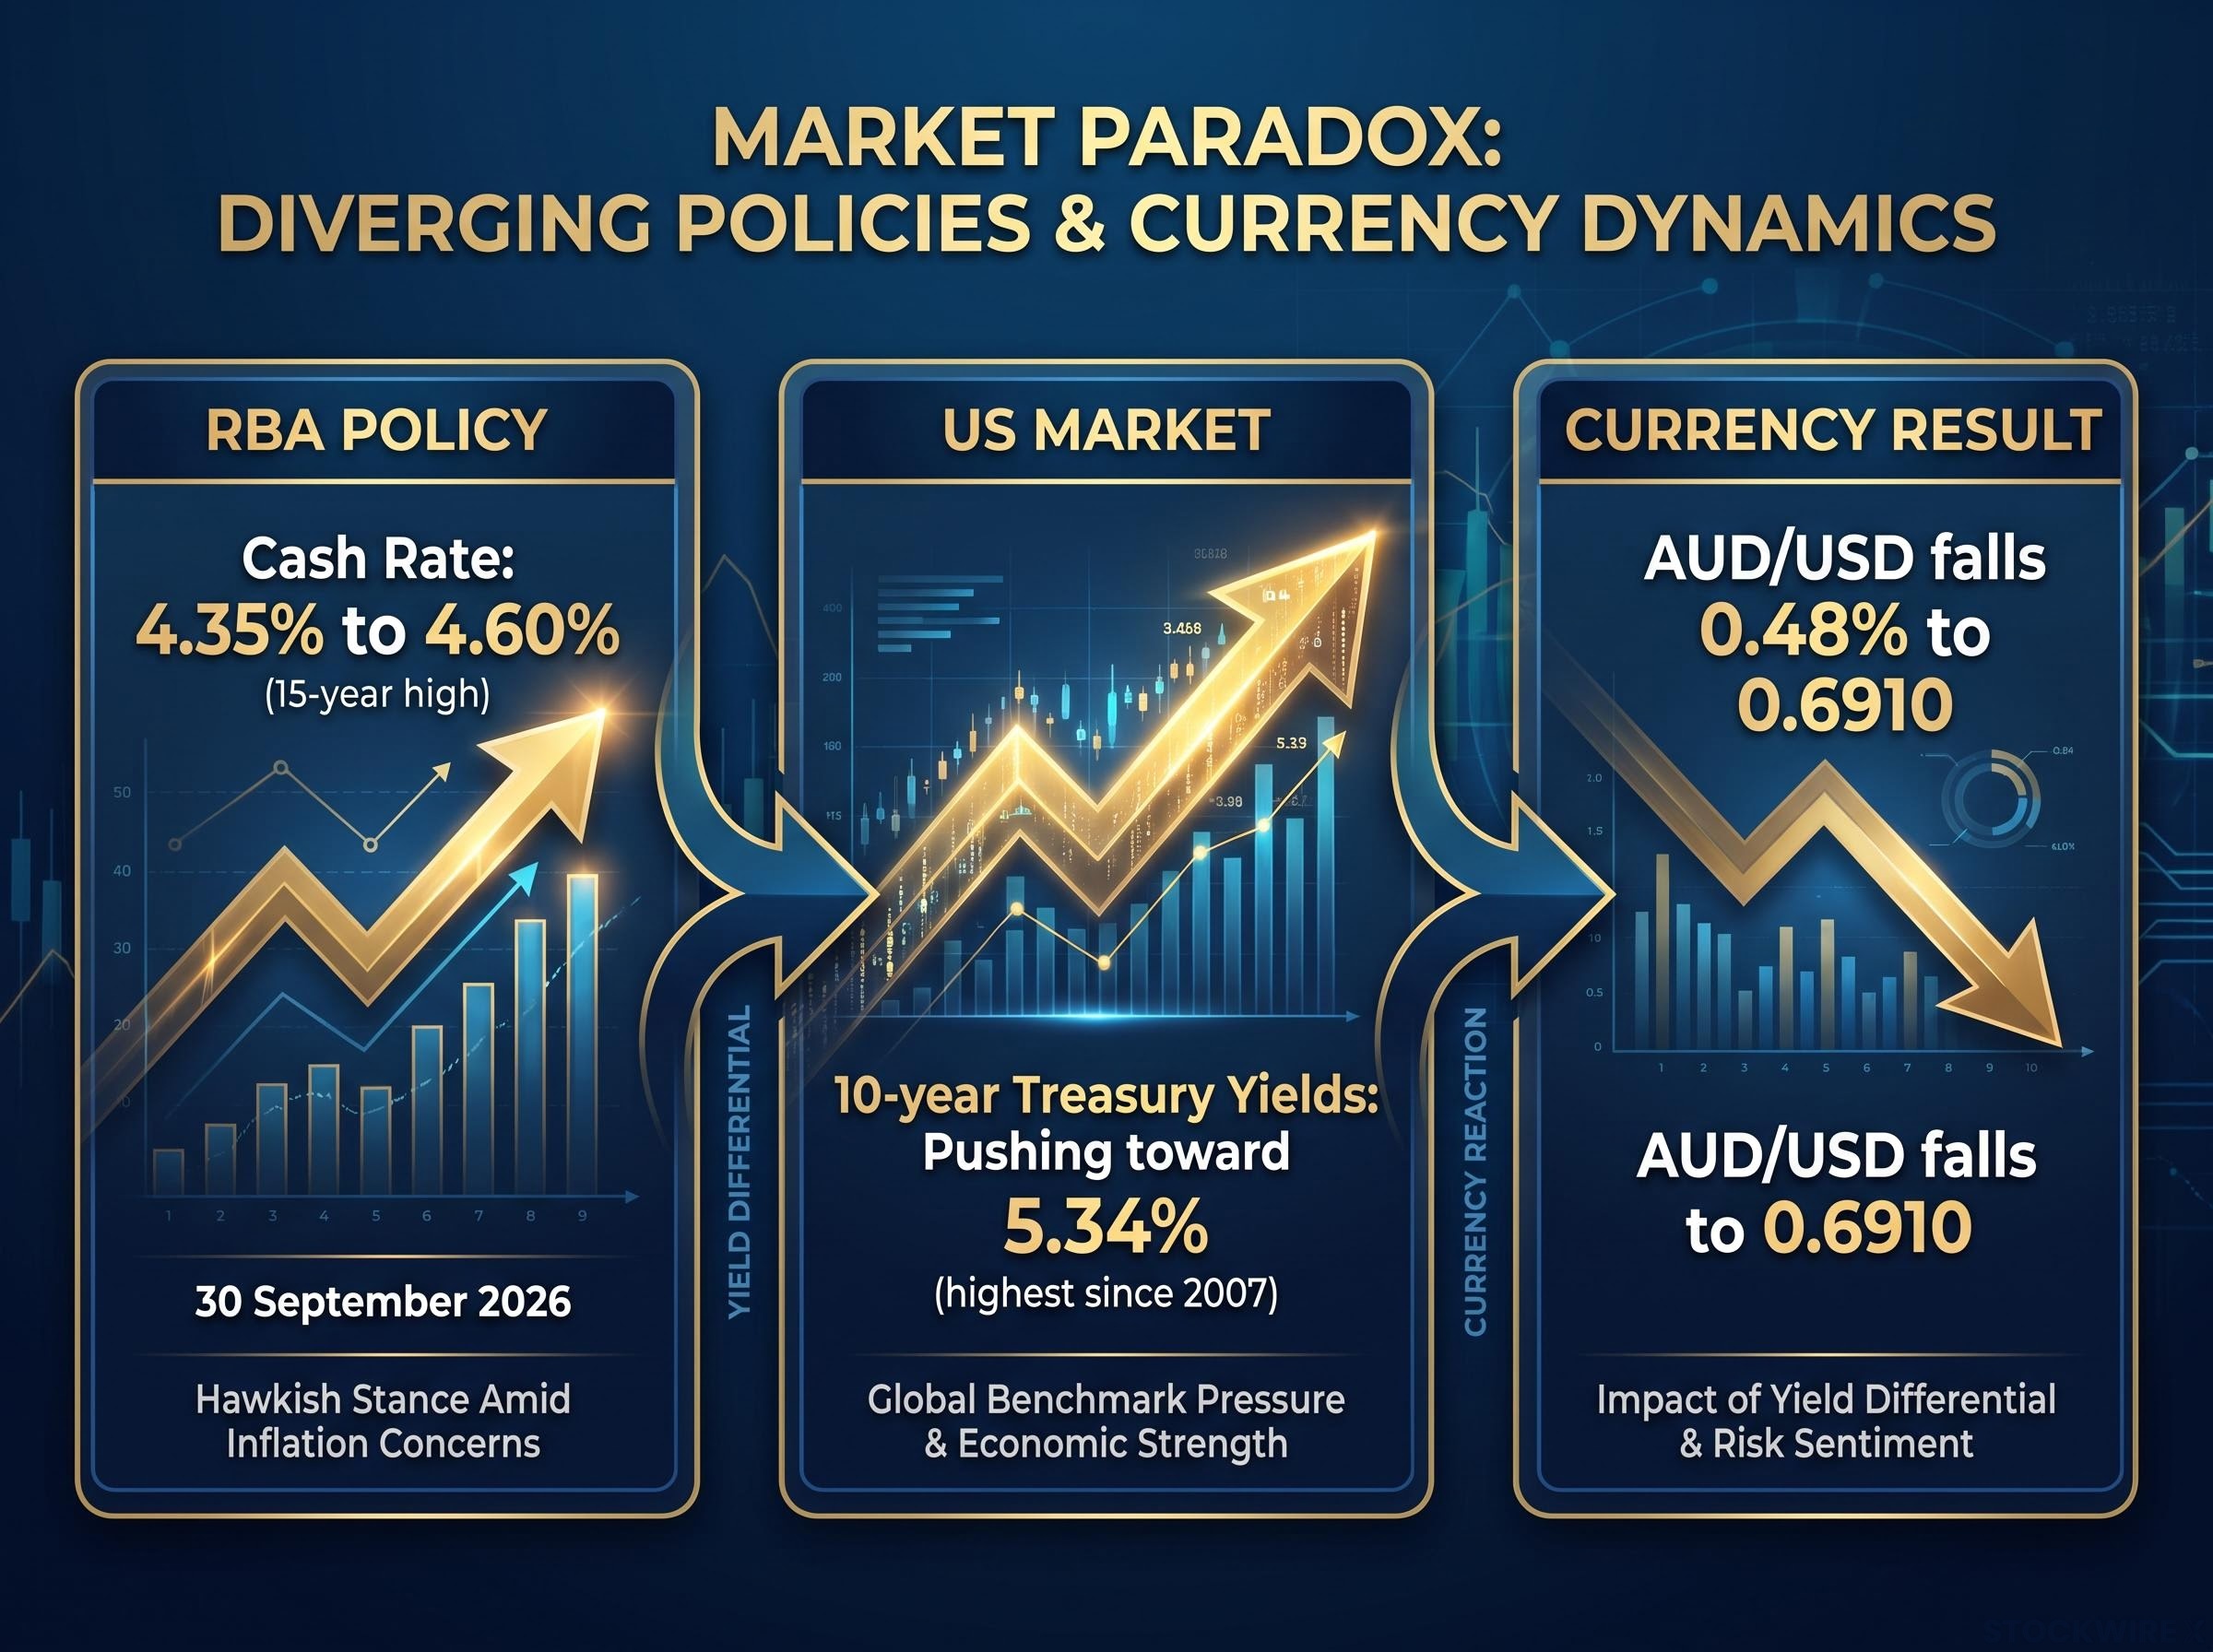
The RBA raised rates to a 15-year high, and the Australian dollar fell anyway.
So what gives? The resolution is not an excuse for the RBA. It is a structural fact about how these markets price information.
Currency markets do not respond to the absolute level of a country’s interest rate. They respond to the direction and size of the policy change relative to other central banks, and to where rates are expected to go from here. A rate at 4.60 percent means nothing on its own. What matters is 4.60 percent compared to what the Fed is doing, and whether the gap between the two is widening or shrinking.
This is the correction most financial news gets wrong. Headlines treat a rate hike as automatically good for a currency. The simultaneous occurrence of an RBA hike and an AUD decline is not an anomaly to explain away. It is the market telling you that the relative and expected path of rates matters more than today’s decision. Once you internalise that, you will read every future central bank announcement differently.
When big ASX news breaks, our subscribers know first
What actually moves currencies: the mechanics of relative monetary policy
Build the logic one piece at a time, because the outcome becomes obvious once the pieces are in place.
The operative variable is the yield differential: the gap between two countries’ interest rates. Capital flows toward the higher yield, so the currency offering the better relative return tends to strengthen. The key word is relative. Markets do not price today’s gap in a vacuum. They price the expected future gap, because money positions itself for where rates are heading, not where they are.
Yield differential mechanics are the upstream variable connecting every central bank decision to currency, bond, and equity outcomes simultaneously; the gap between what was expected and what was delivered, not the rate level itself, drives the sharpest repricing across asset classes.
Now apply that to the AUD/USD case, and the paradox dissolves. The RBA hiked, which on paper widened Australia’s yield advantage. But two things happened at the same time that compressed it instead.
First, markets repriced future RBA hikes lower. Investing.com described this as “fading RBA hike bets,” meaning traders decided the RBA was closer to the end of its tightening than previously assumed. Second, US Treasury yields kept rising on the back of strong American data. The differential narrowed in favour of the dollar even as the nominal Australian rate went up.
And the US data was genuinely strong, across every category that matters for rate expectations.
| US indicator | Reported value | Consensus | Market implication |
|---|---|---|---|
| Initial Jobless Claims (week ended 26 Sep) | 197,000 | 201,000 | Labour market tighter than expected |
| ADP private payrolls (September) | 90,000 | 70,000 | Hiring accelerating from 36,000 in August |
| Q2 GDP (revised) | 2.2% annualised | 1.5% prior estimate | Growth stronger than first measured |
| ISM Manufacturing PMI (September) | 54.5 | 55.0 | Still expanding; Prices Paid jumped to 77.9 from 71.1 |
There is a second, more technical signal layered on top: a bear flattening of the US yield curve, where shorter-dated yields rise faster than longer-dated ones. StoneX flagged this as a sign of Fed repricing rather than a simple term-premium move. In plain terms, it tells FX markets the Fed is expected to stay restrictive for longer, not just that investors want more compensation for holding long bonds.
Three forces were therefore compressing the AUD/USD differential at once:
- Rising US Treasury yields, pushing the dollar’s relative return higher
- Fading RBA hike bets, lowering Australia’s expected future yield
- A bear-flattening US curve, signalling a prolonged Fed plateau
When American data prints this strongly across labour, growth, and manufacturing prices simultaneously, the market does not just price one more Fed hike. It prices a longer restrictive plateau, and that repricing flows straight into the dollar. At time of reporting, the CME FedWatch tool put the probability of a Fed hike at the 27-28 October FOMC meeting at roughly 36 percent.
RBA Governor Michele Bullock said the Board was prepared to lift rates further “if necessary,” which markets read as conditional hawkishness rather than a firm commitment. That conditionality is precisely why a single hike could not shift the trajectory. The lesson for you is to stop reading the headline rate and start asking whether the hike actually improved the currency’s relative yield position. Here, it did not.
The currency hierarchy: why the US dollar rewrites the rules for everyone else
Zoom out, because this AUD/USD episode is one instance of a durable pattern, not a one-off quirk.
Currencies sit in a hierarchy, and the US dollar occupies the apex. Three structural features put it there:
- Reserve asset status. US Treasuries are the global reserve asset that central banks and institutions hold as their baseline safe store of value.
- Invoicing and funding dominance. A vast share of global trade is priced in dollars, and much of the world’s borrowing is denominated in dollars.
- Global capital flow anchor. US financial conditions set the baseline cost of capital for everyone, so when they tighten, the effect ripples outward.
Because of this, US monetary policy and risk appetite drive cross-border capital flows in ways that routinely overwhelm smaller central banks. Economist Helene Rey documented exactly this in her 2013 Jackson Hole research on what she termed the global financial cycle. Her framework found that during US-led tightening phases, open economies tend to see their currencies weaken despite domestic rate increases. The current AUD episode is the kind of dynamic that framework anticipates.
The NBER research on the global financial cycle, published by Helene Rey, demonstrates that US monetary policy transmits through cross-border capital flows in ways that routinely override domestic rate decisions in smaller open economies, regardless of their exchange rate regime.
The selling pressure on AUD/USD reflects a broadly strengthened US Dollar, itself driven by the sustained climb in US Treasury yields to multi-year highs.
History offers a direct precedent. During the 2015-2018 Fed tightening cycle, several emerging-market and smaller advanced-economy central banks raised their own rates and still watched their currencies fall as the dollar strengthened and global investors demanded higher compensation for risk. The pattern is consistent enough that the IMF and BIS have written extensively about these spillovers. A single hike from a smaller central bank gets drowned out by US yield moves.
The ECB rate hike episode of September 2026 produced an almost identical paradox: the deposit rate rose to 2.50% and the euro slipped against the dollar anyway, confirming that the relative Fed-versus-other-central-bank dynamic is not a quirk of Australian policy but a recurring structural pattern.
Why AUD is especially vulnerable during US rate shocks
The Australian dollar is a pro-cyclical, high-beta, commodity-linked currency. It rises when global growth and risk appetite are strong, and it falls hard when they are not. That makes it doubly exposed during a US rate shock.
When US yields spike and risk appetite drops at the same time, two forces hit the Australian dollar together. Safe-haven flows rush toward the US dollar, and investors unwind carry trades that had used the Australian dollar as a higher-yielding bet. Both work against AUD simultaneously.
This is not a defect in RBA policy. It is a structural characteristic of how the Australian dollar functions inside global portfolios. For you, the practical takeaway is blunt: during a US yield spike, your domestic central bank’s decision is not the primary variable. The direction and volatility of US Treasuries will dominate the exchange rate until that shock stabilises. When you want to know where AUD/USD is heading, look at the Fed and the Treasury market first.
What would it take for an RBA hike to actually lift the Australian dollar?
Here is the forward-looking part, because none of this means the Australian dollar is stuck. Recovery does not require the US dollar to collapse. It requires a change in the relative conditions currently favouring it, and there are three identifiable pathways.
- US yield stabilisation. If US Treasury yields stabilise, even at high levels, and Treasury volatility falls, the rates-shock premium supporting the dollar can fade. With fewer Fed surprises, carry and risk appetite become the dominant drivers again, which tends to favour higher-beta currencies like AUD.
- More decisively hawkish Australian data. If Australian inflation or growth surprises to the upside, markets would price more RBA hikes rather than fading them. That would widen the expected rate differential in AUD’s favour, even against a broadly firm dollar.
- Improved global risk sentiment and commodity demand. Strength in demand for Australia’s key exports supports the currency’s pro-cyclical role, offsetting some of the drag from US rates.
Each pathway maps to something specific you can watch.
The BoJ-driven dollar selloff of early September 2026, when a Bank of Japan rate check forced carry-trade unwinds and dragged DXY down 0.58% in a single session, shows how quickly the two forces currently weighing on AUD can reverse when US yield expectations shift or a third-party central bank disrupts the dollar carry trade.
| Recovery condition | What to watch | Why it matters for AUD/USD |
|---|---|---|
| US yield stabilisation | US Treasury yield volatility and the 10-year level | A calmer rates picture removes the shock premium propping up the dollar |
| Hawkish Australian data | Australian CPI and labour market releases | Upside surprises shift RBA pricing higher, widening the differential for AUD |
| Risk and commodity strength | Commodity prices and China demand data | Terms-of-trade support feeds AUD’s pro-cyclical role |
The data gives a mixed read right now. Australia’s trade surplus narrowed to A$495 million in the most recently reported month, down from A$1.351 billion the prior month, with imports up 5.8 percent and exports up 3.7 percent. That reflects a different reference month from the ABS July 2026 reading of A$1.923 billion, so treat them as separate data points rather than a direct comparison. Either way, the trend is a narrowing surplus, which does not yet argue for commodity-driven support.
Governor Bullock’s “if necessary” guidance keeps the domestic tightening path open but data-dependent, so an upside inflation surprise could shift RBA pricing back up. And inflationary pressure is not uniquely Australian. The US ISM Prices Paid Index jumped to 77.9 in September from 71.1 in August, a reminder that the global backdrop driving this episode can itself shift.
The point for you is that the current weakness is conditional, not structural decline. The three recovery conditions are clearly identifiable. They are simply not present yet.
Reading the next rate hike with the right framework
Pull it all together, because the real value here is a change in how you read central bank decisions from now on.
The core lesson is that a rate hike is never a currency signal on its own. It is one input into a relative calculation that always includes the direction and expected path of US monetary policy and Treasury yields. The RBA sitting at 4.60 percent while US 10-year yields hover between 5.24 and 5.34 percent explains why AUD/USD is at multi-month lows despite the hike. Fading RBA hike bets compressed the differential even as the move landed.
Seen correctly, raising rates to a 15-year high while managing conditional guidance is appropriate domestic policy. The FX market simply is not grading the RBA in isolation. It is assessing Australia’s position relative to the United States at a moment when US financial conditions are the dominant global variable, exactly the mechanism Helene Rey’s global financial cycle framework describes in action.
So when the next RBA or Fed announcement lands, run it through two questions:
- Where is the Fed in its cycle, and which way are US Treasury yields trending?
- Is this domestic hike shifting the expected future rate differential, or merely delivering what markets had already priced in?
Ask those two questions and you will read a currency’s response to a central bank decision as information rather than noise. You will stop asking “did rates go up?” and start asking the question that actually determines the outcome.
For investors wanting to see how geopolitical shocks layer on top of rate-differential pressures, our deep-dive into AUD/USD external risk drivers examines how Hormuz escalation and US dollar safe-haven demand created an asymmetric downside skew that domestic RBA policy could not offset.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking scenarios are speculative and subject to change based on market developments.