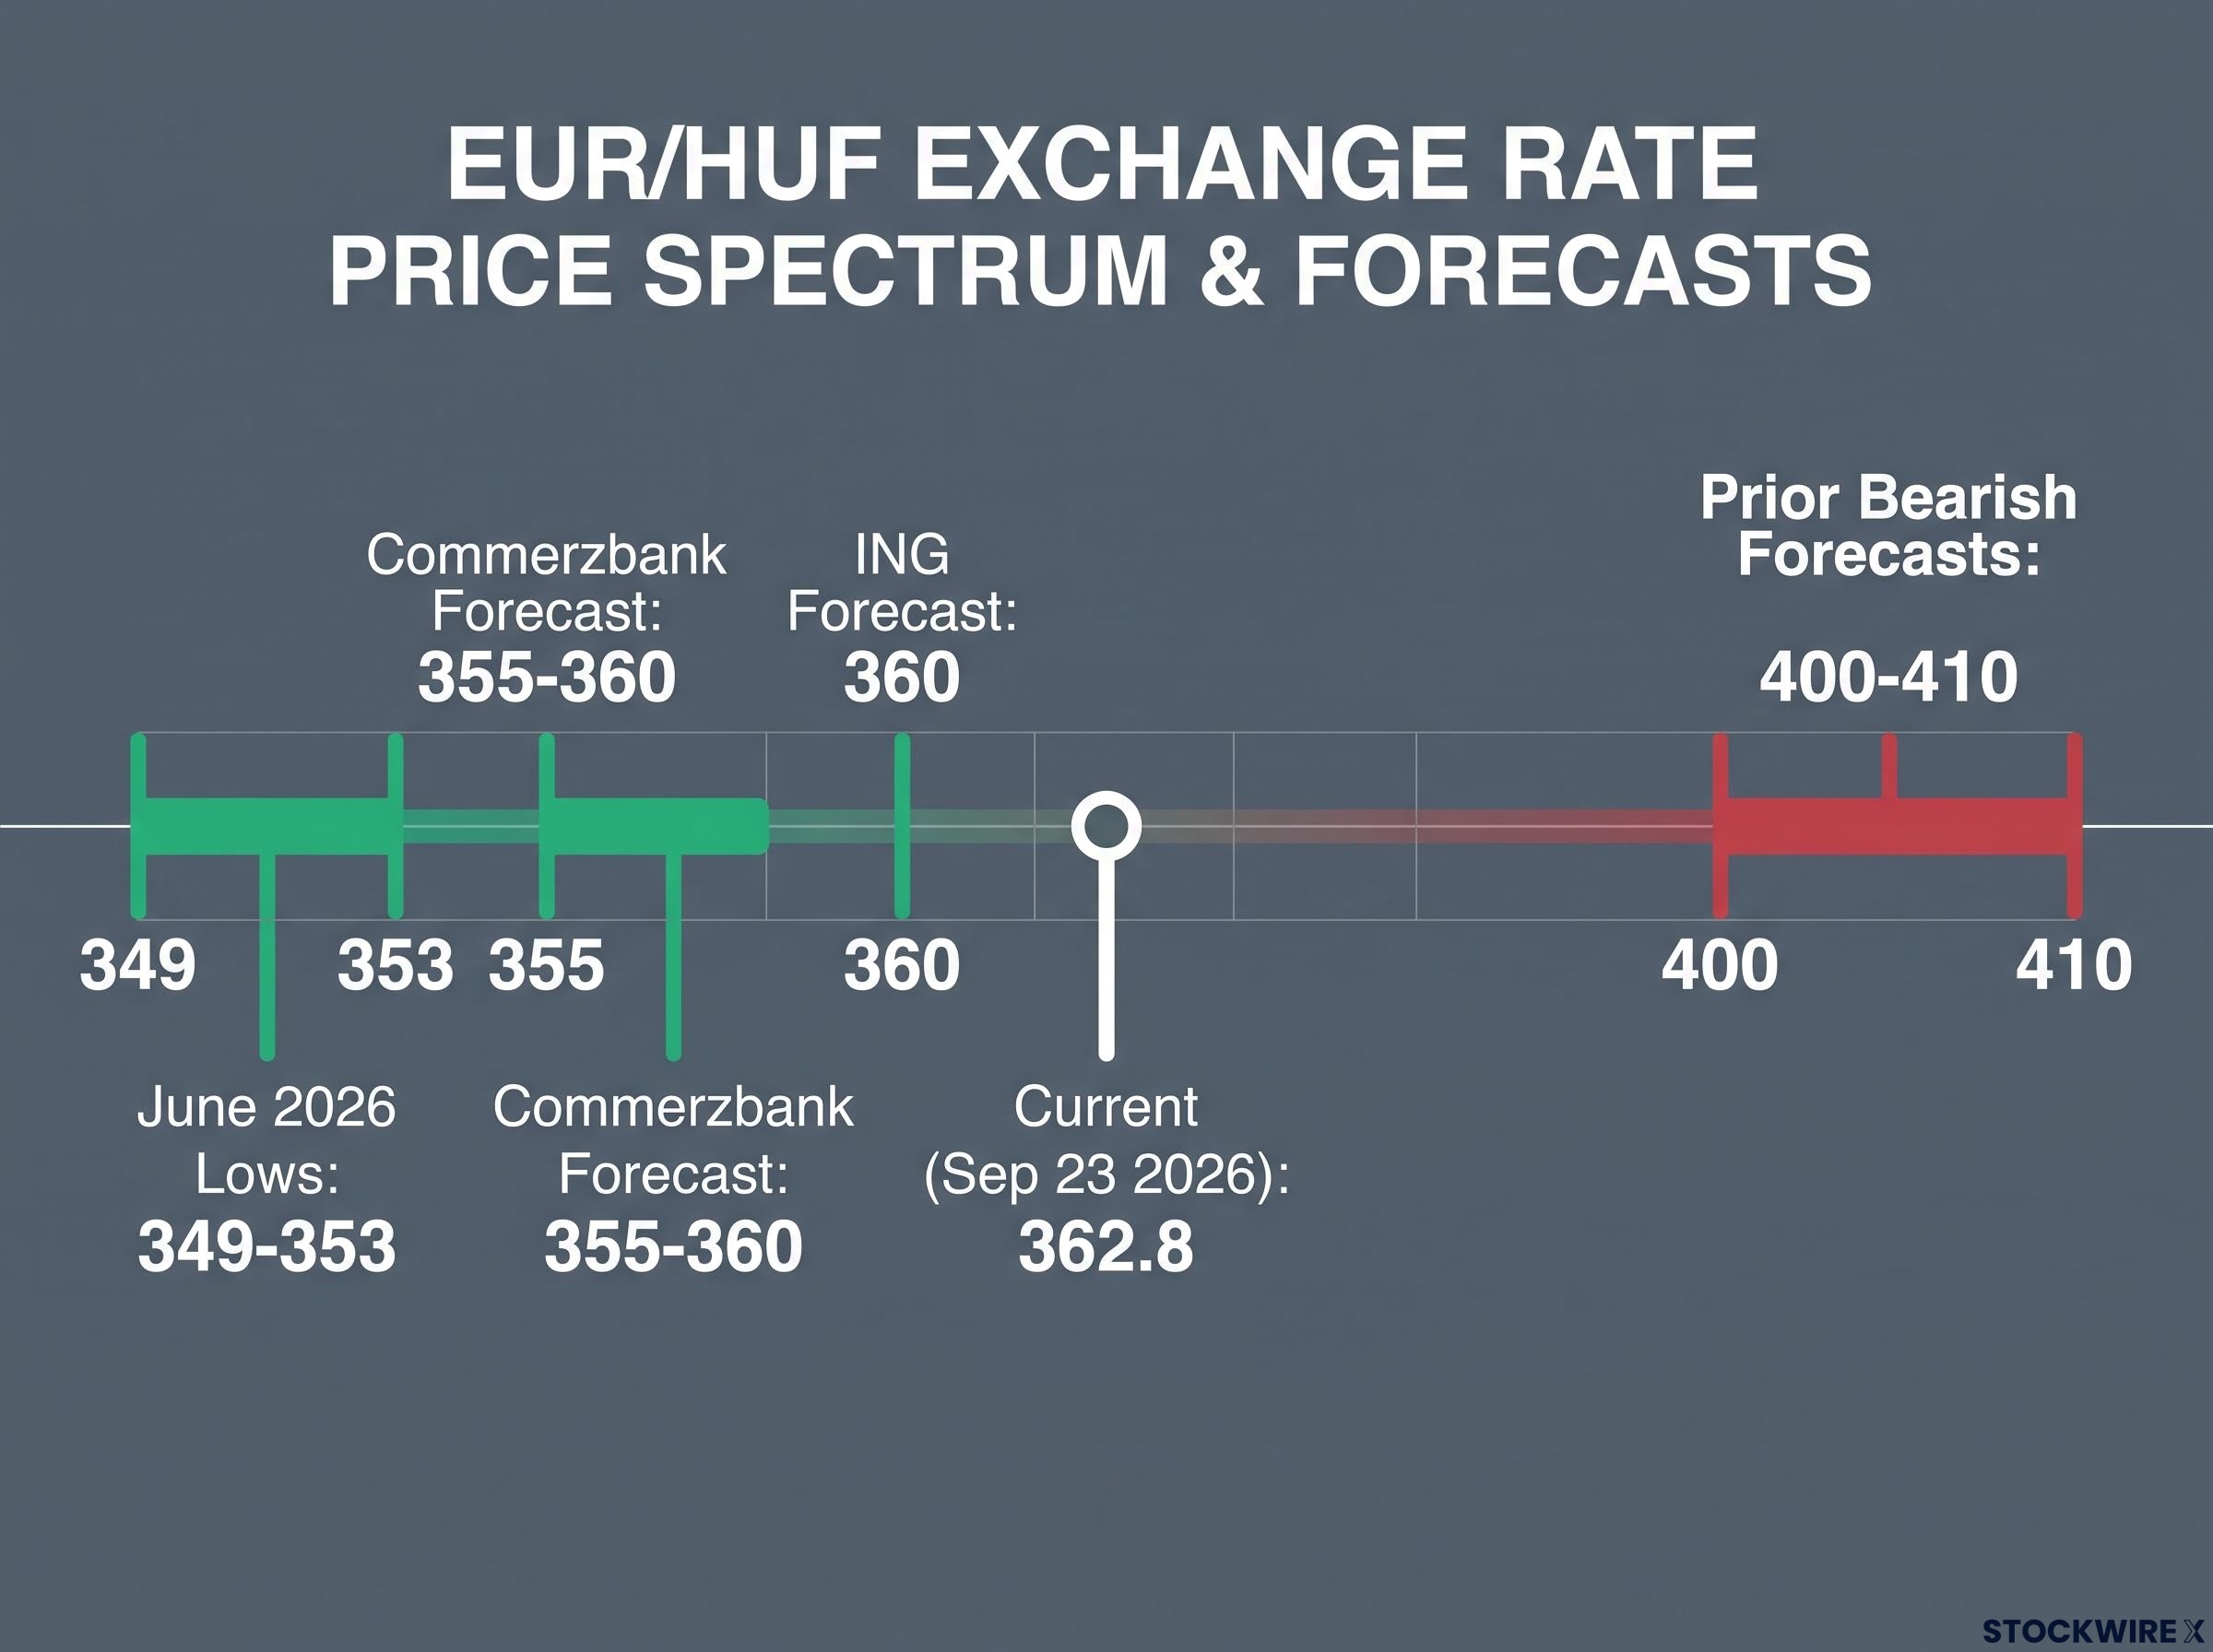
Something shifted in how markets priced the forint this year, and the numbers tell the story before any strategist does. EUR/HUF fell to lows of 349-353 in June 2026 before settling near 362.8 on 23 September 2026, a round trip that left the pair hovering just above a level traders now watch closely.
The catalyst may have crystallised the day before. The National Bank of Hungary held its base rate at 5.50% on 22 September 2026, breaking a run of four consecutive cuts, and in the same breath lowered its inflation target from 3.0% to 2.5%, effective January 2028.
That combination matters more than either move alone. Halting the easing while tightening the bar it sets for itself signals a bank confident in disinflation yet deliberately guarding the real-rate cushion that has carried the forint through a rough external stretch.
This is the Hungarian Forint outlook in its current form: a currency with a credible domestic anchor and a long list of things that can knock that anchor loose. What follows here separates the domestic signals working in the forint’s favour, the external variables that can unwind them fast, and what the wide gap between professional forecasts reveals about navigating any of it.
How the NBH’s policy pause reframes the forint narrative
The forint’s 2026 owed a great deal to a rate path that moved in one direction until it stopped. The Magyar Nemzeti Bank held at 6.50% in January, then cut steadily: to 6.25% in February, 6.00% in June, 5.75% in July, and 5.50% in August. Four cuts in six months, each smaller in consequence than the pause that followed.
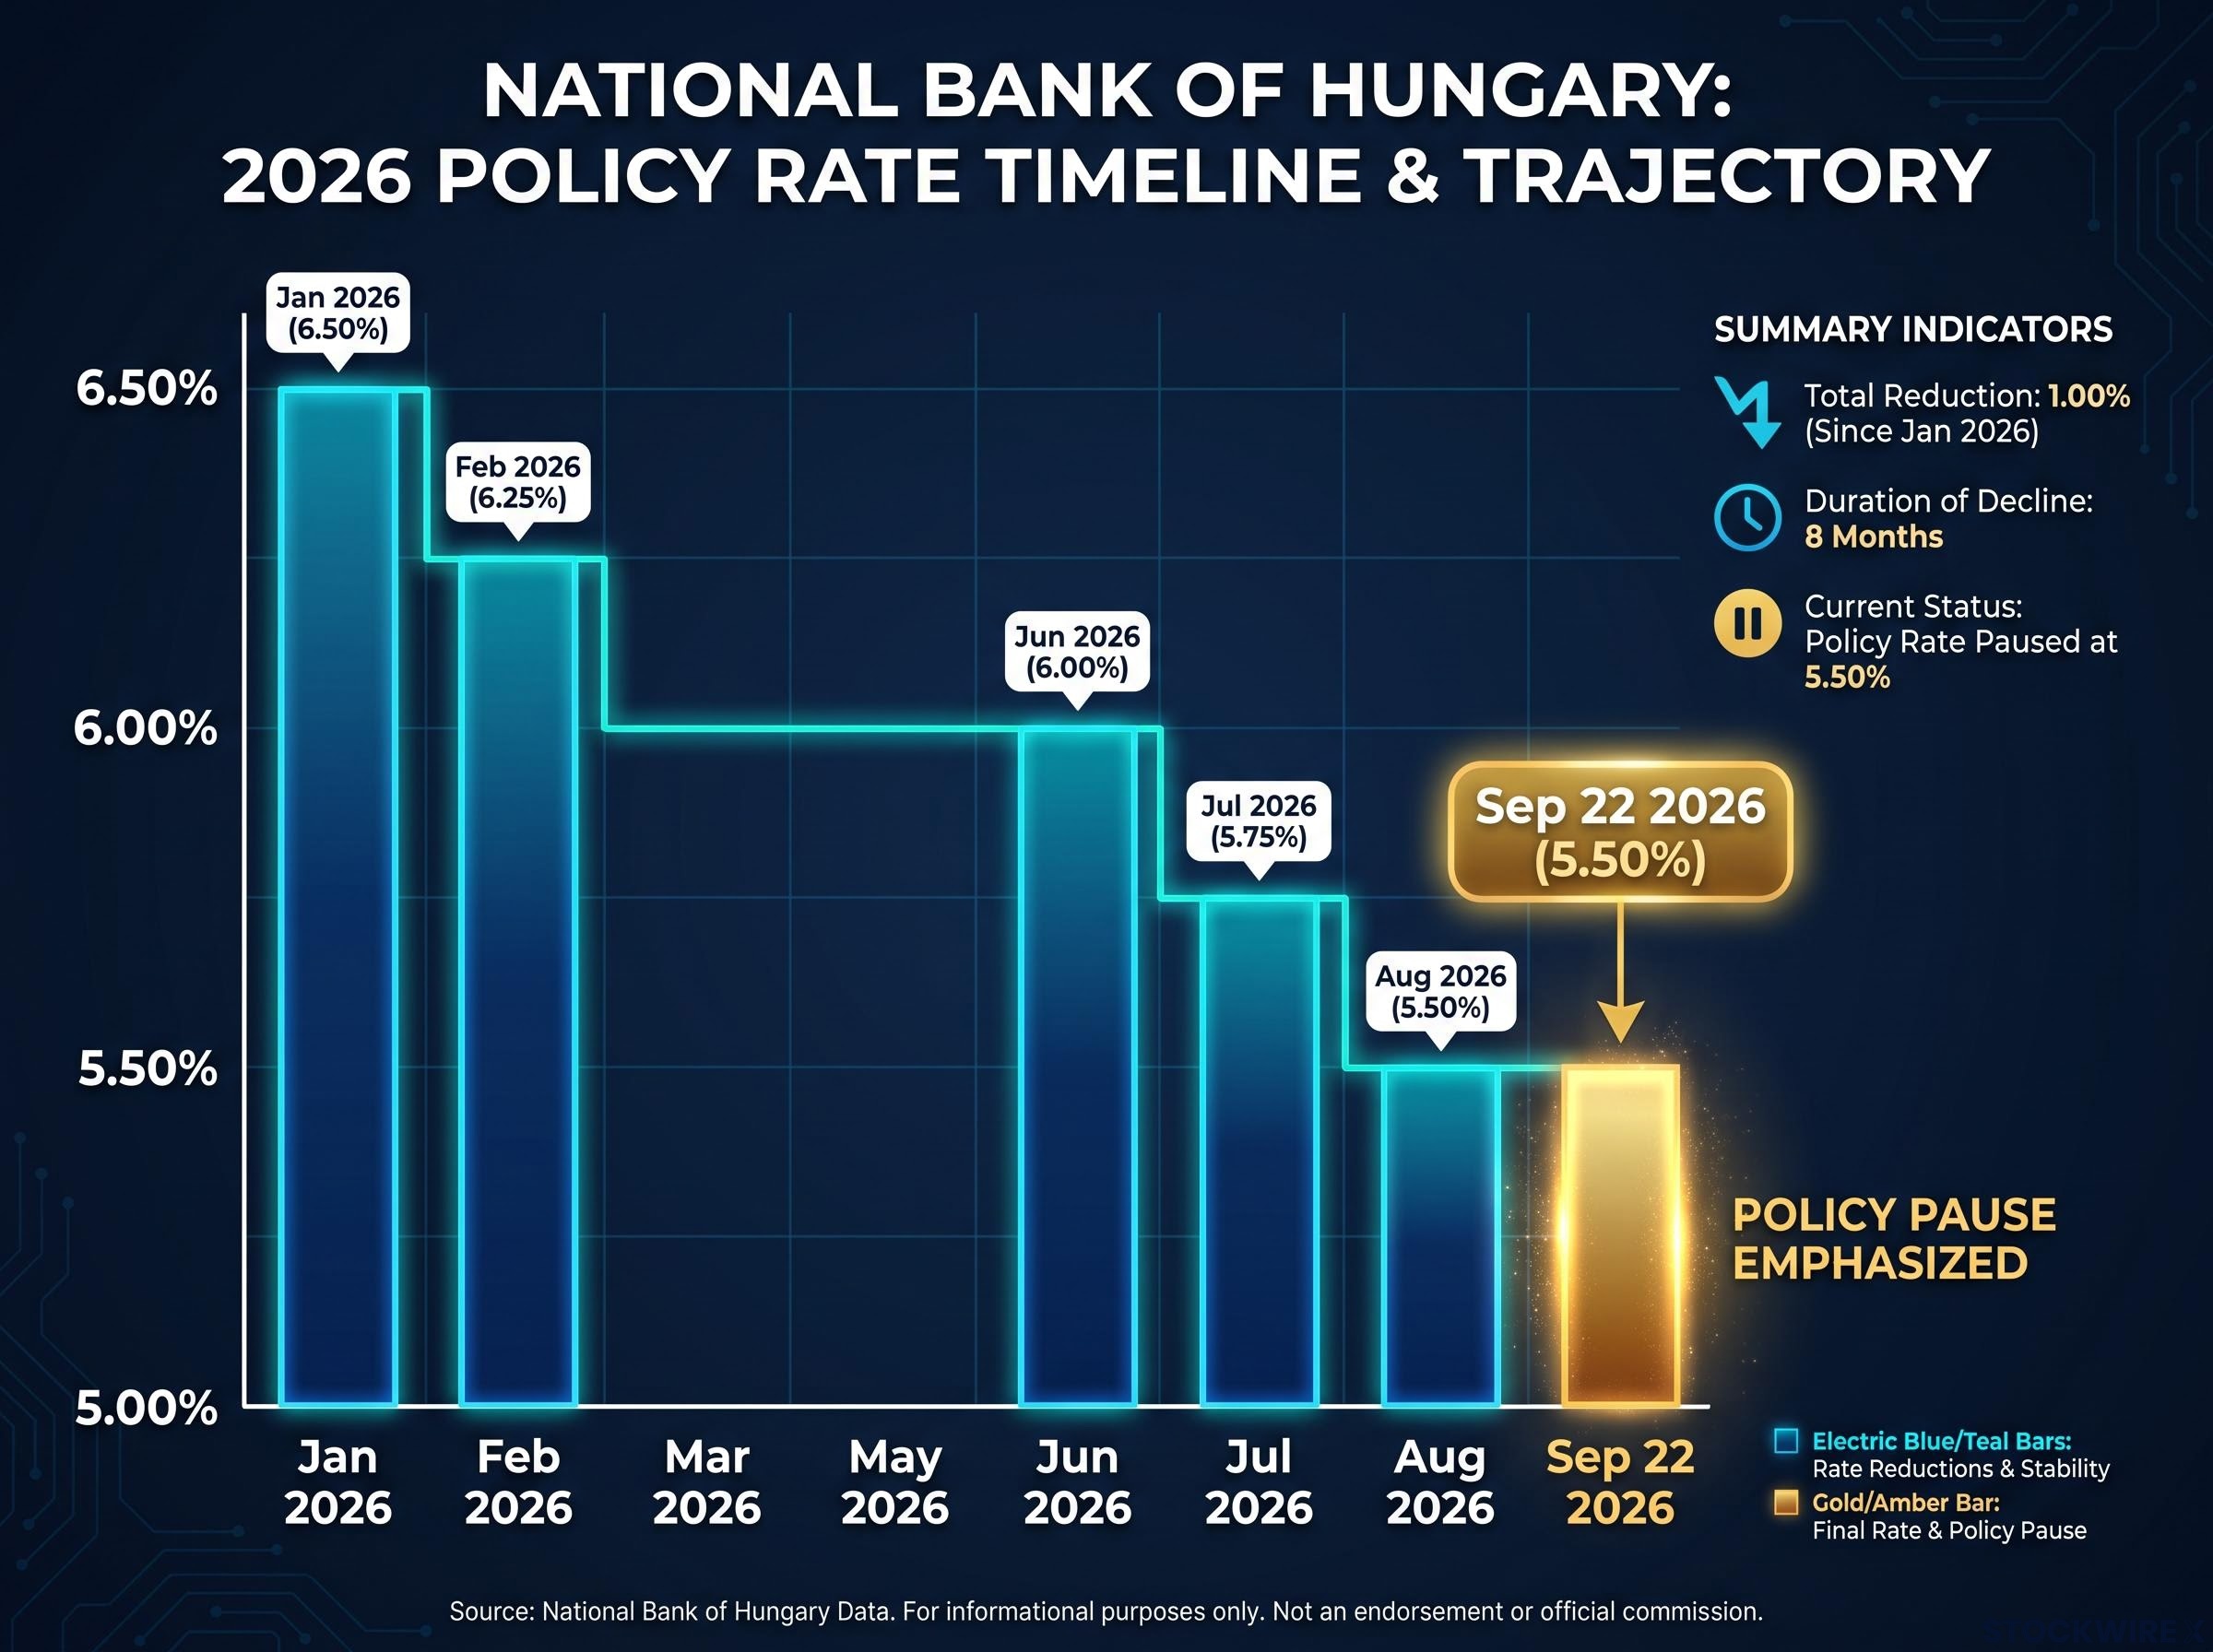
On 22 September 2026, the Monetary Council held at 5.50%, with the overnight deposit rate at 4.50% and the overnight collateralised loan rate at 6.50%, both unchanged. After a pre-committed glide lower, standing still is a decision in its own right.
| Date | Decision | Base Rate | Notes |
|---|---|---|---|
| 27 Jan 2026 | Hold | 6.50% | Cycle starting point |
| 24 Feb 2026 | Cut | 6.25% | First cut of the year |
| 23 Jun 2026 | Cut | 6.00% | Easing continues |
| 21 Jul 2026 | Cut | 5.75% | Inflation near decade low |
| 25 Aug 2026 | Cut | 5.50% | Fourth consecutive cut |
| 22 Sep 2026 | Hold | 5.50% | Data-dependent pause |
What made the pause both technically clean and politically comfortable was the inflation picture underneath it. August CPI ran at roughly 1.3% year-on-year, near the lowest reading in nearly a decade and well below the NBH’s own 3.1% projection for the coming year.
The KSH August 2026 CPI release confirmed that consumer prices rose 1.3% year-on-year, the official baseline underpinning the NBH’s decision to hold rates rather than extend the cutting cycle into the autumn.
That gap is the tell. The bank expects inflation to reaccelerate toward 3.1% even as it commits to a tighter target, which means the pause is not the closing chapter of the easing story but the opening of a more conditional one.
What the 2.5% inflation target actually signals
The mechanics of the target change are straightforward: a tighter nominal anchor, the same symmetric ±1 percentage point tolerance band, and a longer runway to implementation in January 2028. Nothing about it forces the bank’s hand today.
That is precisely the point. Announcing a stricter target while inflation sits at 1.3% is a credibility play, not a reaction to current prices. The NBH is telling carry investors it intends to defend real returns over the medium term, which reframes each future inflation print as a test of whether it means it.
When big ASX news breaks, our subscribers know first
Where professional forecasters stand on EUR/HUF, and why they disagree
With EUR/HUF at roughly 362.8 on 23 September 2026, having tested 349-353 in June before drifting back above 360, the pair sits at a level where credible strategists genuinely part ways. The spread between their views is not noise. It is information about how much uncertainty is baked into this trade.
ING’s Frantisek Taborsky holds a cautiously bullish forint bias. Supportive domestic policy and a long end of the Hungarian yield curve expected to drift lower underpin his case for a retest of 360, though he stresses the trajectory hangs heavily on global conditions cooperating.
ING’s Frantisek Taborsky frames the forint as constructively positioned on domestic fundamentals, with a 360 EUR/HUF retest as a plausible scenario, while cautioning that the currency’s path remains heavily contingent on the external environment.
Commerzbank’s Antje Praefcke, writing on 22 September 2026, reads the same policy mix as forint-supportive. The 5.50% rate and the lower inflation target, in her framing, sustain carry attractiveness and confidence in NBH policy, pointing to a stable 355-360 band through the rest of 2026.
| Analyst | Firm | EUR/HUF View | Key Conditions | Downside Risk |
|---|---|---|---|---|
| Frantisek Taborsky | ING | Retest of 360 | Supportive domestic policy, lower long-end yields | High contingency on global conditions |
| Antje Praefcke | Commerzbank | 355-360 band through end-2026 | High real rate, credible disinflation framework | Global rates, USD, regional sentiment |
Set that against where consensus sat not long ago. Earlier bearish forecasts pointed to EUR/HUF rebounding toward 400-410, a call that market action has already walked straight through.
Here is the analytical read you should take from that. Credible desks recently expected the pair near 400-410 while it currently trades at 362.8, which is a strong argument for holding any forecast, including the constructive ones, with real epistemic humility. The breadth of prior disagreement was not forecaster error alone. It was a signal of structural uncertainty that has not gone anywhere.
Koruna rate pricing, with markets embedding up to 125 basis points of CNB tightening over twelve months against ING’s scepticism that rates breach 4.00%, illustrates the same forecaster divergence the forint faces: the gap between consensus pricing and institutional analyst calls is itself a signal of structural uncertainty rather than analytical error.
The external risk architecture that can unwind a constructive domestic story
A clean domestic story does not make a clean trade, because the forint sits inside a web of external levers that can move together and overwhelm even well-run policy. These risks do not queue politely. They compound.
Three channels do most of the work:
- USD strength and Fed policy: When the Fed holds rates high or signals slower easing, global risk-free yields stay elevated, the dollar stays firm, and EM carry compresses, pushing capital out of currencies like the forint and into dollar assets.
- Energy prices: As a net energy importer, Hungary sees its terms of trade deteriorate when energy prices rise, widening external deficits and feeding directly into headline inflation, which can force the NBH into pro-cyclical tightening.
- Geopolitics: Proximity to the Russia-Ukraine conflict and reliance on regional energy flows means escalation hits risk appetite, energy costs, and Hungarian growth expectations in one correlated shock rather than three separate ones.
The forint’s energy import exposure, with 75-87% primary energy dependency and 80-95% of natural gas sourced from Russia, means CEE currency stress does not arrive in isolation; a TTF gas spike hits the current account deficit, erodes carry appeal, and triggers self-reinforcing FX selling in the same correlated move.
The reason the September pause reads as constructive is that none of these has fired at scale. The NBH’s 5.50% rate against 1.3% CPI leaves a wide real-rate buffer that insulates the forint, but only while that differential holds. The margin for error is narrow, and each channel can compress it.
What history says about EM currency stress and the NBH’s response capacity
The precedents show how fast this develops. The 2013 taper tantrum and the 2018 EM selloff both turned sentiment against high-yielding, externally exposed currencies within weeks, dragging capital out and FX with it. Speed is the defining feature.
During the 2022-2023 inflation surge, EUR/HUF temporarily traded above 430, prompting the NBH into emergency tightening tools and rapid rate hikes to stabilise the currency.
That episode carries two lessons. It shows the actual tail risk in a forint position when domestic credibility and global conditions deteriorate at once, and that tail is not a thought experiment. It also proves the NBH has both the willingness and the toolkit to intervene, which puts a partial floor under the bearish case.
Where does the forint sit in the credibility spectrum? Against CEE peers, the zloty, the koruna, the leu, Hungary’s real-rate buffer keeps it competitive. Against higher-beta names like the Turkish lira and South African rand, currencies weighed by weaker real yields and debasement risk, the forint reads as a comparatively anchored story. Even the September relief rally in global markets was judged insufficient to shift the broader negative backdrop, which is why the pause preserved optionality rather than declaring victory.
EM currency dynamics and what drives the forint that domestic data alone cannot explain
To read the forint properly, treat it as an emerging-market asset first and a Hungarian one second. Domestic monetary policy sets the terms, but global capital flows decide whether anyone shows up to trade on them.
The carry trade sits at the centre of this. A carry trade means borrowing in a low-yielding currency, typically the euro or dollar, to hold a higher-yielding one and pocket the rate difference. The forint’s appeal as a carry currency depends entirely on that differential, and right now it is being squeezed from both sides.
- From above: the NBH’s cutting cycle has pulled the Hungarian rate down from 6.50% to 5.50%, shrinking the yield on offer.
- From below: the Fed holding rates high keeps funding costs elevated, narrowing the gap that makes the trade worthwhile in the first place.
What has held the trade together is the real-rate buffer, and that concept is what separates the forint from weaker EM peers. A real rate is the policy rate minus inflation, and with a 5.50% rate against roughly 1.3% CPI, the forint offers an implied real return of about 4.2 percentage points.
BIS research on US rate transmission to EM currencies links a 100-basis-point rise in the US term premium to roughly a 6% depreciation in emerging market FX, which is the quantitative foundation behind the intuition that a firmer dollar or a longer Fed hold compresses forint carry regardless of how well the NBH runs its own policy.
| Country | Policy Rate | Estimated CPI | Implied Real Rate | Credibility Signal |
|---|---|---|---|---|
| Hungary | 5.50% | ~1.3% | ~4.2pp | Tighter target, preserved buffer |
| CEE peers (zloty, koruna) | Varies | Varies | Positive | Generally anchored by policy credibility |
| Higher-beta EM (lira, rand) | Varies | Elevated | Weaker or negative | Higher debasement risk, weaker anchor |
A real rate near 4.2 percentage points places the forint in the upper tier of CEE carry attractiveness. That is genuine carry, compensation for holding the currency, rather than thin yield offsetting debasement risk, which is what distinguishes it from higher-beta peers.
ING characterised EM resilience through mid-2026 as notable given the global headwinds, a durability it credited to disinflation narratives, central bank credibility, and steadier commodity prices. Read the inflation target cut through that lens: lowering the bar to 2.5% signals to carry investors that the NBH intends to protect real returns over a medium-term horizon, not just hand over a fleeting nominal rate. That buffer, though, lasts exactly as long as the bank’s commitment to the new target, which turns every future inflation print into a credibility test worth tracking.
What the NBH’s credibility bet means for HUF through the rest of 2026
Pull the threads together and the domestic case is coherent. The NBH has run an orderly cutting cycle, held onto a substantial real-rate buffer, and anchored expectations with a tighter target, all of which favours the forint against its peers.
The construction is conditional, though, not automatic. ING’s 360 retest and Commerzbank’s 355-360 band are both plausible, and both carry explicit dependencies on the external environment staying manageable.
Both the ING and Commerzbank cases for the forint rest on the same fragile precondition: that the external environment, USD strength, Fed policy, energy prices, and regional geopolitics, remains contained. The domestic anchor is real, but it is not self-sustaining.
Three variables tell you in real time whether the constructive story holds:
- Hungarian monthly CPI prints: track them against the NBH’s 3.1% forecast. Stay low and the cutting cycle stays frozen with carry intact; overshoot and the rate market starts pricing hikes.
- Fed signals and the USD trajectory: a firmer dollar or a longer Fed hold compresses forint carry from below, regardless of NBH quality.
- European energy prices: watch the read-through to Hungarian terms of trade, the channel most likely to force pro-cyclical tightening.
Do not expect false resolution here. The forecaster split that produced a 400-410 camp and a 355-360 camp at once is the correct analytical posture for this currency, not a flaw to be tidied away.
Making a calibrated call on HUF in a high-uncertainty EM environment
The takeaway is not a direction. It is a conditional structure you can revise as data arrives, which in a high-uncertainty EM currency is a sturdier position than any point forecast.
Taken together, the NBH’s September decisions form a coherent posture: pause the cuts, tighten the target, preserve the real-rate buffer, and watch the incoming data before committing further. The prior split between 355-360 and 400-410 was never a failure of method, just a fair reading of genuine uncertainty, and today’s environment carries equivalent ambiguity pointing the other way.
The logic breaks cleanly two ways:
- Constructive case triggers: CPI stays low and the Fed softens, giving the forint room toward the 355-360 central tendency or the ING 360 retest.
- Risk case triggers: energy prices spike or the Fed holds longer, and the external channels dominate regardless of how well the NBH runs policy.
Keep the tail in view. EUR/HUF sits at 362.8 today, having recovered from 349-353 in June, but the above 430 peak of 2022-2023 is not a museum piece. It is a live scenario if the external risk architecture deteriorates in a correlated way, and that distance is your practical risk calibration.
For investors exploring how to position across EM asset classes in a weaker-dollar scenario, our dedicated guide to EM local-currency bond dynamics covers the three compounding advantages of EM bonds over EM equities as a carry expression, including the 6.9% carry yield and the portfolio diversification case, with specific analysis of where forint-denominated instruments sit in that framework.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and the scenarios described here are speculative and subject to change based on market developments.