

FY27 revenue guidance upgraded to $37.5m–$40.0m on back of strong contract momentum
Synertec Corporation Limited (ASX: SOP) has upgraded its FY27 revenue guidance from $29.5m–$31.7m to $37.5m–$40.0m, an increase of approximately $8.0m–$8.3m across the range. The upgrade is anchored to two forces: the recently awarded $45.5 million ANSTO Nuclear Medicine Manufacturing Program contract, and broader contract conversion and momentum across both the Engineering and Powerhouse businesses.
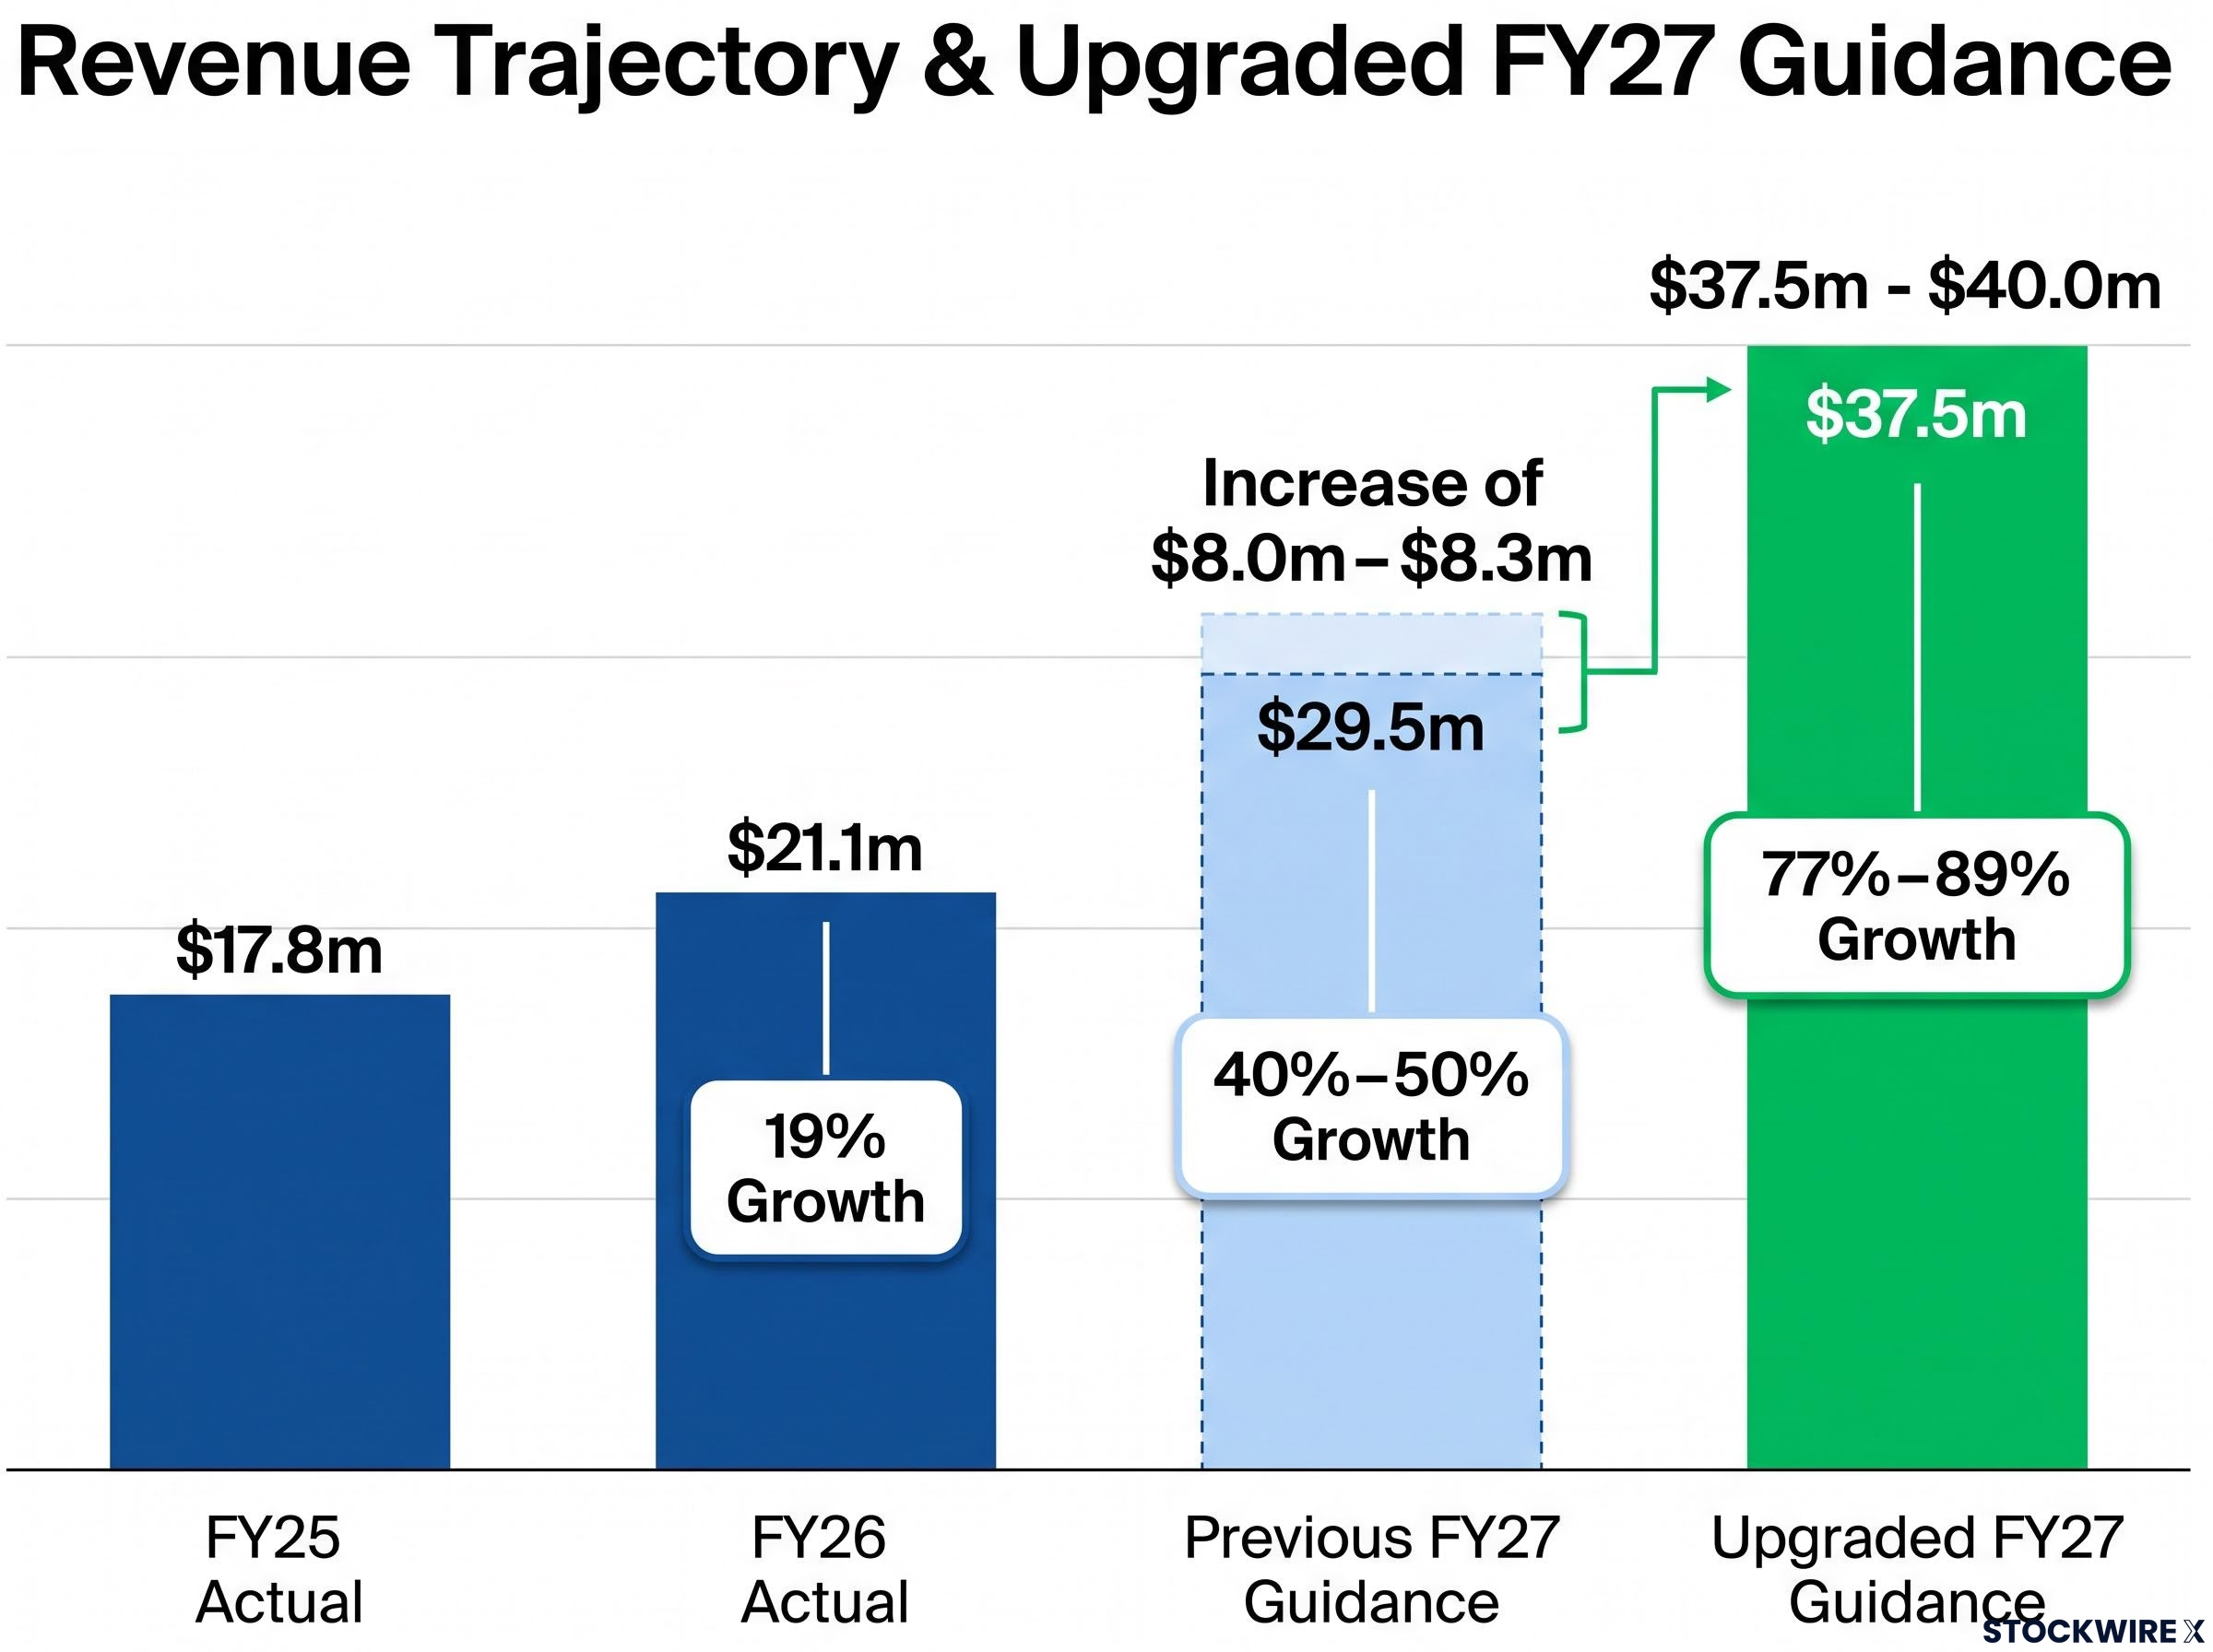
The revised guidance implies growth of approximately 77%–89% on FY26 external revenue of $21.1 million, a material re-rating of near-term revenue expectations for the company.
When big ASX news breaks, our subscribers know first
FY27 guidance at a glance
| Metric | FY25 Actual | FY26 Actual | Previous FY27 Guidance | Upgraded FY27 Guidance |
|---|---|---|---|---|
| Revenue ($m) | 17.8 | 21.1 | 29.5–31.7 | 37.5–40.0 |
| Growth on PCP | — | 19% | 40%–50% | 77%–89% |
The latest upgrade, representing an increase of approximately $8.0 million to $8.3 million compared with the previous FY27 guidance range, signals a meaningful improvement in execution quality and revenue visibility rather than a modest incremental revision.
The FY26 cash turnaround marked Synertec’s first positive full-year operating cash flow since FY19, with work in hand reaching $20.9 million, up 188%, providing the contracted base from which the current FY27 guidance upgrade has been built.
What’s driving the upgrade — and why it goes beyond ANSTO
While the ANSTO contract is the headline item, Synertec has been explicit that the guidance upgrade reflects a broader strengthening of the business across multiple contract wins, project advancements, and growing activity in both business units.
ANSTO validates the pipeline — but only added ~$9m to it
Synertec uses a probability-weighted methodology when reporting its Engineering pipeline, meaning the estimated likelihood of winning each opportunity is factored into the reported figure before any formal contract award. As a result, the $45.5 million ANSTO contract increased the previously disclosed Engineering pipeline of $174 million by only approximately $9 million, because a substantial portion of the opportunity had already been incorporated within the reported pipeline prior to award.
For investors, this is a meaningful signal. It suggests the pipeline is conservatively and credibly constructed, and that future contract conversions carry genuine incremental weight when they occur.
Engineering and Powerhouse both contributing
The key drivers disclosed across both business units include:
- Strong contract conversion in Engineering across government, healthcare, nuclear, and critical infrastructure markets
- The ANSTO Nuclear Medicine Manufacturing Program contract ($45.5m)
- Accelerating commercial momentum and project progression across Powerhouse
- Increased revenue visibility from contracted work
- Continued execution of the company’s industry diversification and geographic expansion strategy
Managing Director Michael Carroll
“We are pleased to upgrade our FY27 revenue guidance following strong contract conversion and operational momentum across both our Engineering and Powerhouse businesses. The ANSTO contract is a significant milestone; however, the upgraded outlook reflects a broader strengthening of the business, with increased revenue visibility across multiple projects and customers…”
Understanding Synertec’s two-engine business model
Synertec operates across two distinct business units, and the structure matters for understanding how revenue diversification is built into its growth trajectory.
The Engineering division provides technology design, development, and engineering services across government, healthcare, nuclear, and critical infrastructure sectors. The ANSTO Nuclear Medicine Manufacturing Program contract is a flagship example of the type of long-duration, high-value work this division pursues.
The Powerhouse division is a commercial-stage business focused on low-carbon technology solutions for energy and advanced manufacturing markets.
The Hitachi Energy BESS partnership, a 36-month MoU targeting integrated 5MW to 30MW battery energy storage solutions across energy, data centres, mining, and critical infrastructure, is one of the commercial structures expanding the Powerhouse division’s addressable market well beyond its current contracted base.
This dual-engine structure means revenue is not concentrated in a single sector or contract type, a factor that becomes increasingly relevant as the company scales toward $40 million in annual revenue. Synertec’s broader mission is enabling a low-carbon future through scalable, environmentally friendly technology for global markets.
What the guidance upgrade means for investors
This is not a minor revision. The upgrade represents a structural re-rating of FY27 revenue expectations, and several factors are worth considering:
- The guidance upgrade represents an increase of approximately $8.0 million to $8.3 million compared with the previous FY27 guidance range.
- Implied growth of 77%–89% on FY26 revenue represents an acceleration, not a plateau.
- The ANSTO pipeline methodology validation supports confidence in the previously disclosed $174m Engineering pipeline, as the conversion process has now been demonstrated at scale.
- Revenue visibility is increasing, with contracted work underpinning guidance and reducing reliance on pipeline conversion alone.
- Synertec has not provided FY27 guidance for EBITDA, EBIT, NPAT, or operating cash flow. The upgraded guidance relates to revenue only, consistent with the approach adopted in the company’s previous FY27 guidance.
The upgraded guidance is subject to the following assumptions:
- Delivery of contracted work in accordance with current project schedules
- Mobilisation and execution of recently awarded contracts
- Continued progression of Powerhouse projects
- Revenue recognition in line with current project execution assumptions
- No material adverse changes in customer schedules, project delivery timing, economic conditions, supply chains, or foreign exchange rates
Don’t Miss the Next ASX Industrials Breakout
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ investors who stay ahead of the market the moment announcements hit. Click the “Free Alerts” button at Big News Blast to start receiving alerts across Tech, Healthcare, Industrials, and more.