
BetMakers posts 205% Adjusted EBITDA jump as technology strategy drives FY26 turnaround
In its FY26 full-year results presentation released in August 2026, BetMakers Technology Group (ASX: BET) reported Adjusted EBITDA of $14.1M, up 205% on the prior corresponding period.
Management framed the result around three pillars: revenue growth, margin expansion, and cost discipline. Revenue reached $92.6M, an 8.8% increase (11.2% on a constant currency basis), while the Adjusted EBITDA Margin lifted to 15.2% from 5.5% a year earlier.
The company, which operates a technology-led global racing wagering platform, presented the year as continued execution of a turnaround strategy, supported by an Adjusted Gross Margin of 66.9%.
When big ASX news breaks, our subscribers know first
FY26 headline results at a glance
The presentation summarised a full-year performance defined by top-line growth and materially reduced losses. The company delivered revenue growth alongside a $3.1M reduction in operating expenses, driving disproportionate gains at the EBITDA line.
| Metric | FY26 | FY25 | Var ($) | Var (%) |
|---|---|---|---|---|
| Revenue | $92.6M | $85.1M | $7.5M | 8.8% |
| Gross Profit | $60.7M | $54.5M | $6.2M | 11.4% |
| Operating Expense | ($49.4M) | ($52.5M) | $3.1M | 6.0% |
| Adjusted EBITDA | $14.1M | $4.6M | $9.5M | 205.1% |
| NLAT | ($5.2M) | ($25.3M) | $20.3M | 79.9% |
The net loss after tax (NLAT) narrowed by 79.9% to $5.2M. On the margin side, the statutory Gross Margin in the P&L was 65.5%. After adjusting for a $1.3M inventory write-off, the Adjusted Gross Margin was 66.9%.
What drove the growth: digital, margin and cost discipline
Management attributed the EBITDA improvement to three levers working together:
-
Revenue growth of 8.8% year-on-year.
-
Adjusted Gross Margin improvement of 2.8 percentage points.
-
A $3.1M reduction in operating expenses.
Digital revenue leading the charge
Global Betting Services revenue rose to $43.3M, up from $34.5M in FY25. Domestic customers were the key contributors during the year, with an expanding set of international opportunities described as emerging.
New customers launched in the second half of FY26 were positioned by management as providing a foundation for growth in FY27.
The FY26 full-year result extends the momentum established in the 1H FY26 results, when BetMakers posted $6.0M Adjusted EBITDA on revenue of $46.1M, underpinned by the CrownBet and Stake partnership launches that seeded the second-half digital revenue acceleration.
Tote steady, content contributing
Global Tote revenue was $49.3M, compared with $50.6M in FY25. On a constant currency basis, this represented growth of 1.1% (FY25 constant currency revenue of $48.8M).
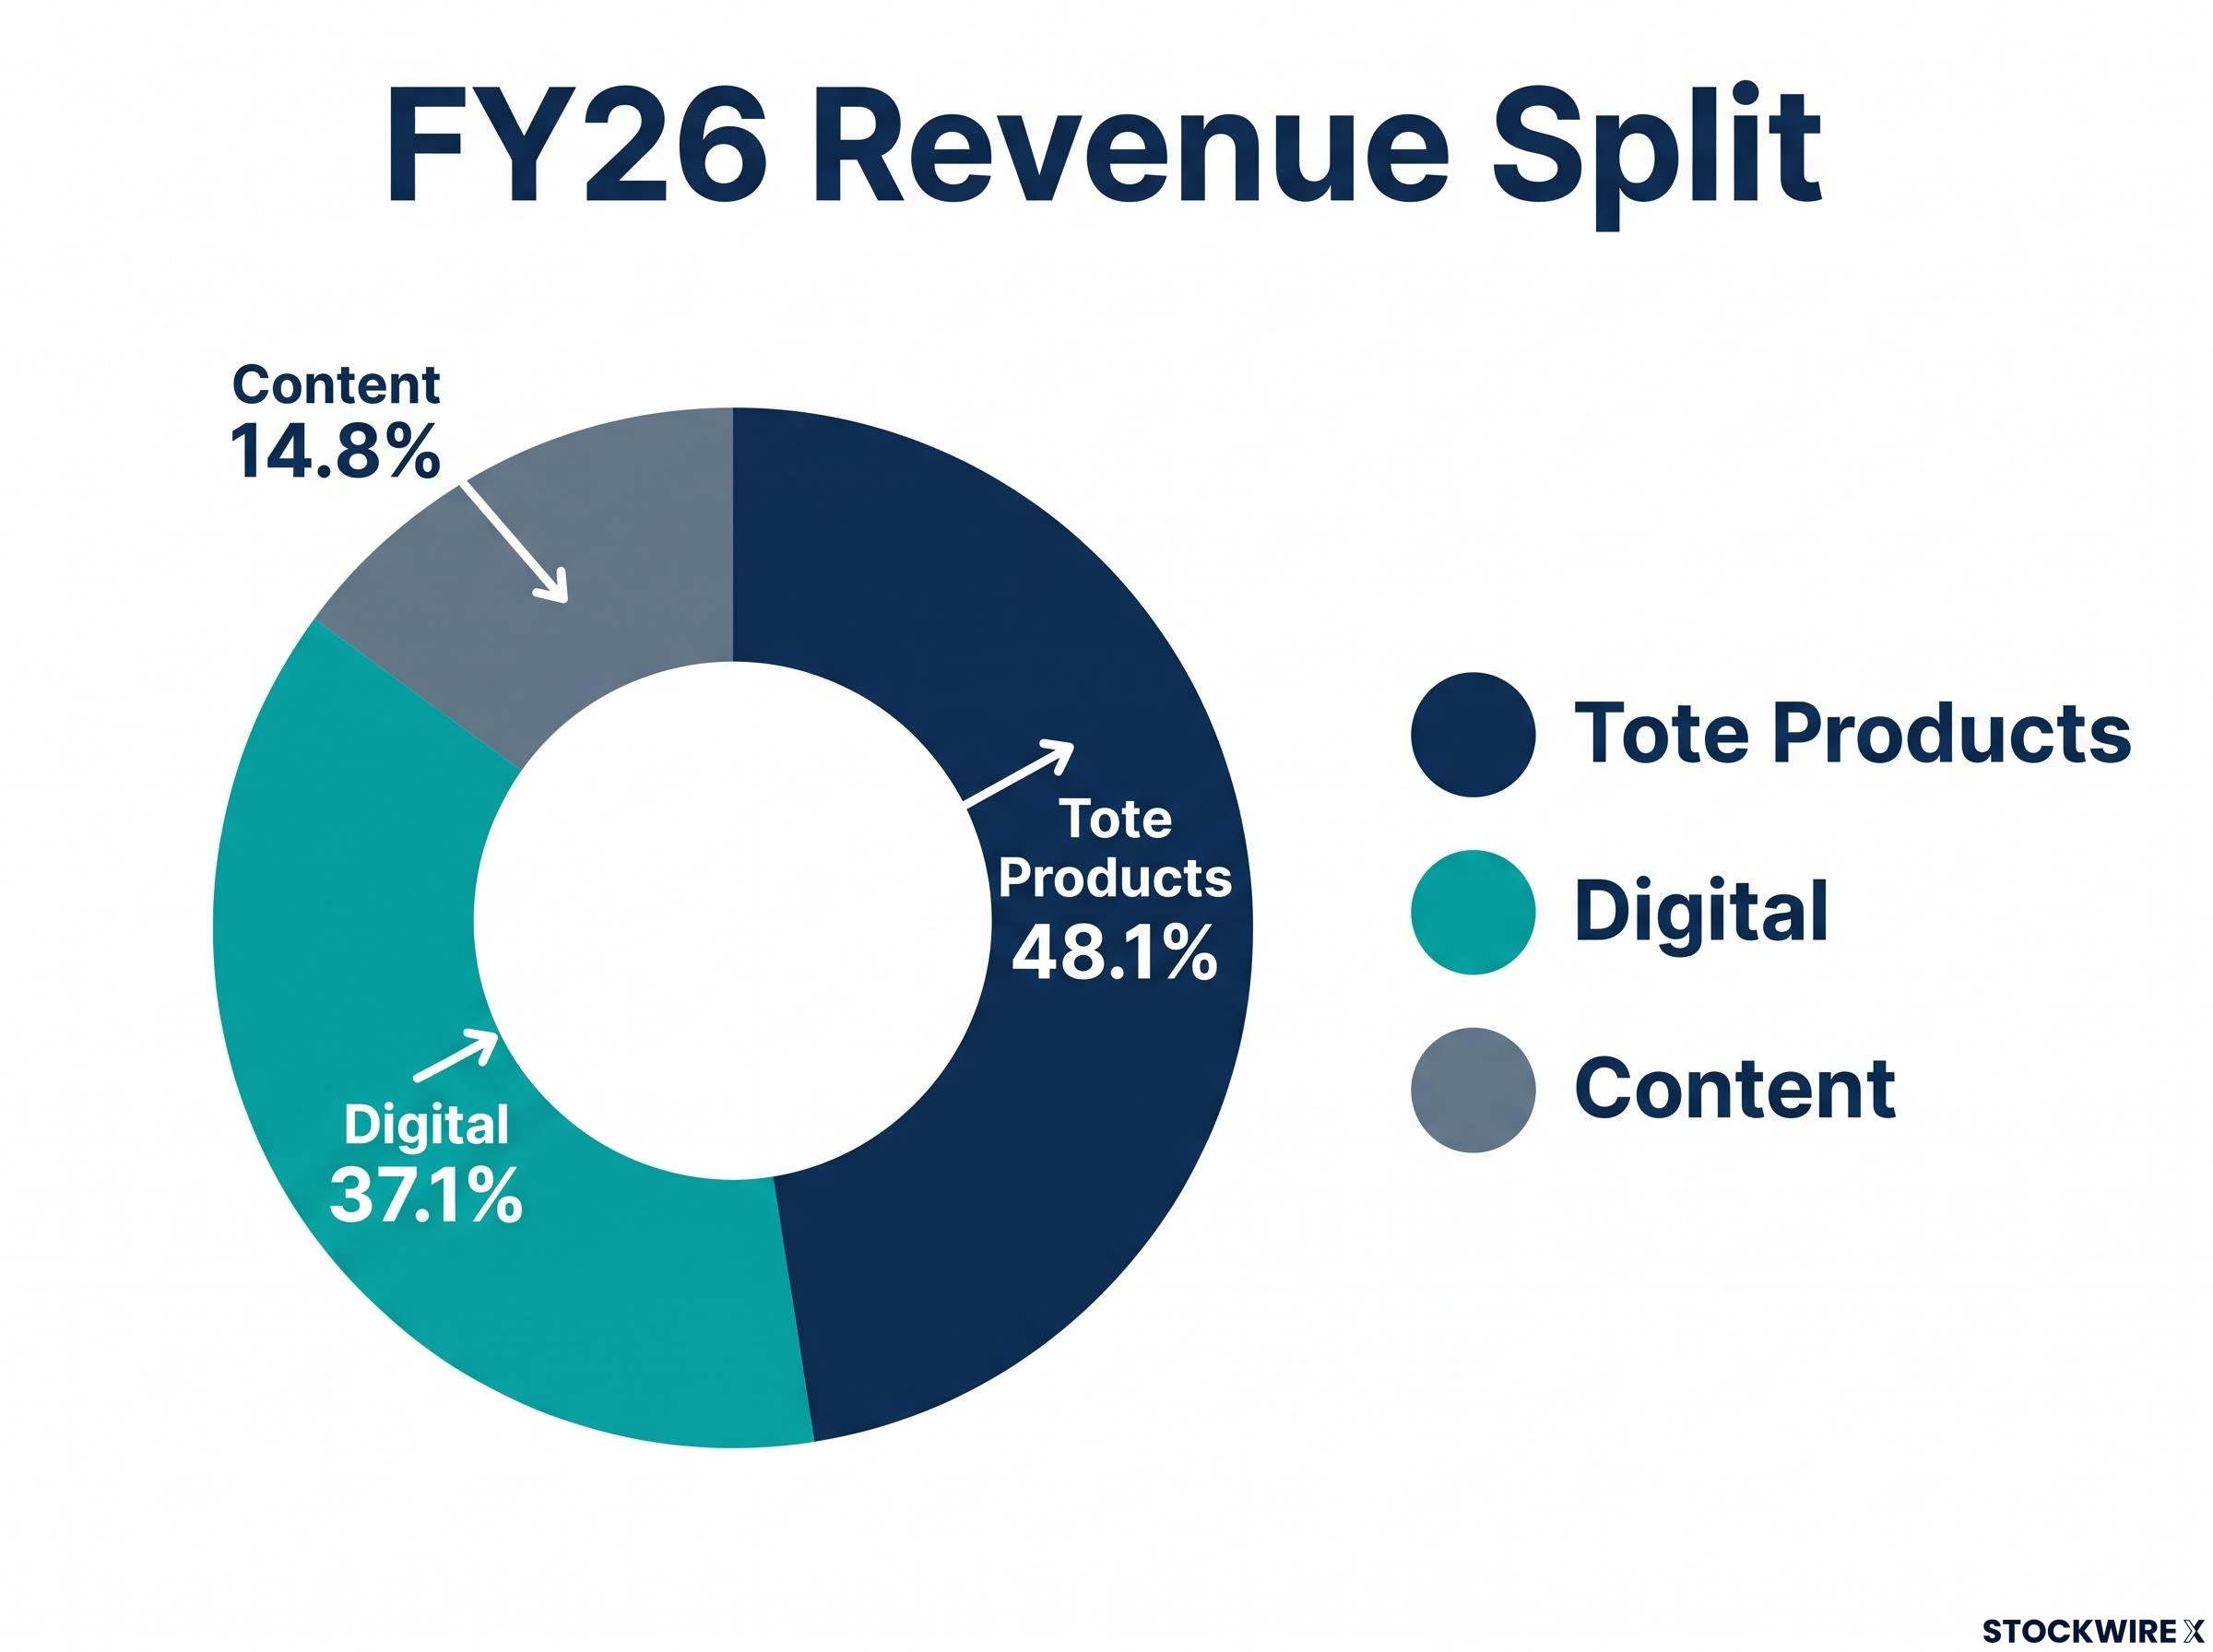
The company noted some customer churn during FY26, which partially offset steady performance across core tote hosting and managed services. The FY26 revenue split was Tote Products 48.1%, Digital 37.1%, and Content 14.8%.
Margin and cost leverage
Adjusted Gross Margin improved to 66.9% from 64.1%, with the unaudited Q4 FY26 figure reaching 68.5%, tracking towards the company’s stated long-term goal of 70.0%.
The restructured Penn contract (referenced in the ASX announcement dated 3 December 2025) improved the gross margin profile in the second half of FY26. Operating expenses fell to $49.4M from $52.5M, a reduction achieved despite the year’s revenue growth.
Cash flow strengthens as the business scales
The presentation highlighted continued improvement in operating cash-flow generation, extending a multi-year trajectory rather than marking a one-off shift.
-
Operating cash flow of $5.0M (FY25: $2.8M; FY24: -$9.7M), a $14.7M improvement versus FY24.
-
Unrestricted cash balance of $15.6M, down from $18.8M.
-
The $2.2M decrease included approximately $1.2M of costs associated with the acquisition of LVDC.
The trajectory signals that the turnaround is cash-backed, with the company stating it continues to work towards consistent free-cash flow generation as the business scales.
Understanding BetMakers’ racing technology model
For investors less familiar with the business, BetMakers operates a fully integrated racing ecosystem spanning Fixed Odds, Tote, and Data. This model is designed to deliver the full wagering value chain, positioning the company across key global racing markets.
A defining feature is its hybrid / variable revenue model, described in the presentation as a success-based revenue model “not reliant on ‘per-seat’ SaaS revenue.” Revenue is tied to platform activity rather than fixed licensing fees.
Why does this matter to investors? Incremental digital revenue carries a high gross margin. As the platform scales, this creates operating leverage, allowing revenue growth to convert into disproportionate EBITDA gains, as FY26 demonstrated.
The company also noted it continues to embed AI across its workflows, including development, pricing, content, and operations, with the stated aim of driving efficiencies and productivity.
Global footprint powering market leaders
The presentation conveyed the scale of the company’s network and its blue-chip client base across both Tote and Fixed Odds products.
-
Fixed Odds customers: Ladbrokes, Sportsbet, TABtouch, RMG, and William Hill.
-
Tote customers: Hipódromo Chile, Penn Entertainment, Caesars, UK Tote Group, Rikstoto, and Kentucky Downs.
Core infrastructure includes the Quantum™ Tote Engine, tote hosting, and international tote pooling, with management noting emerging opportunities to leverage its international tote network across an expanding digital customer base.
Investment thesis: a scalable platform hitting an inflection point
The presentation positioned FY26 as evidence of operating leverage becoming visible, with revenue growth converting to outsized EBITDA gains. Adjusted EBITDA has improved by $46M since FY23 and, on management’s figures, continues an upward trajectory.
The Q4 FY26 annualised run-rate reached $17.9M at an Adjusted EBITDA Margin of 18.2%, above the full-year margin of 15.2%.
Strategic positioning
“Well positioned for FY27 as the Company continues to execute on its technology-led growth strategy.”
For investors, the FY26 result demonstrates the model’s operating leverage in practice, with each incremental dollar of high-margin digital revenue contributing meaningfully to profitability.
FY27 outlook and strategic priorities
Management outlined three strategic priorities for FY27:
-
Further growth in digital revenues, both domestically and internationally, alongside expanded distribution capabilities and growth in content revenues and partnerships.
-
Ongoing cost base optimisation from technology efficiencies, driving further operating leverage.
-
Delivering Adjusted EBITDA growth and expansion of the Adjusted EBITDA margin.
The company noted that new deployments are expected in the first half of FY27, with continued opportunities to expand its content network.
Management concluded that the business has established a solid foundation heading into FY27, with a continued focus on operational discipline, technology innovation, and execution.
Don’t Miss the Next ASX Tech Turnaround
Big News Blast delivers FREE breaking ASX technology news directly to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ subscribers already staying ahead of the market. Click the “Free Alerts” button at Big News Blast to receive the next market-moving announcement the moment it drops.