

Nuix Neo drives full-year turnaround as Nuix swings to $16.4m profit
Nuix (ASX: NXL) delivered a strong FY26 result for the year ended 30 June 2026, with momentum from its Nuix Neo platform driving the improvement.
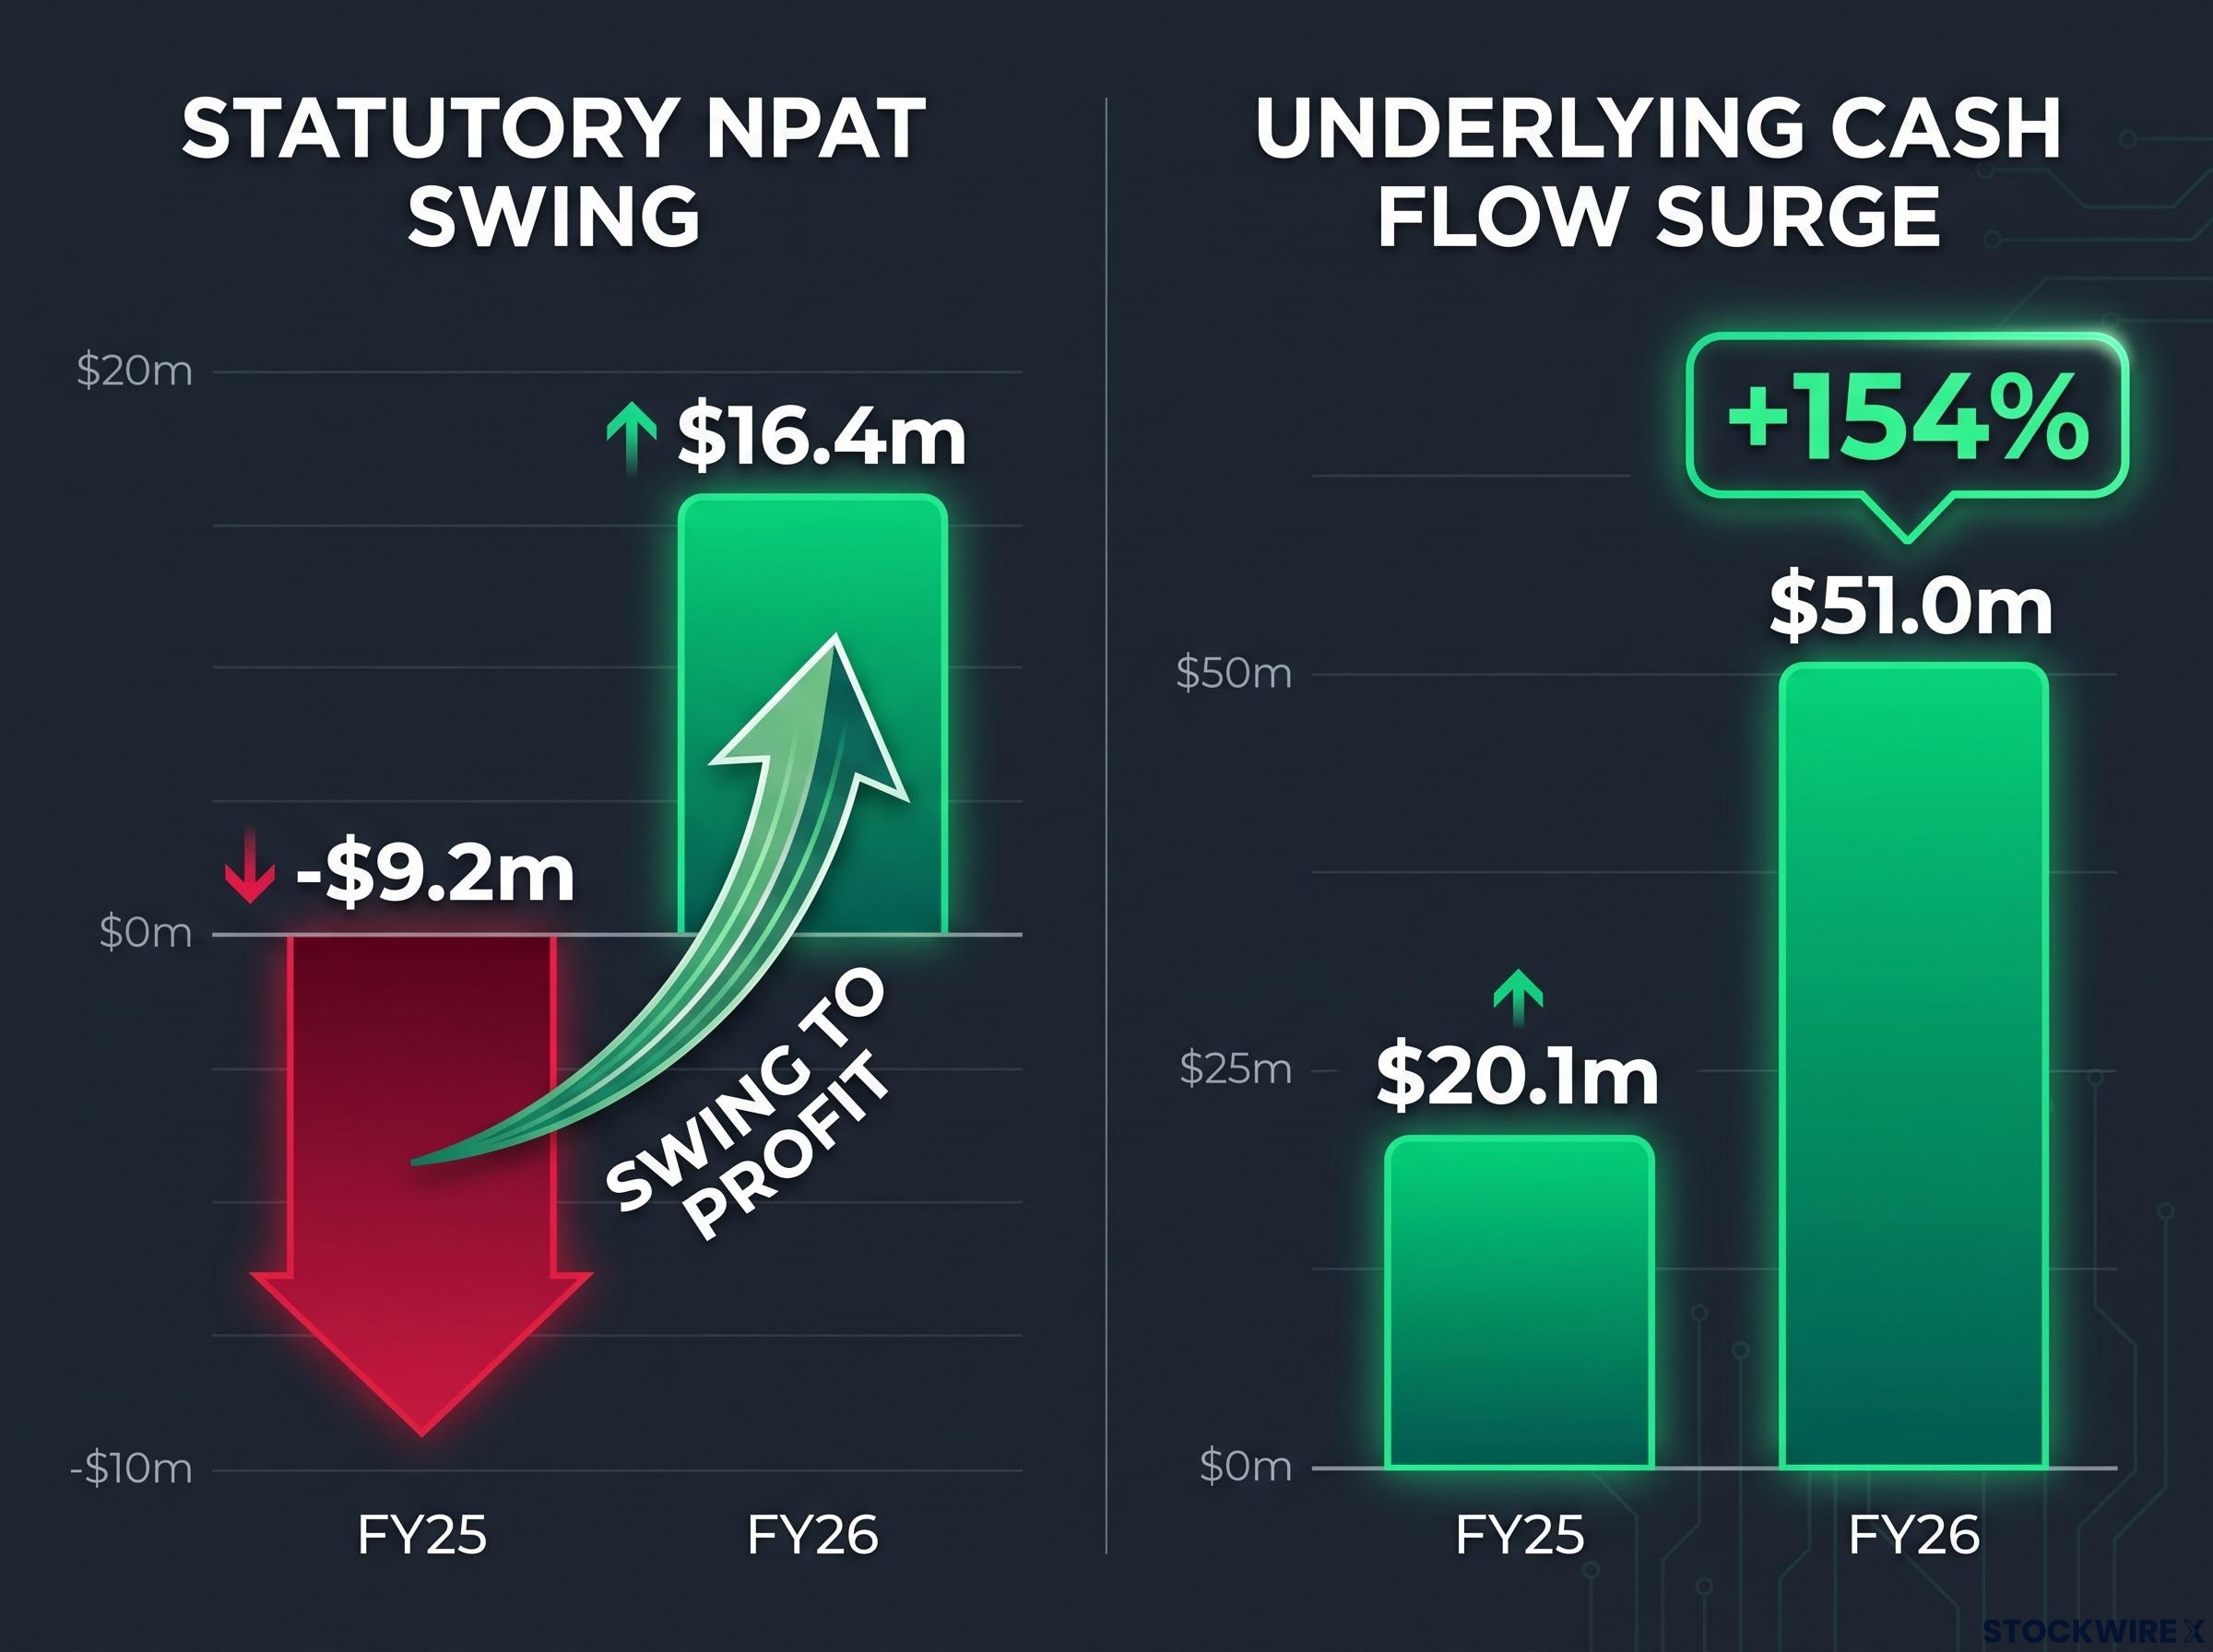
Annualised Contract Value (ACV) reached $260.0m, up 13.9%, while revenue climbed 18.8% to $263.2m. The standout outcome was the swing to a Statutory Net Profit After Tax (NPAT) of $16.4m, reversing a -$9.2m loss in the prior year.
The result marks a return to statutory profitability alongside a substantial lift in cash generation, both of which the Company identified as core strategic objectives for the year.
When big ASX news breaks, our subscribers know first
FY26 results at a glance
The table below compares FY26 performance against the prior corresponding period (pcp), FY25.
| Metric | FY26 | FY25 (pcp) | % change |
|---|---|---|---|
| Annualised Contract Value (ACV) | $260.0m | $228.4m | +13.9% |
| Revenue | $263.2m | $221.5m | +18.8% |
| Adjusted Management EBITDA | $59.8m | $37.2m | +60.4% |
| Statutory EBITDA | $66.9m | $47.6m | +40.5% |
| Statutory NPAT | $16.4m | -$9.2m | n.m. |
| Underlying Cash Flow | $51.0m | $20.1m | +154% |
| Net Cash | $49.9m | $40.0m | +24.8% |
The figures include the contribution from the Linkurious acquisition. Adjusted Management EBITDA margin expanded to 22.7% from 16.8% in the prior year. According to the Company, this met its stated strategic objective to grow revenue faster than operating costs, demonstrating expanding operating leverage across the business.
Nuix Neo emerges as the primary growth engine
Nuix Neo was the primary driver of growth during the year, with ACV surging 179% to $78.5m across 135 customers. The platform now represents 30% of total ACV, more than double its proportion twelve months ago. Growth was driven by migration, new customer acquisition, and upsell to existing Nuix Neo customers.
Supporting retention and revenue-quality metrics improved across the period:
-
Net Dollar Retention: 105.2% at year end, up from 101.0% at the half
-
Churn: 6.6%, improved on the prior year, although higher than the 1H result
-
Multi-year deals: rose to 35% of revenue, up from 27% pcp
-
Organic ACV (excluding Linkurious): +8.6%, or +11.1% in constant currency
The combination of Nuix Neo migration momentum and improving retention points to more durable, recurring revenue. Rising expansion within the existing customer base is a key indicator of the platform’s growing stickiness.
Strategic reset, from feature selling to platform value
FY26 was the year Nuix restructured its commercial model to shift from feature selling to platform value. The Company points to a large opportunity in enterprise unstructured data, spanning investigations, compliance, privacy, and AI, which it describes as multi-billion dollars in size. It identifies over 10,000 ICP accounts globally that meet its target criteria, with current penetration of less than 10%.
To capture this, the go-to-market structure has been realigned with enhanced commercial capability, operational from FY27:
-
Two regional sales teams (Americas and International), each led by a dedicated EVP for consistent execution and clearer accountability
-
A Chief Customer Officer leading global practices to strengthen retention and increase expansion revenue
-
A dedicated Sales Enablement function to improve pipeline conversion at scale
-
Discover separated into a dedicated go-to-market team to deliver on its growth potential independently of Nuix Neo
Apart from one-off restructuring costs, the new structure is described as essentially cost-neutral.
AI strategy and the R&D Accelerator
Nuix has established a structured approach to embedding AI across the organisation, with dedicated AI roles, model-agnostic tooling, and Digital FTEs (dFTEs) adopted as a universal measure of AI return on investment. The approach is designed to scale capacity rather than reduce headcount.
Management frames Nuix Neo’s governed data layer, model-agnostic BYO AI architecture, and full auditability as a defensive moat, with growing enterprise demand for data sovereignty positioned as a structural tailwind. A one-off $15m R&D Accelerator investment in FY27 will target five areas: Enterprise Integration and Connectivity, Agentic AI Capabilities, Cloud Platform Acceleration, Unified UI/UX, and Accelerated Innovation Cadence. Product and Technology teams have been unified under CTO ownership.
Linkurious acquisition and cash strength
The acquisition of Linkurious was completed on 20 April 2026, with integration progressing to plan and early cross-sell wins already secured. The strategic rationale is that Nuix Neo processes large volumes of complex, unstructured data, while Linkurious visualises the connections within it, together providing a complete workflow from raw data to visual intelligence.
The Linkurious acquisition, completed on 20 April 2026 for approximately A$27 million, was funded with $20 million in debt and roughly $7 million in existing cash, with around $30 million in undrawn facilities retained for future flexibility.
Linkurious contributed a $12.0m ACV run-rate at 30 June 2026, and $3.8m in revenue and $2.0m in EBITDA over the 72 days from financial close to year end.
Cash generation strengthened materially. Underlying cash flow rose 154% to $51.0m, while Free Cash Flow increased to $37.4m, up from $4.0m in the prior year. The closing net cash position was $49.9m, up 24.8%, after the Linkurious financial close.
On the regulatory front, the Federal Court dismissed all of ASIC’s claims against the Company and the then individual Directors. ASIC has appealed the decision only insofar as it concerns the Company, and that appeal is pending. The dismissal of all claims against the relevant individual Directors is final and not subject to appeal.
The Federal Court dismissed all of ASIC’s claims against Nuix and its former directors on 23 April 2026, resolving a five-year legal overhang that had weighed on management focus and investor sentiment throughout the period.
CEO commentary and FY27 outlook
John Ruthven, Chief Executive Officer
“FY26 was a year of profitable growth and decisive action. Financial performance was robust across key metrics, with ACV within our guided range, material increases in profitability and a substantial lift in cash generation. Nuix Neo continues to scale as the primary engine of profitable growth.
During the year, we made the structural changes required to shift from feature selling to platform value. We have restructured our go-to-market with enhanced commercial capability, established a clear AI strategy, and unified product and technology, backed by a one-off R&D Accelerator investment in FY27. These were decisive actions to position the Company to capture a significantly larger addressable market.
Looking ahead to FY27, we are building on continued underlying momentum. With enhanced commercial capability in place, continued investment in platform and AI capabilities, and a clear strategy for profitable growth, we are well positioned to capture the significant opportunity ahead.”
Nuix set out the following guidance for FY27:
-
FY27 ACV range: $285m – $300m
-
FY27 Adjusted Management EBITDA: similar to FY26, impacted by the one-off R&D Accelerator investment
-
Growth weighted to the second half, in line with prior years
-
Guidance assumes an AUD/USD rate of 0.70 (FY26 average: 0.68)
For investors, the FY26 result combines a return to statutory profitability with a substantial improvement in cash generation. The Company’s enhanced commercial capability, continued platform and AI investment, and a large under-penetrated addressable market frame the case management has put forward for sustained profitable growth into FY27.
Don’t Miss the Next ASX Tech Winner
Big News Blast delivers FREE breaking ASX tech news directly to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ subscribers already getting the edge on market-moving announcements the moment they drop. Click the “Free Alerts” button at Big News Blast to stay ahead of the market.