
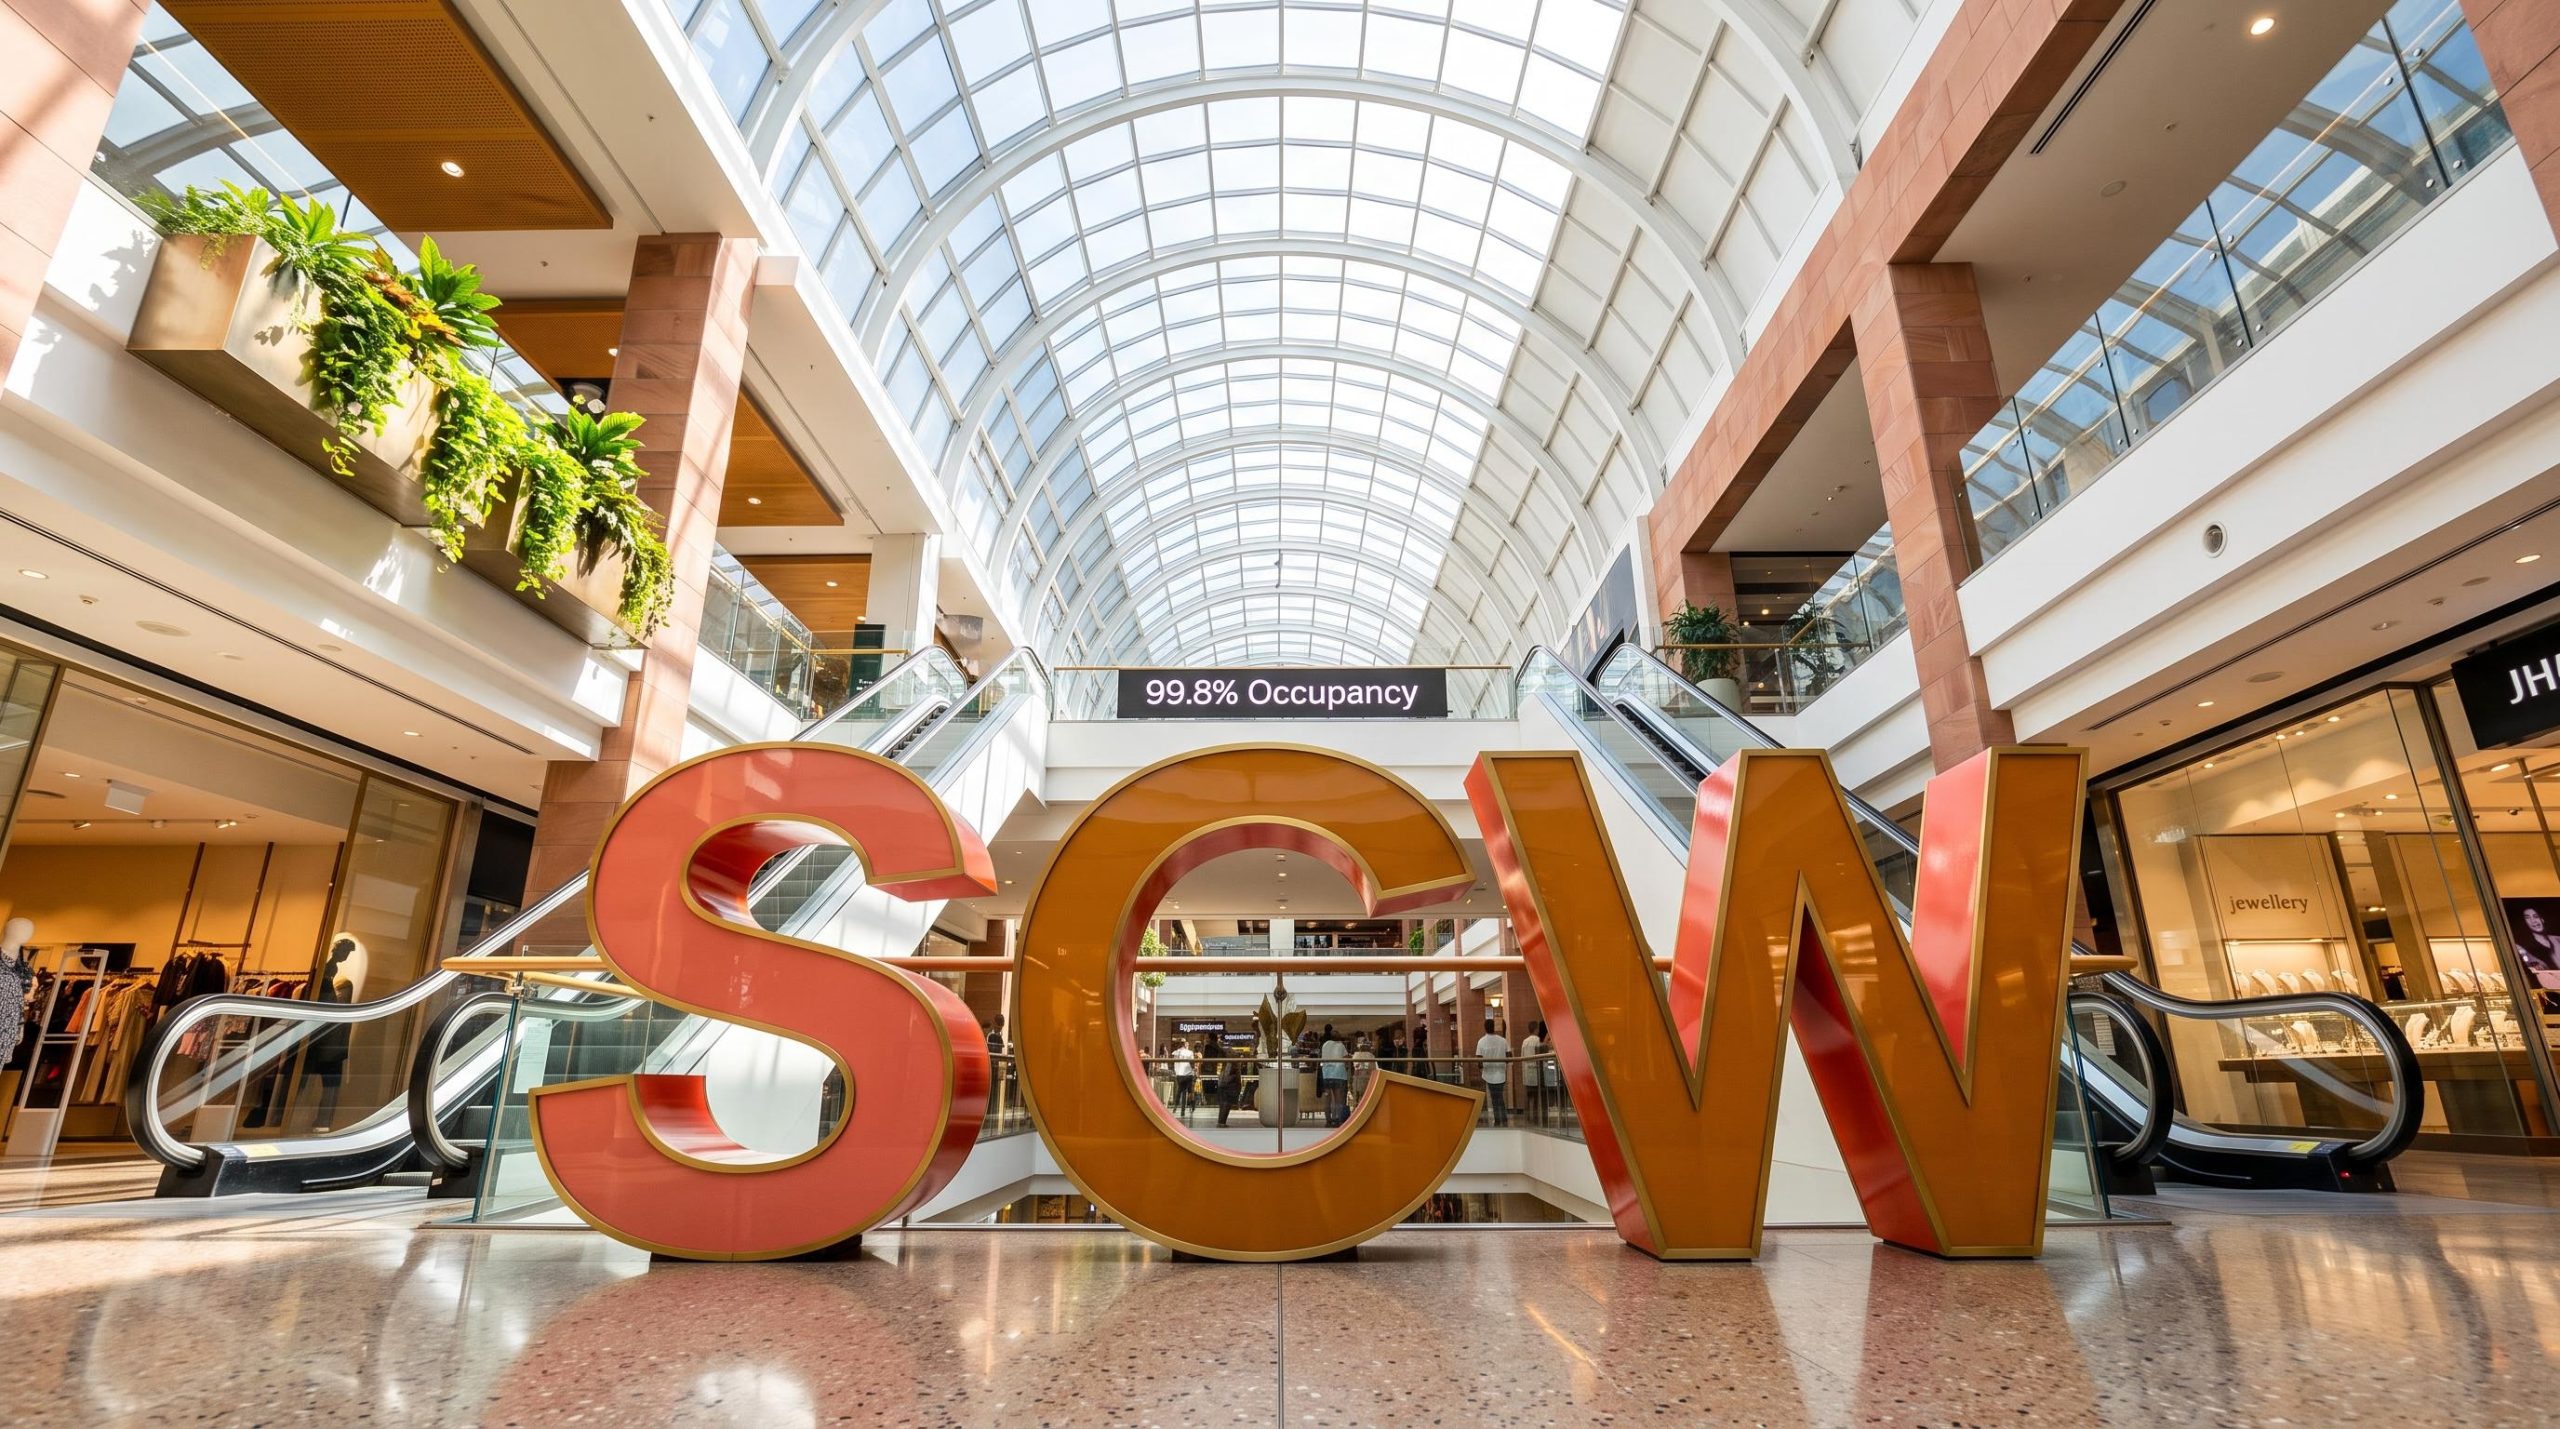
Record 99.8% occupancy and 554 million visits headline Scentre Group update
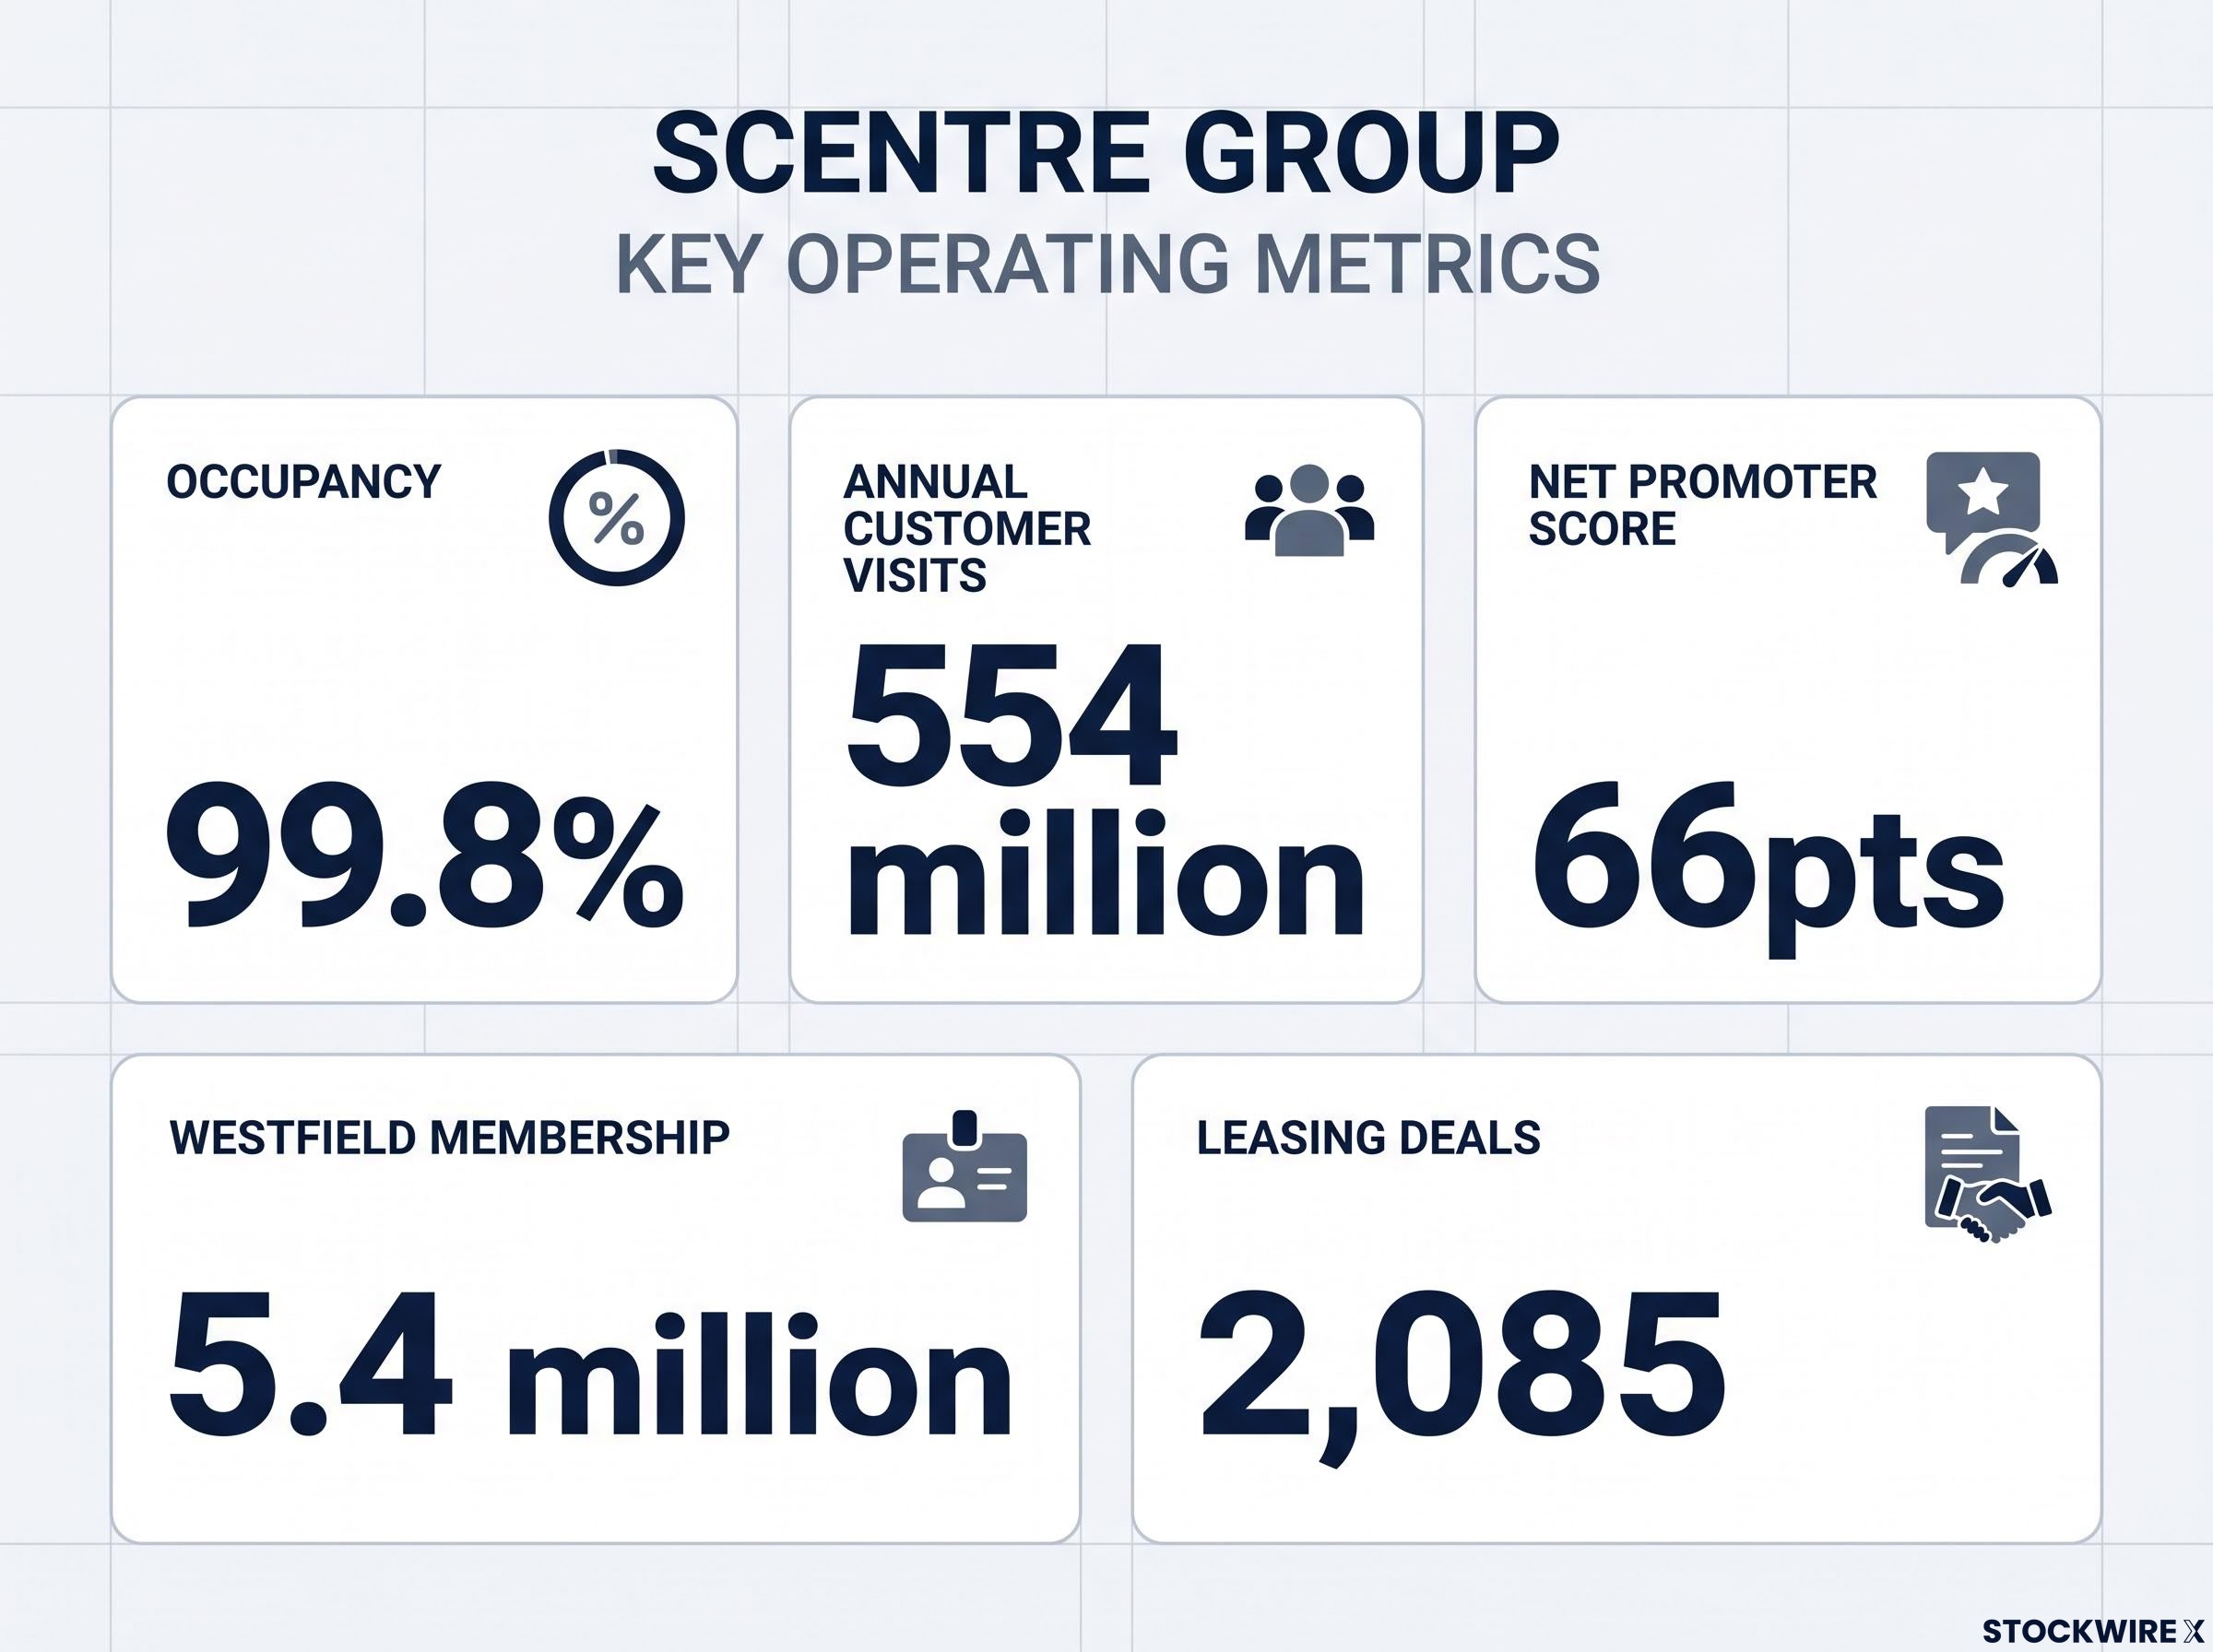
Scentre Group (ASX: SCG) has reported occupancy of 99.8% across its Westfield destinations, which the company says is at its highest level in more than a decade. Annual customer visits reached 554 million, up 3.1% or 17 million on the prior comparable period.
From the beginning of the year to 1 November 2026, the Group welcomed 452 million customer visitations, an increase of 3.2% or 14 million. The operating update, released on 4 November 2026, also reaffirmed a target for funds from operations (FFO) of at least 23.79 cents per security for 2026, representing at least 4.25% growth, subject to no material change in conditions.
Key metrics from the update include:
- Net Promoter Score: 66pts, up 12pts on the prior comparable period
- Westfield membership: 5.4 million, up 10.8%
- Leasing deals: 2,085 completed, with average specialty releasing spreads of +3.7%
- Average specialty rent escalations: 5.6% in the 9 months to 30 September 2026
Elliott Rusanow, Chief Executive Officer
“We continue to see strong demand for space in our destinations with occupancy of 99.8% which is at its highest level in more than a decade.”
When big ASX news breaks, our subscribers know first
Sales growth across the Westfield portfolio
Total annual business partner sales across the portfolio to 30 September 2026 were $30.5 billion, up $1 billion on the same period in 2025. For the three months ended 30 September 2026, business partners achieved total sales growth of 3.5%, with specialty store sales up 4.6%.
The table below shows sales growth over 2025 for selected categories, compared to the prior comparable period on a constant currency basis.
| Category | 12 months to 30 Sep 2026 | 9 months to 30 Sep 2026 | 3 months to 30 Sep 2026 |
|---|---|---|---|
| Total Specialties | 5.3% | 5.1% | 4.6% |
| Total Majors | 1.5% | 1.2% | 1.0% |
| Total | 4.0% | 3.7% | 3.5% |
| Health & Beauty | 8.4% | 8.8% | 8.7% |
| Jewellery | 9.1% | 8.6% | 8.2% |
| Fashion | 5.7% | 6.5% | 7.0% |
| Footwear | (2.8%) | (4.3%) | (4.2%) |
By region, New Zealand and Western Australia recorded the strongest growth. NZ sales rose 7.3% over 12 months, 8.7% over 9 months and 9.4% over 3 months, while WA posted 6.1%, 6.0% and 5.4% respectively.
Some categories were weaker. Footwear, Department Stores and Leisure & Sports each recorded negative growth in the three months to 30 September 2026, at (4.2%), (3.7%) and (2.8%).
What is a specialty rent escalation and why occupancy matters
Occupancy measures the share of available retail space that is leased. At 99.8%, almost all space across the Westfield portfolio is occupied.
Specialty stores are the smaller retailers in a centre, as distinct from major tenants such as supermarkets and department stores. A releasing spread compares the rent on a new or renewed lease with the rent previously paid on that space, while a rent escalation is the scheduled increase in rent during a lease.
FFO, or funds from operations, is a common earnings measure for property groups. It adjusts for items such as property revaluations to show the cash earnings generated by the portfolio. Strong occupancy alongside positive spreads and escalations is the pattern investors typically watch when assessing rental income and distribution capacity.
Developments, David Jones exposure and strategic land
Development pipeline
Scentre Group reported progress on three redevelopments:
- Westfield Bondi, Sydney: $240 million (SCG share $240 million). A Level 6 dining, entertainment and lifestyle precinct will be anchored by an upgraded Event Cinemas and a new Kingpin entertainment offer opening to the community in December.
- Westfield Penrith, Sydney: $30 million (SCG share $15 million), expanding the entertainment and lifestyle precinct and HOYTS Cinemas complex. It is fully leased.
- Westfield Tuggerah, NSW Central Coast: $20 million (SCG share $20 million), repurposing the former David Jones space. JD Sports and rebel are now open, with visitation up 6.2% on the prior comparable period in the eight weeks since opening.
At Westfield Eastgardens in Sydney, the Group’s expression of interest has been accepted for progression as a State Significant Development through the NSW Housing Delivery Authority. The proposal has the potential to deliver up to 1,300 dwellings.
David Jones exposure
Scentre Group noted recent media reports regarding David Jones and its owner Anchorage Capital Partners. The company set out its exposure:
- David Jones occupies space at 17 Westfield destinations, about 200,000 square metres.
- Gross rent from these stores in calendar year 2026 is $45 million (SCG share), or $352 per square metre against the portfolio average of $942.
- This represents approximately 1.8% of the Group’s gross rent and approximately 3.6% of FFO on an annualised basis.
David Jones has provided $45 million in bank guarantees across the Westfield Australia/New Zealand portfolio, of which the Group’s share is approximately $30 million, equivalent to 8 months gross rent. The guarantees can be applied against any unpaid rent and were put in place as a condition of the Group’s approval of Anchorage Capital Partners’ acquisition of David Jones in 2023. David Jones paid all rent up to 30 September 2026.
Capital management and balance sheet strength
Two transactions featured in the update. In late September, the Group settled the divestment of a 50.0% interest in Westfield Mt Gravatt, Brisbane, to joint venture partner Australian Retirement Trust for $882.5 million.
In October, the Group issued US$750 million (A$1,079 million) of 10-year guaranteed senior notes, marking a re-entry into the US bond market after six years. Obligations on the notes have been swapped to a floating rate A$ liability at a margin of 141 basis points over 3-month BBSW.
Available liquidity was $3.4 billion as at 31 October 2026, sufficient to cover all maturities until the second half of 2029.
Subject to no material change in conditions, the Group reaffirmed its target for FFO of at least 23.79 cents per security for 2026. Distributions are expected to grow by 4.25% to 18.473 cents per security.
What happens next for Scentre Group
Several milestones are scheduled across the development pipeline:
- Westfield Bondi: the Kingpin entertainment offer opens to the community in December. The remainder of the development, including dining experiences, opens progressively from 2027.
- Westfield Penrith: the entertainment and lifestyle precinct and HOYTS Cinemas complex opens progressively from Q2 2027.
- Westfield Tuggerah: TimeZone opens in Q2 2027.
- Westfield Eastgardens: the proposal continues to progress through the NSW Housing Delivery Authority as a State Significant Development.
Get Property News Before the Market Moves
Get FREE breaking ASX alerts delivered within minutes of release, with in-depth analysis already done. Join 20,000+ investors using Big News Blast to stay ahead on real estate and other non-resource sectors. Click the “Free Alerts” button to receive market-moving news the moment it breaks.