

ACCC blocks IAG’s bid for RAC Insurance
The Australian Competition and Consumer Commission (ACCC) has formally opposed Insurance Australia Group’s (ASX: IAG) proposed acquisition of RAC Insurance (RACI), following an in-depth Phase 2 assessment under the formal merger regime. The regulator determined that the deal would substantially lessen competition in both motor vehicle insurance and home and contents insurance in Western Australia.
IAG had proposed to acquire RACI from RACI Pty Ltd, a wholly owned subsidiary of the Royal Automobile Club of Western Australia Inc. If completed, the acquisition would have seen IAG underwrite motor and home and contents insurance under the RAC WA brand, significantly consolidating its presence in the state.
RACI is currently the market leader in both insurance categories in Western Australia, while IAG is one of Australia’s two largest personal insurers.
When big ASX news breaks, our subscribers know first
What the ACCC found, and why it matters for competition
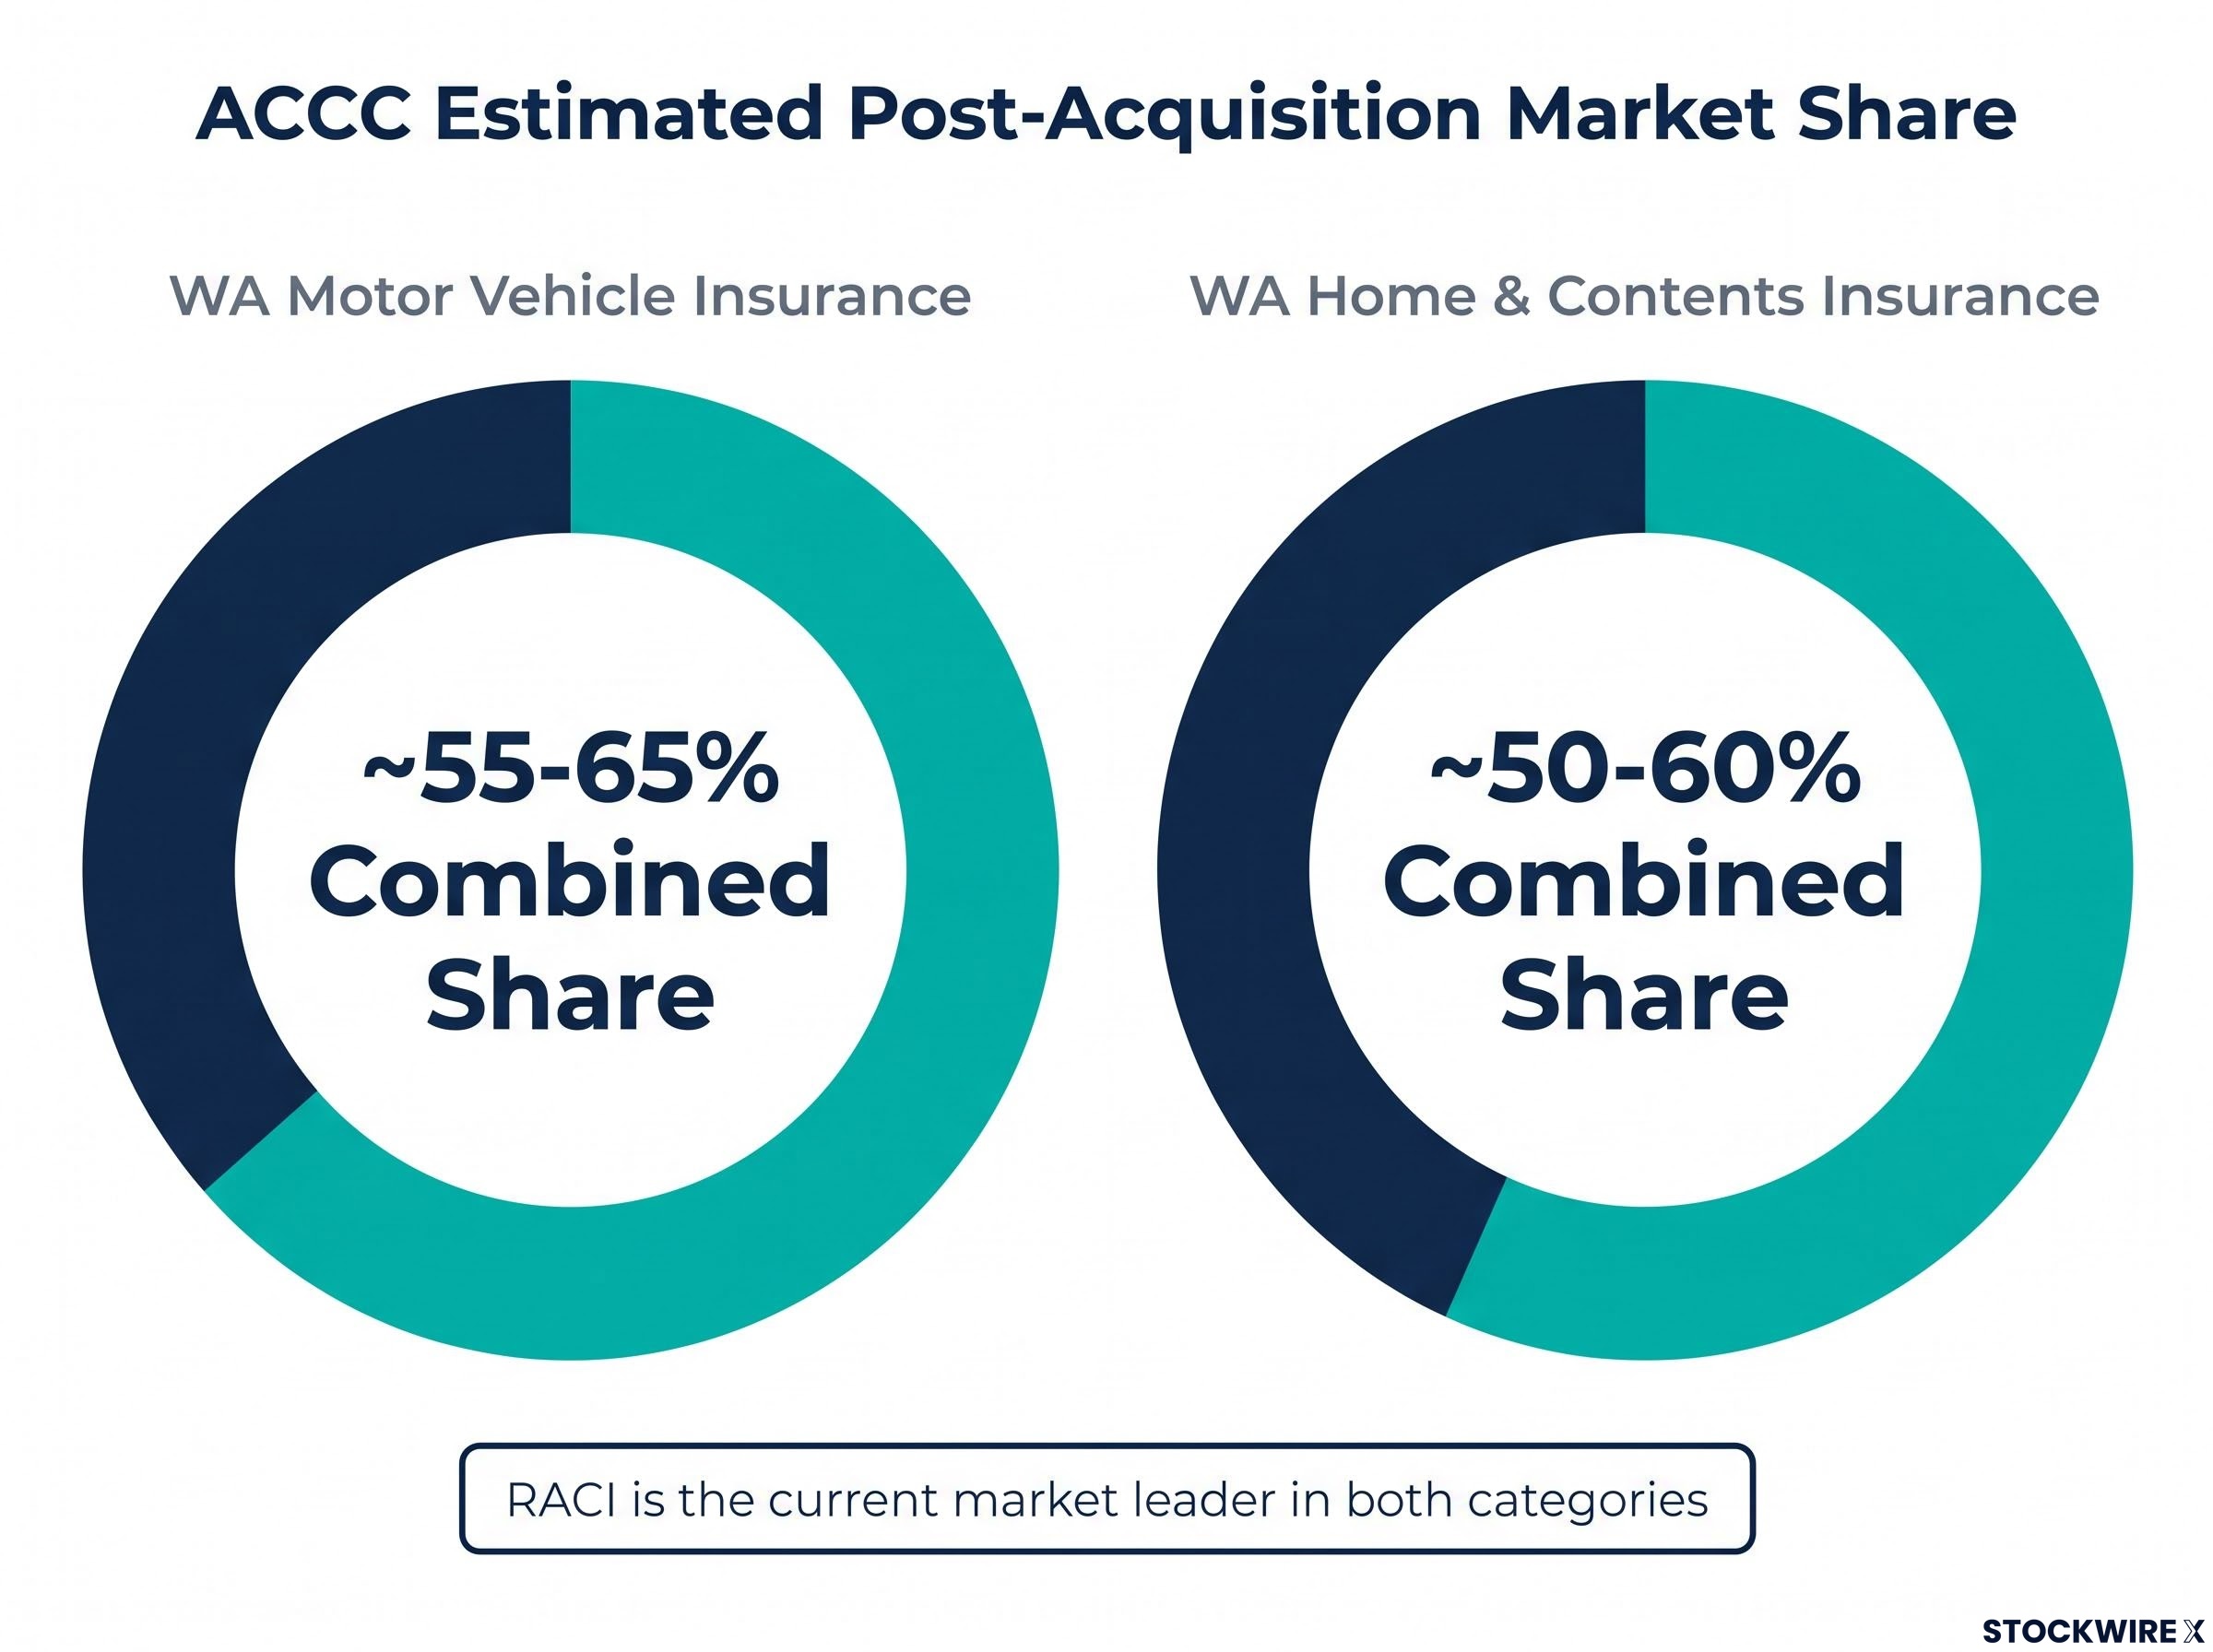
The ACCC’s Phase 2 assessment centred on the scale of market concentration the combined entity would create. The combined estimated market shares in Western Australia were a primary driver of the opposition.
Key findings from the assessment include:
- Post-acquisition WA motor vehicle insurance market share: approximately 55–65%
- Post-acquisition WA home and contents insurance market share: approximately 50–60%
- RACI is the current market leader in both categories in WA under the RAC WA brand
- IAG is described as one of Australia’s two largest personal insurers
ACCC Chair Gina Cass-Gottlieb
“The acquisition would combine two large insurers, resulting in a substantial increase in IAG’s market share and a significant increase in market concentration.”
The ACCC further found that remaining competitors in the WA market would be unlikely to provide sufficient constraint to offset the loss of competition arising from the deal.
The regulator did, however, draw a distinction on two specific concerns. It did not find sufficient evidence that IAG would have the incentive to restrict competing insurers’ access to repair services, and it also concluded there was insufficient evidence of a likely substantial lessening of competition in smash repair acquisition markets in certain WA regions.
| Segment | RACI current position | IAG current brands in WA | Combined estimated share | ACCC concern level |
|---|---|---|---|---|
| Motor vehicle insurance | Market leader | NRMA | ~55–65% | High |
| Home and contents insurance | Market leader | NRMA | ~50–60% | High |
Understanding merger clearance, and what comes next for IAG
Australia’s formal merger regime commenced on 1 January 2026, replacing the previous informal clearance process. Under the old regime, merging parties could seek informal guidance from the ACCC without a legislated process or binding determination. The new formal regime introduces structured notification requirements, defined assessment timelines, and binding regulatory decisions, giving the ACCC greater authority over significant transactions.
This acquisition has navigated both regimes. IAG first sought clearance under the informal regime in 2025, and the ACCC opposed it in December 2025 based on information available at that time. IAG then re-notified the proposed acquisition under the new formal regime in March 2026, triggering the Phase 2 assessment that has now concluded with a formal determination opposing the deal.
The ACCC Phase 2 review that preceded this formal determination had already flagged concerns about WA market concentration, with the regulator escalating its assessment after IAG re-notified under the new formal merger regime in March 2026.
The ACCC’s decision is not necessarily the final word. A “public benefit application” pathway remains available to IAG. Under this process, the parties may lodge an application asking the ACCC to weigh whether the public benefits of the acquisition outweigh the competitive detriment. For investors, this means the deal is blocked but not definitively closed.
The remaining process steps for IAG are:
- ACCC issues formal determination opposing acquisition
- IAG may lodge a public benefit application with the ACCC
- ACCC assesses whether public benefit outweighs competitive detriment
- ACCC determination issued within 50 business days (subject to extension)
Investment implications for IAG
The ACCC’s decision represents a strategic setback for IAG’s ambitions in Western Australia, though the scope of the lost opportunity should be understood clearly. IAG currently supplies home and motor insurance in WA primarily under the NRMA brand, having transitioned customers away from the SGIO brand from 2022. The proposed acquisition would have accelerated IAG’s WA presence materially, but IAG did not seek to acquire RAC’s roadside assistance, auto servicing and repair, finance, retirement living, or other ancillary operations. The blocked deal is therefore limited in scope to the insurance underwriting business.
Elsewhere in its state-based partnership strategy, IAG operates a joint venture with RACV in Victoria, where it underwrites RACV-branded home and contents and motor vehicle insurance. In 2025, it acquired RACQ Insurance in Queensland, demonstrating an ongoing strategy of deepening presence through aligned brand partnerships.
IAG’s Ambition 2030 strategy had explicitly incorporated the RAC Insurance acquisition as a key assumption underpinning targets of approximately 8 million retail customers and roughly $15 billion in Retail Insurance Australia gross written premium, making the blocked deal a material variable for those headline projections.
One notable aspect of the ACCC’s findings carries forward-looking significance for investors. The regulator explicitly assessed that organic competitive dynamics in WA favour IAG’s growth regardless of the acquisition outcome.
ACCC Chair Gina Cass-Gottlieb
“Our assessment is that IAG and RACI are effective competitors in Western Australia. The ACCC considers that IAG is likely to be a stronger competitor than it is presently if the acquisition does not proceed.”
This finding suggests the ACCC views IAG as well-positioned to grow its WA market share organically, independent of any acquisition. It also underscores why the ACCC regarded the proposed deal as particularly concentrated: both parties were seen as capable, strengthening competitors rather than one being a declining or marginal player.
No financial figures relating to the deal value or any share price impact have been disclosed by IAG or the ACCC in connection with this decision.
The full Phase 2 Determination is available on the ACCC’s Acquisitions Register under Insurance Australia Group – RAC Insurance.
Don’t Miss the Next Finance Sector Development
Big News Blast delivers FREE breaking ASX financial sector news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers who stay ahead of the market the moment announcements drop. Click the “Free Alerts” button at Big News Blast to start receiving alerts today.