
Inghams trims FY27 guidance top end as volumes grow 5.3%
Inghams Group Limited (ASX: ING) reported an in-principle agreement with Woolworths on a new long-term supply arrangement extending beyond 2030, while reducing the top end of its FY27 guidance by $10 million. The trading update covers the first 18 weeks of FY27, to 31 October, and is dated 12 November 2026.
Group core poultry volumes rose 5.3% versus the prior corresponding period (PCP). The headline points from the period were:
- Australian volumes: +4.8%
- New Zealand volumes: +8.0%
- Australian core poultry pricing: +1.9%
- New Zealand pricing: -0.8% in NZD terms
The guidance reduction applies to both Underlying EBITDA (pre AASB 16) and Underlying EBIT, and reflects higher costs and continued pressure on Australian Wholesale pricing.
Ed Alexander, CEO and Managing Director
“Demand for chicken remains resilient, supported by its affordability and versatility…”
“Our focus remains on converting volume growth into stronger and more sustainable earnings through operational and commercial excellence.”
When big ASX news breaks, our subscribers know first
Woolworths agreement extends the relationship beyond 2030
Inghams has reached an agreement in-principle on the key commercial terms of a new long-term supply arrangement with Woolworths, which would extend the relationship beyond 2030. The agreement is a proposed agreement, not yet final.
The company said the proposed agreement provides greater certainty for both companies, while supporting their shared focus on delivering quality, value and reliable supply to Australian consumers.
The commercial terms remain confidential. Alexander said: “…we are pleased with the agreed volumes and key terms, which provide a strong foundation for our ongoing partnership.”
Retail drives growth while Wholesale pricing weighs
Retail was the main driver of volume growth, while demand through out-of-home channels was generally softer, which management attributed to cost-of-living pressures.
Australian Wholesale pricing declined 8.3% versus PCP. The anticipated recovery in this channel has been slower than expected, reflecting softer out-of-home demand and changes in customer supply arrangements that have contributed to excess market supply. Inghams has reduced its exposure to the channel, though weaker Wholesale pricing continues to weigh on FY27 earnings.
In New Zealand, pricing declined 0.8% in local currency and 9.6% in Australian dollar terms, reflecting foreign exchange movements.
Why Wholesale pricing matters
Wholesale is the channel through which a poultry producer sells product to food service and other out-of-home customers rather than to supermarkets. When Wholesale prices fall, the average price the producer receives can drop even if volumes rise.
Average pricing also moves with channel and product mix, meaning the share of sales going to each channel and product type. Inghams said Australian price growth of 1.9% reflected channel and product mix, and the reduced Wholesale exposure is part of that picture.
Operational costs absorbed year to date
The business has absorbed additional costs from several operational impacts:
- Commissioning of automation upgrades at Osborne Park
- The move to fixed-weight retail products
- The addition of substantial new retail volumes
- Temporary operational disruptions at the Queensland primary processing facility
Inghams expects efficiency to improve progressively over the remainder of FY27, with initiatives implemented to address these costs.
The efficiency recovery sits within the broader Stabilise, Optimise, Grow strategy that management outlined at its May 2026 Investor Day, where processing yield gains and automation were presented as early proof points of the first phase.
Revised FY27 guidance and cost assumptions
The operating environment has been marked by higher inflation across feed, labour, energy, fuel and freight, packaging and ingredients, alongside ongoing geopolitical disruption. Feed cost increases to date are broadly in line with the outlook provided with the FY26 results in August.
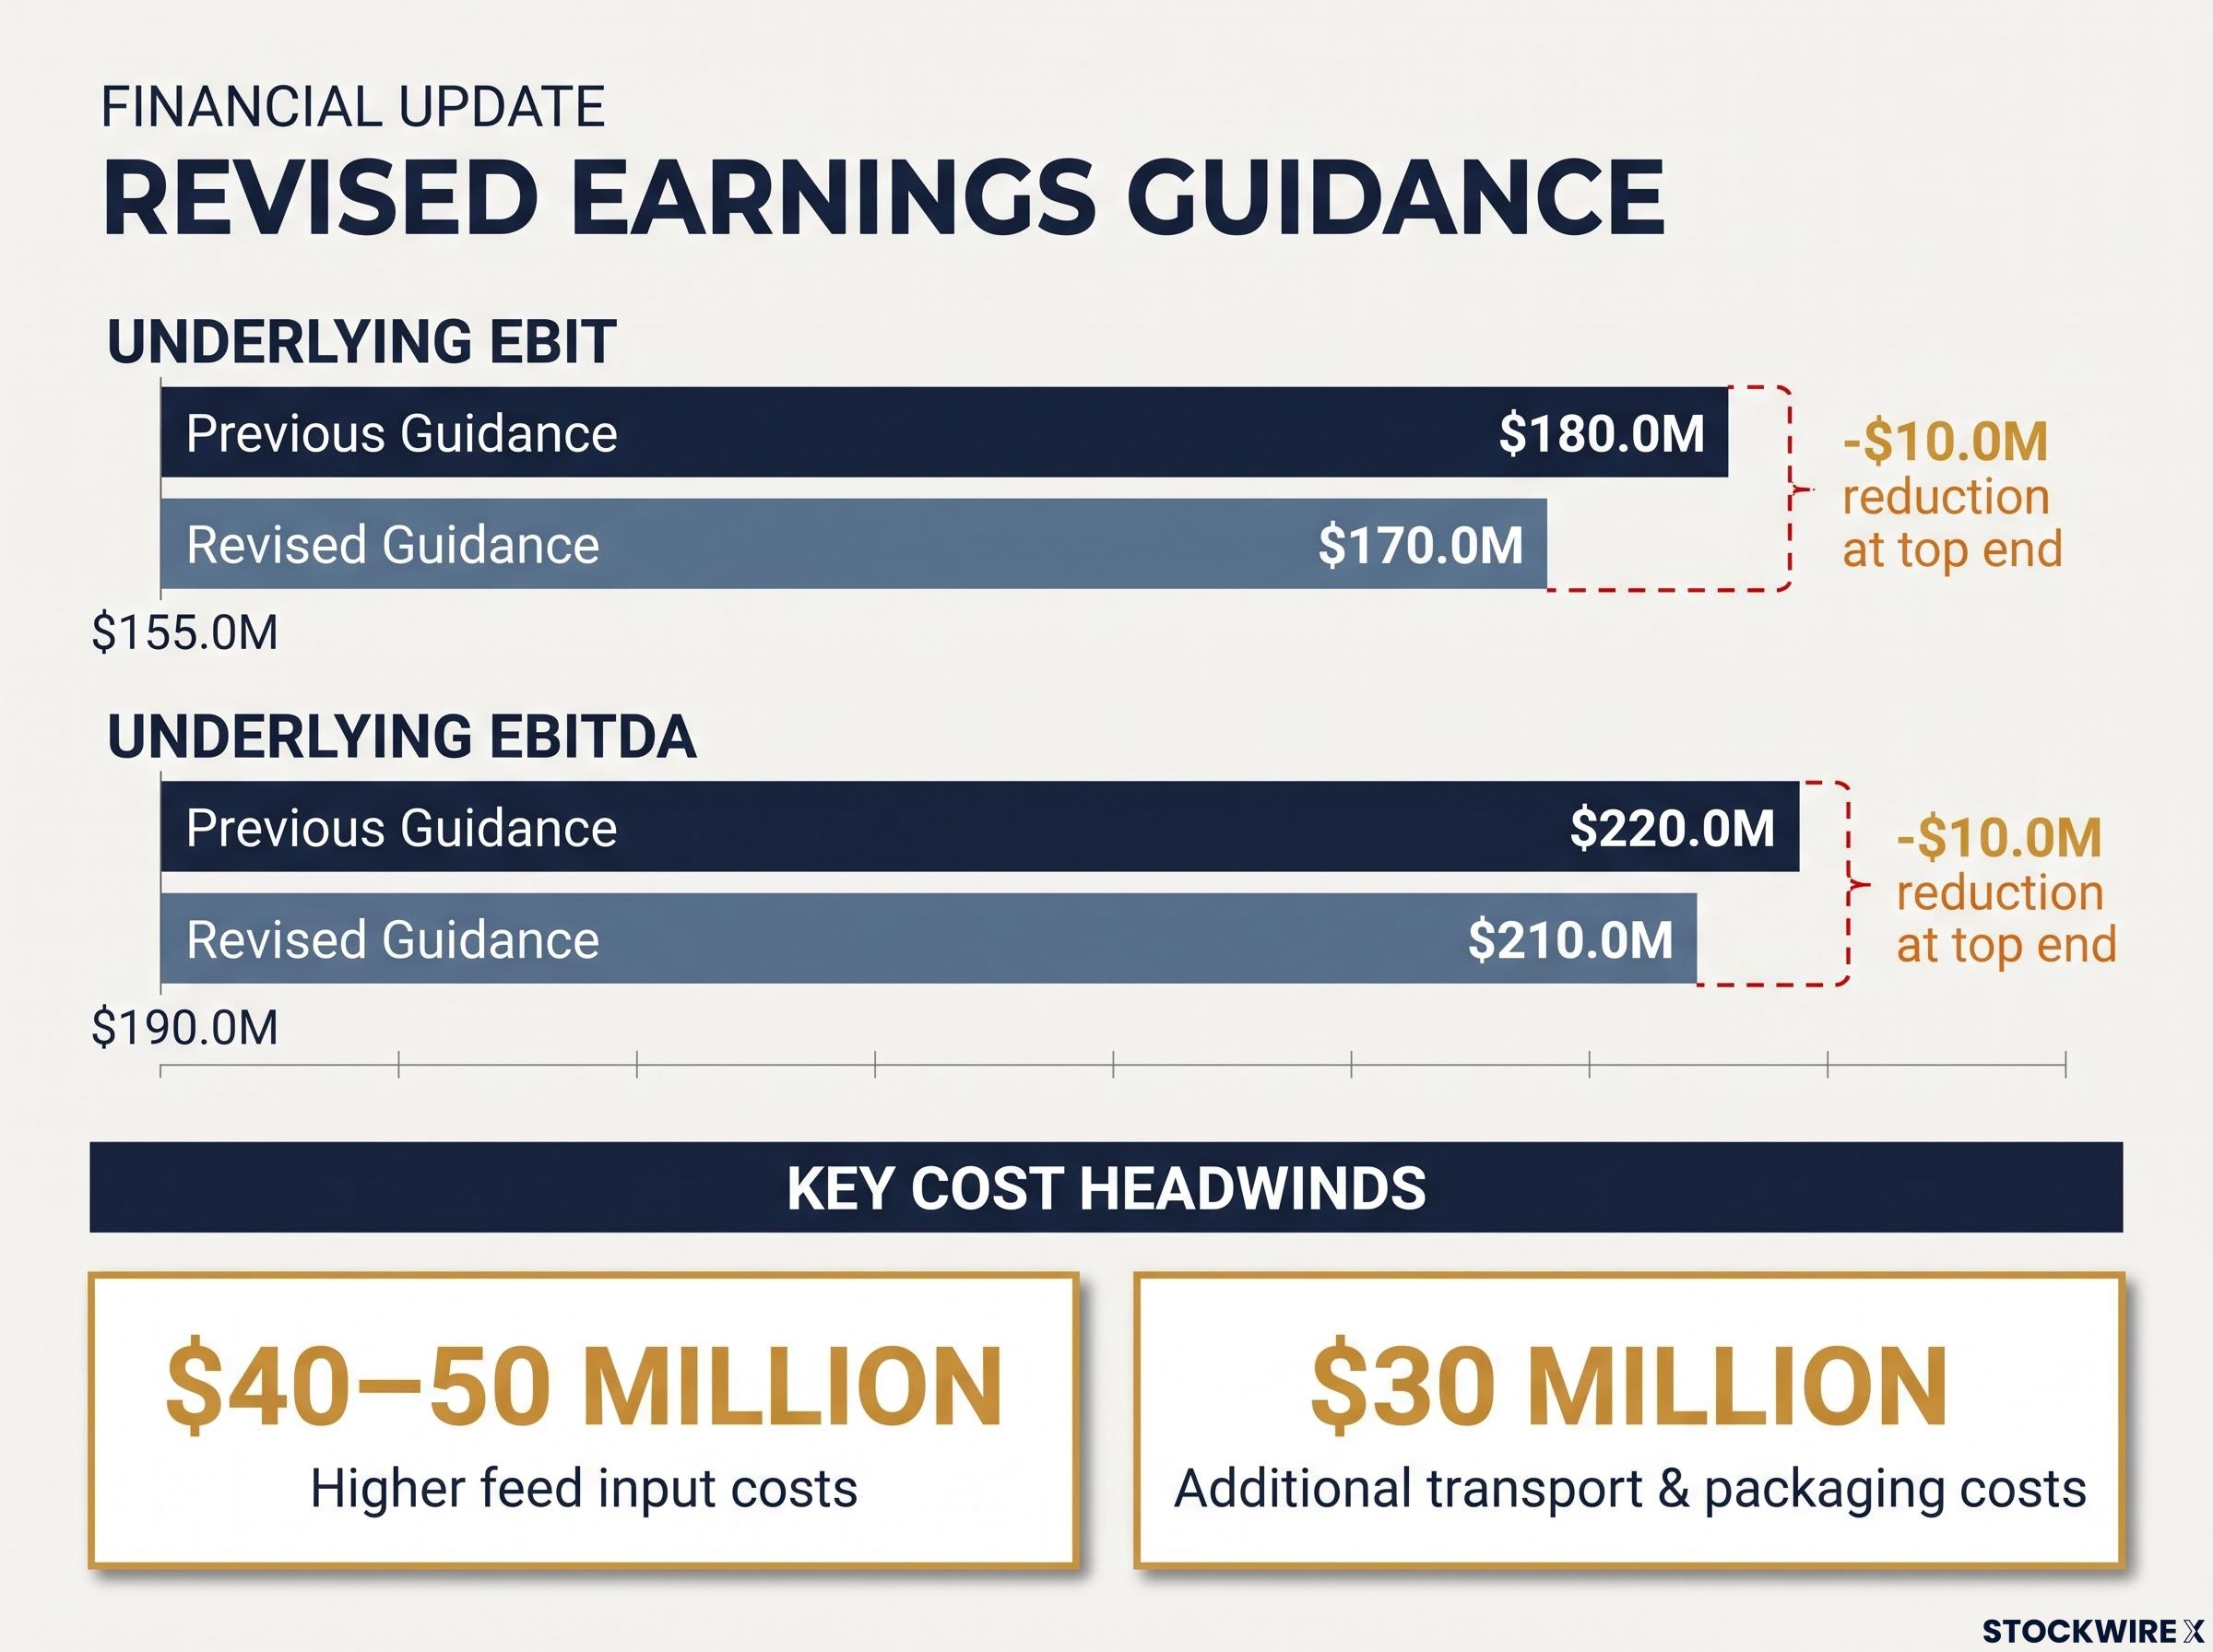
The revised ranges leave the lower end of both measures unchanged.
| Metric | Previous range | Revised range |
|---|---|---|
| Underlying EBIT (post AASB 16) | $155.0 million to $180.0 million | $155.0 million to $170.0 million |
| Underlying EBITDA (pre AASB 16) | $190.0 million to $220.0 million | $190.0 million to $210.0 million |
The updated FY27 guidance assumes:
- Core poultry volume growth of 2.5-4.0%.
- Operating cost growth (excluding feed) of 4-5%, including forecast volume growth, to be significantly offset through pricing (including some feed cost recovery), continuous improvement and procurement initiatives.
- $30 million of additional transport and packaging costs associated with the Middle East conflict.
- $40-50 million of higher feed input costs, based on current market conditions and expected volumes.
- Progressive recovery in Wholesale pricing through to the end of FY27.
- Capital expenditure of $80 million.
Inghams continues to expect core volumes and net selling prices to be higher than last year. FY27 earnings performance is expected to be significantly weighted to the second half.
Want Alerts Like This on the Consumer Staples Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.