
PEXA’s 1Q27 trading update: volumes fall 11.5% and FY27 guidance is cut
In its 1Q27 trading update for the quarter ended 30 September 2026, PEXA Group (ASX: PXA) reported total PEXA Exchange transaction volumes of 934k, a decrease of 11.5% on the prior comparative period (PCP or 1Q26). The company also updated its FY27 guidance, with Group Revenue now $355m-$380m, down from the prior $385m-$415m.
Chief Executive Officer and Group Managing Director Russell Cohen said Australian Exchange customer satisfaction remained broadly stable at approximately 90%, in line with historical levels, against a backdrop of a significant decline in Australian property transaction market activity.
Russell Cohen, PEXA CEO and Group Managing Director
“PEXA’s platform remains resilient and we continue to invest in the strength and security of our network…”
Cohen added that the company was maintaining disciplined cost control while protecting the integrity of its platform and customer operations, and the strategic direction of the business.
When big ASX news breaks, our subscribers know first
Australian Exchange performance
Consecutive interest rate rises and falling property prices weighed on buyer confidence and transfer volumes, according to the CEO. Transfer volumes fell the most of the three transaction types.
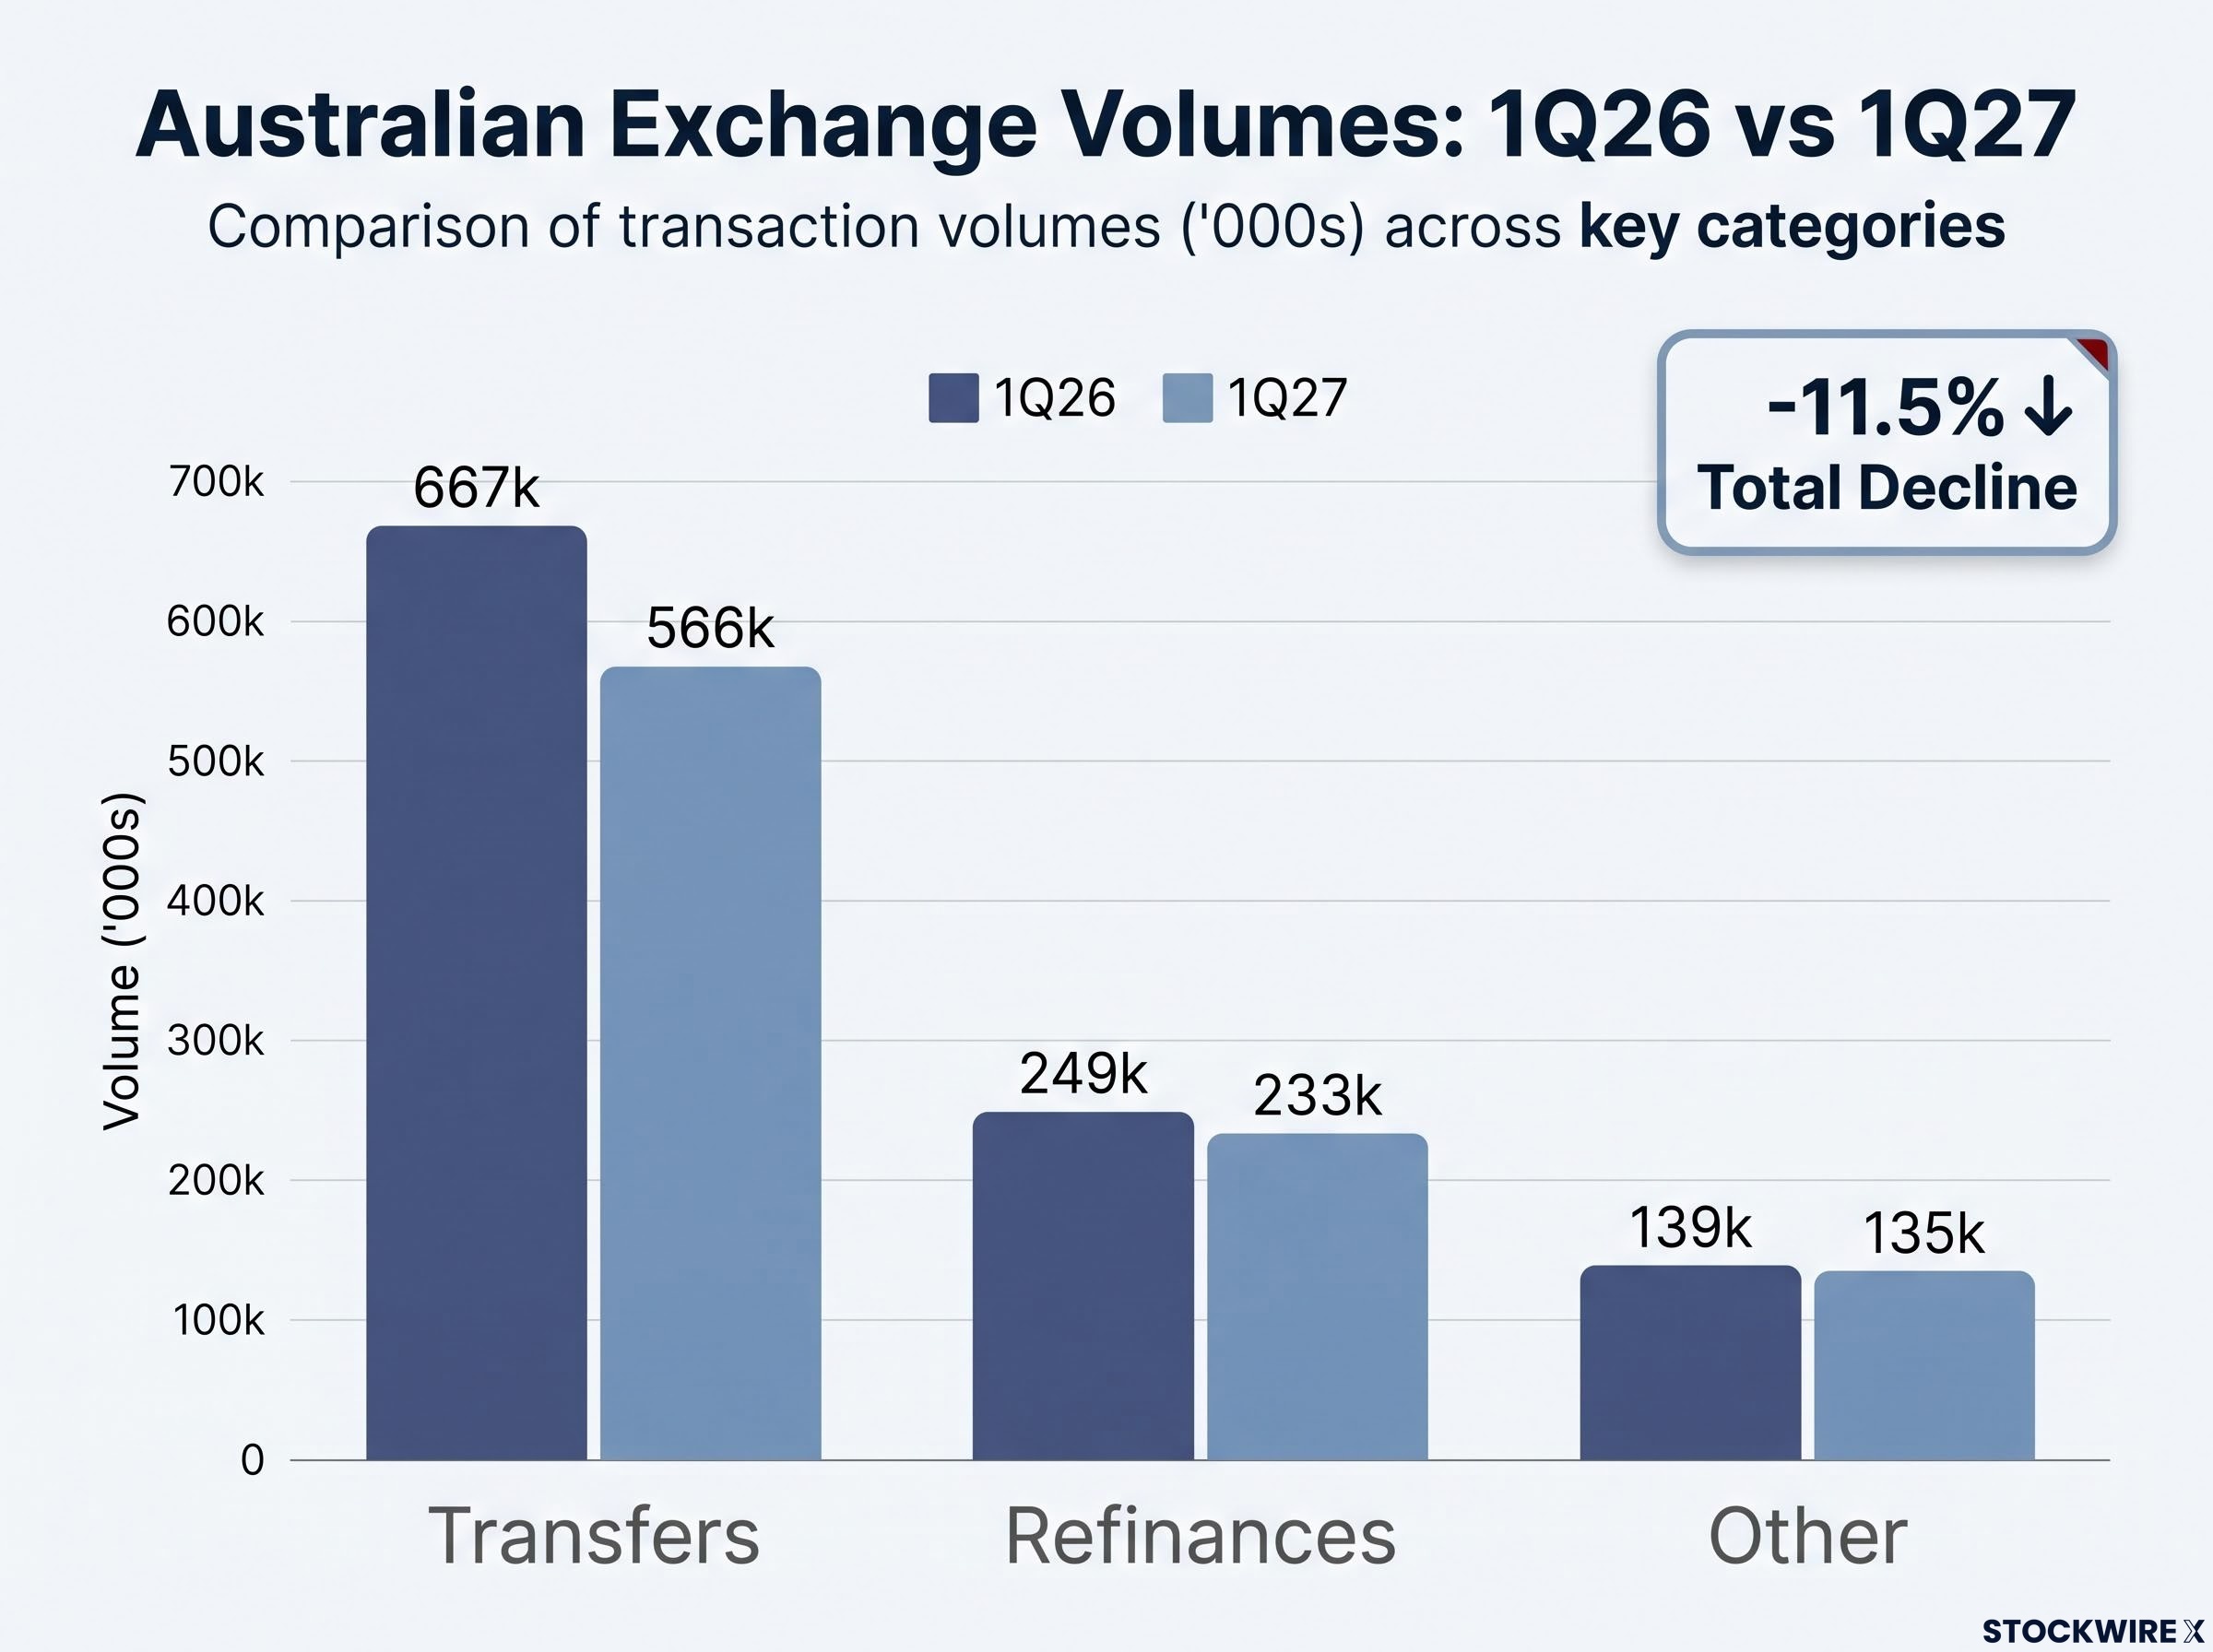
Volumes by transaction type
| Transaction type | 1Q26 | 1Q27 | Change |
|---|---|---|---|
| Transfers | 667k | 566k | (15.2%) |
| Refinances | 249k | 233k | (6.4%) |
| Other | 139k | 135k | (3.2%) |
| Total | 1,055k | 934k | (11.5%) |
Refinance activity accounted for 25% of volumes, up 1% versus the PCP.
Network and product progress
The company reported the following network and product updates for the quarter:
- Total national market penetration was 90%, consistent with 2H26.
- The Exchange customer satisfaction score was 89.1% in 1Q27, compared with 89.8% in 4Q26.
- Tasmanian volumes increased incrementally alongside the removal of paper titles from Land Titles Office processes on 1 September.
- PEXA launched remortgage capabilities in the Northern Territory in 2025, with transfer capabilities scheduled to launch in the week of 9 November 2026.
- PEXA Clear continued to onboard customers and commenced monetisation in Q1, following the commencement of new Anti-Money Laundering and Counter-Terrorism Financing requirements on 1 July 2026. PEXA took a paced onboarding approach.
UK expansion: NatWest and remortgage volumes
NatWest continues to process remortgage transactions on PEXA’s UK platform, with a significant increase in transaction speeds and improved customer satisfaction scores reported. Implementation of NatWest Sale & Purchase transactions commenced during the quarter.
The CEO said PEXA expects to process its first Sale and Purchase transaction with NatWest in March 2027.
| Metric | 1Q26 | 1Q27 | Change |
|---|---|---|---|
| Optima Legal remortgage completions | 13.7k | 15.4k | 12.7% |
| Smoove remortgage completions | 9.0k | 7.4k | (17.8%) |
| Smoove Sale and Purchase completions | 5.4k | 5.3k | (1.2%) |
Optima Legal remortgage completions grew 13% on the PCP as customers sought to lock in new rates ahead of expected interest rate rises. Smoove remortgage completions fell 18% due to a slowdown in volumes received from a panel lender.
Updated FY27 guidance and cost discipline
Consecutive interest rate rises, tax changes and a decline in property prices continue to impact transfer volumes. In October 2026, transfer volumes were 26% lower than the PCP, whilst remortgage volumes were broadly flat.
To reduce the impact of anticipated lower transfer volumes on margins, the Group continues to focus on disciplined cost control and capital allocation. Group EBITDA margin has moved broadly in line with the scenarios presented at the FY26 results.
The FY26 results showed a return to statutory profit and a net debt to EBITDA ratio of 1.0x, which gives the balance sheet some room to absorb weaker volumes.
The updated guidance reflects the company’s current FY27 transaction volume expectations and target Group EBITDA margin range.
| Metric | Prior FY27 guidance | Updated FY27 guidance |
|---|---|---|
| Group Revenue | $385m-$415m | $355m-$380m |
| Group EBITDA margin | 31.5%-33.5% | 29.0%-31.5% |
| Group Core NPAT continuing operations | $5m-$20m | ($6m)-$6m |
| Group Capex | ($45m-$55m) | ($45m-$50m) |
| International operating cash flow | ($55m-$65m) | ($55m-$65m) |
Core NPAT represents financial results from core operations, reported results adjusted for significant non-recurring items.
What happens next for PEXA
The update points to the following dated events:
- Northern Territory transfer capabilities are scheduled to launch in the week of 9 November 2026.
- The NSW Government is to release the IPART final report on ELNO service fees, which will be made public by 18 November 2026. IPART submitted the report to the NSW Premier on 30 October 2026.
- ARNECC will then review the report and commence its process to determine whether any changes to PEXA’s prices are required, and if so, to what extent.
- The first NatWest Sale & Purchase transaction on PEXA is expected in March 2027.
The IPART draft fee proposal put a roughly 20% cut to regulated revenue on the table, and PEXA’s push for a four-year phase-in rather than a single-year reduction will shape how much of that lands in any one period.
PEXA will continue to work closely with ARNECC and other relevant stakeholders to advocate for an appropriate outcome for customers, shareholders and employees.
Want Alerts Like This on the Property Technology Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.