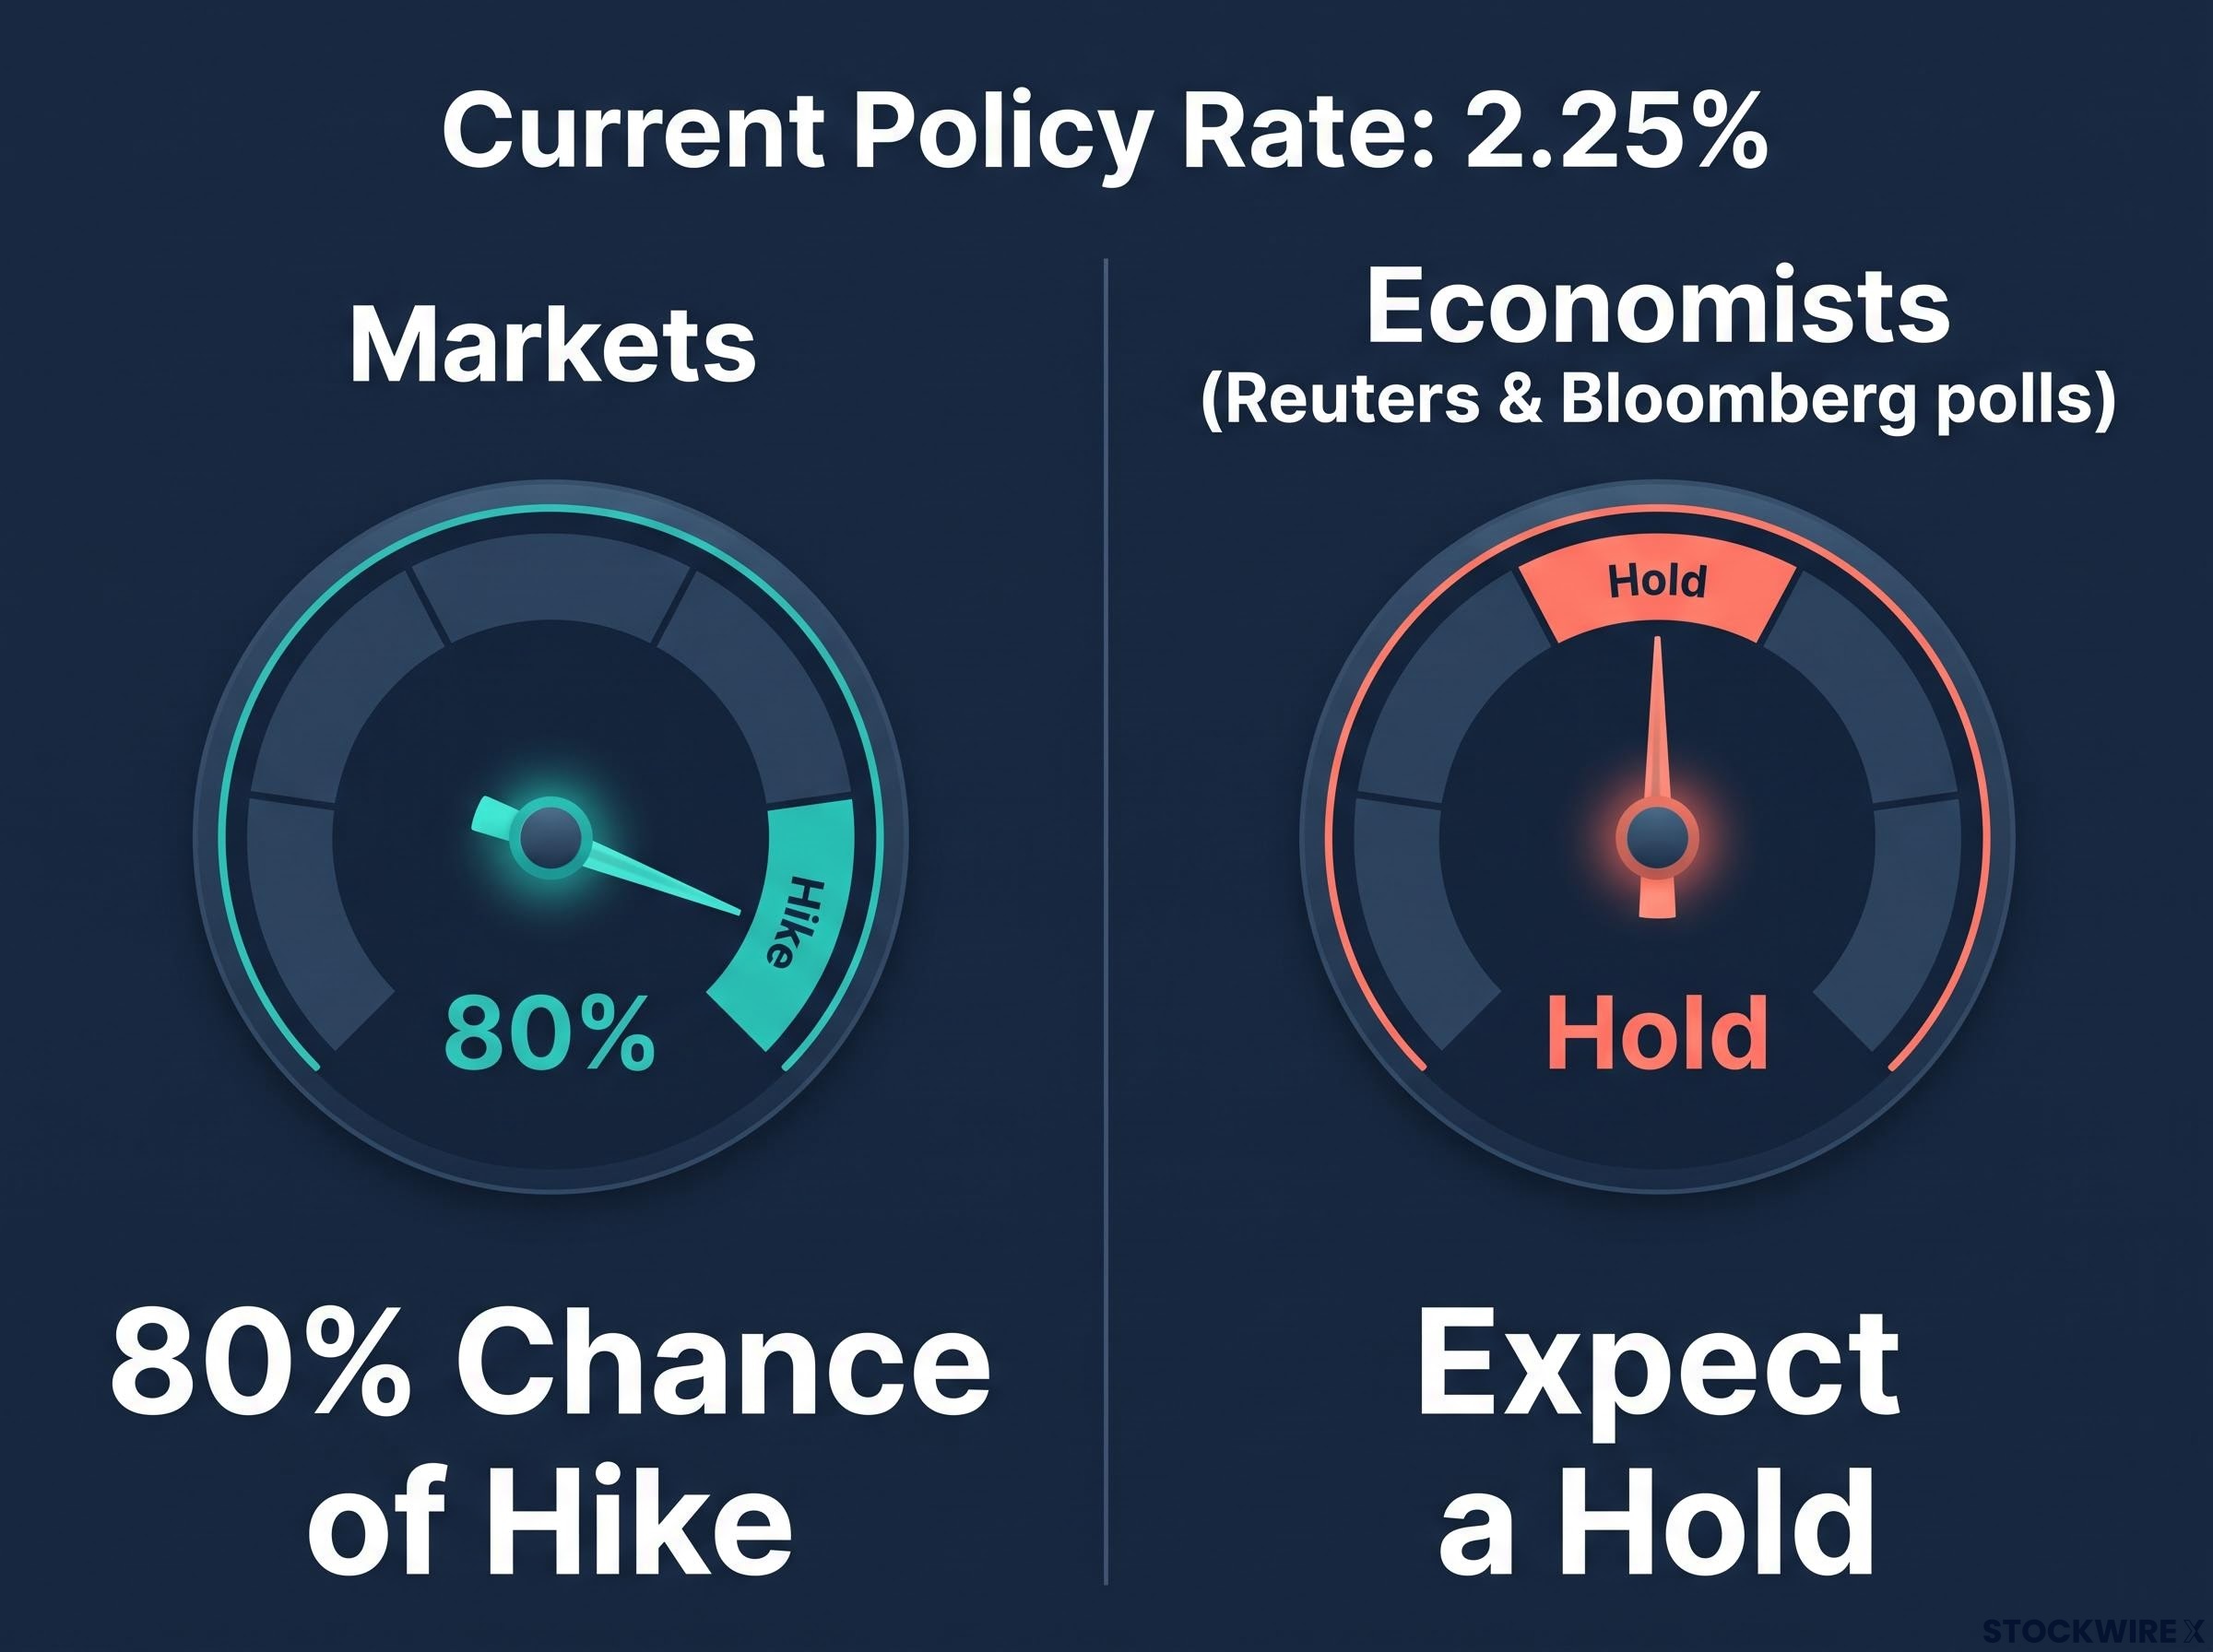
Markets now price roughly an 80% chance that the Bank of Canada raises rates on 28 October 2026, yet most economists polled by Reuters and Bloomberg still expect a hold. That gap between traders and forecasters is the signal in the coming Bank of Canada rate decision, and it is easy to miss.
The policy rate has sat at 2.25% for about a year, including a hold in September. The Bank’s Q3 Business Outlook Survey arrived yesterday, and the decision is now eight days away.
The stakes are personal. A hike would lift variable-rate payments, firm up fixed mortgage quotes for anyone renewing, and nudge savings returns higher. A hold would give stretched borrowers more time but leave the inflation question open.
Here is why the Bank is genuinely torn, what RBC‘s base case of no hikes until 2027 assumes, and which signals could pull a move forward.
Why is the case for holding rates still strong?
Start with the labour market. Hiring intentions in the Q3 survey are soft and below their historical average, with most firms planning to keep headcount flat. Investment intentions eased slightly but remain above historical norms.
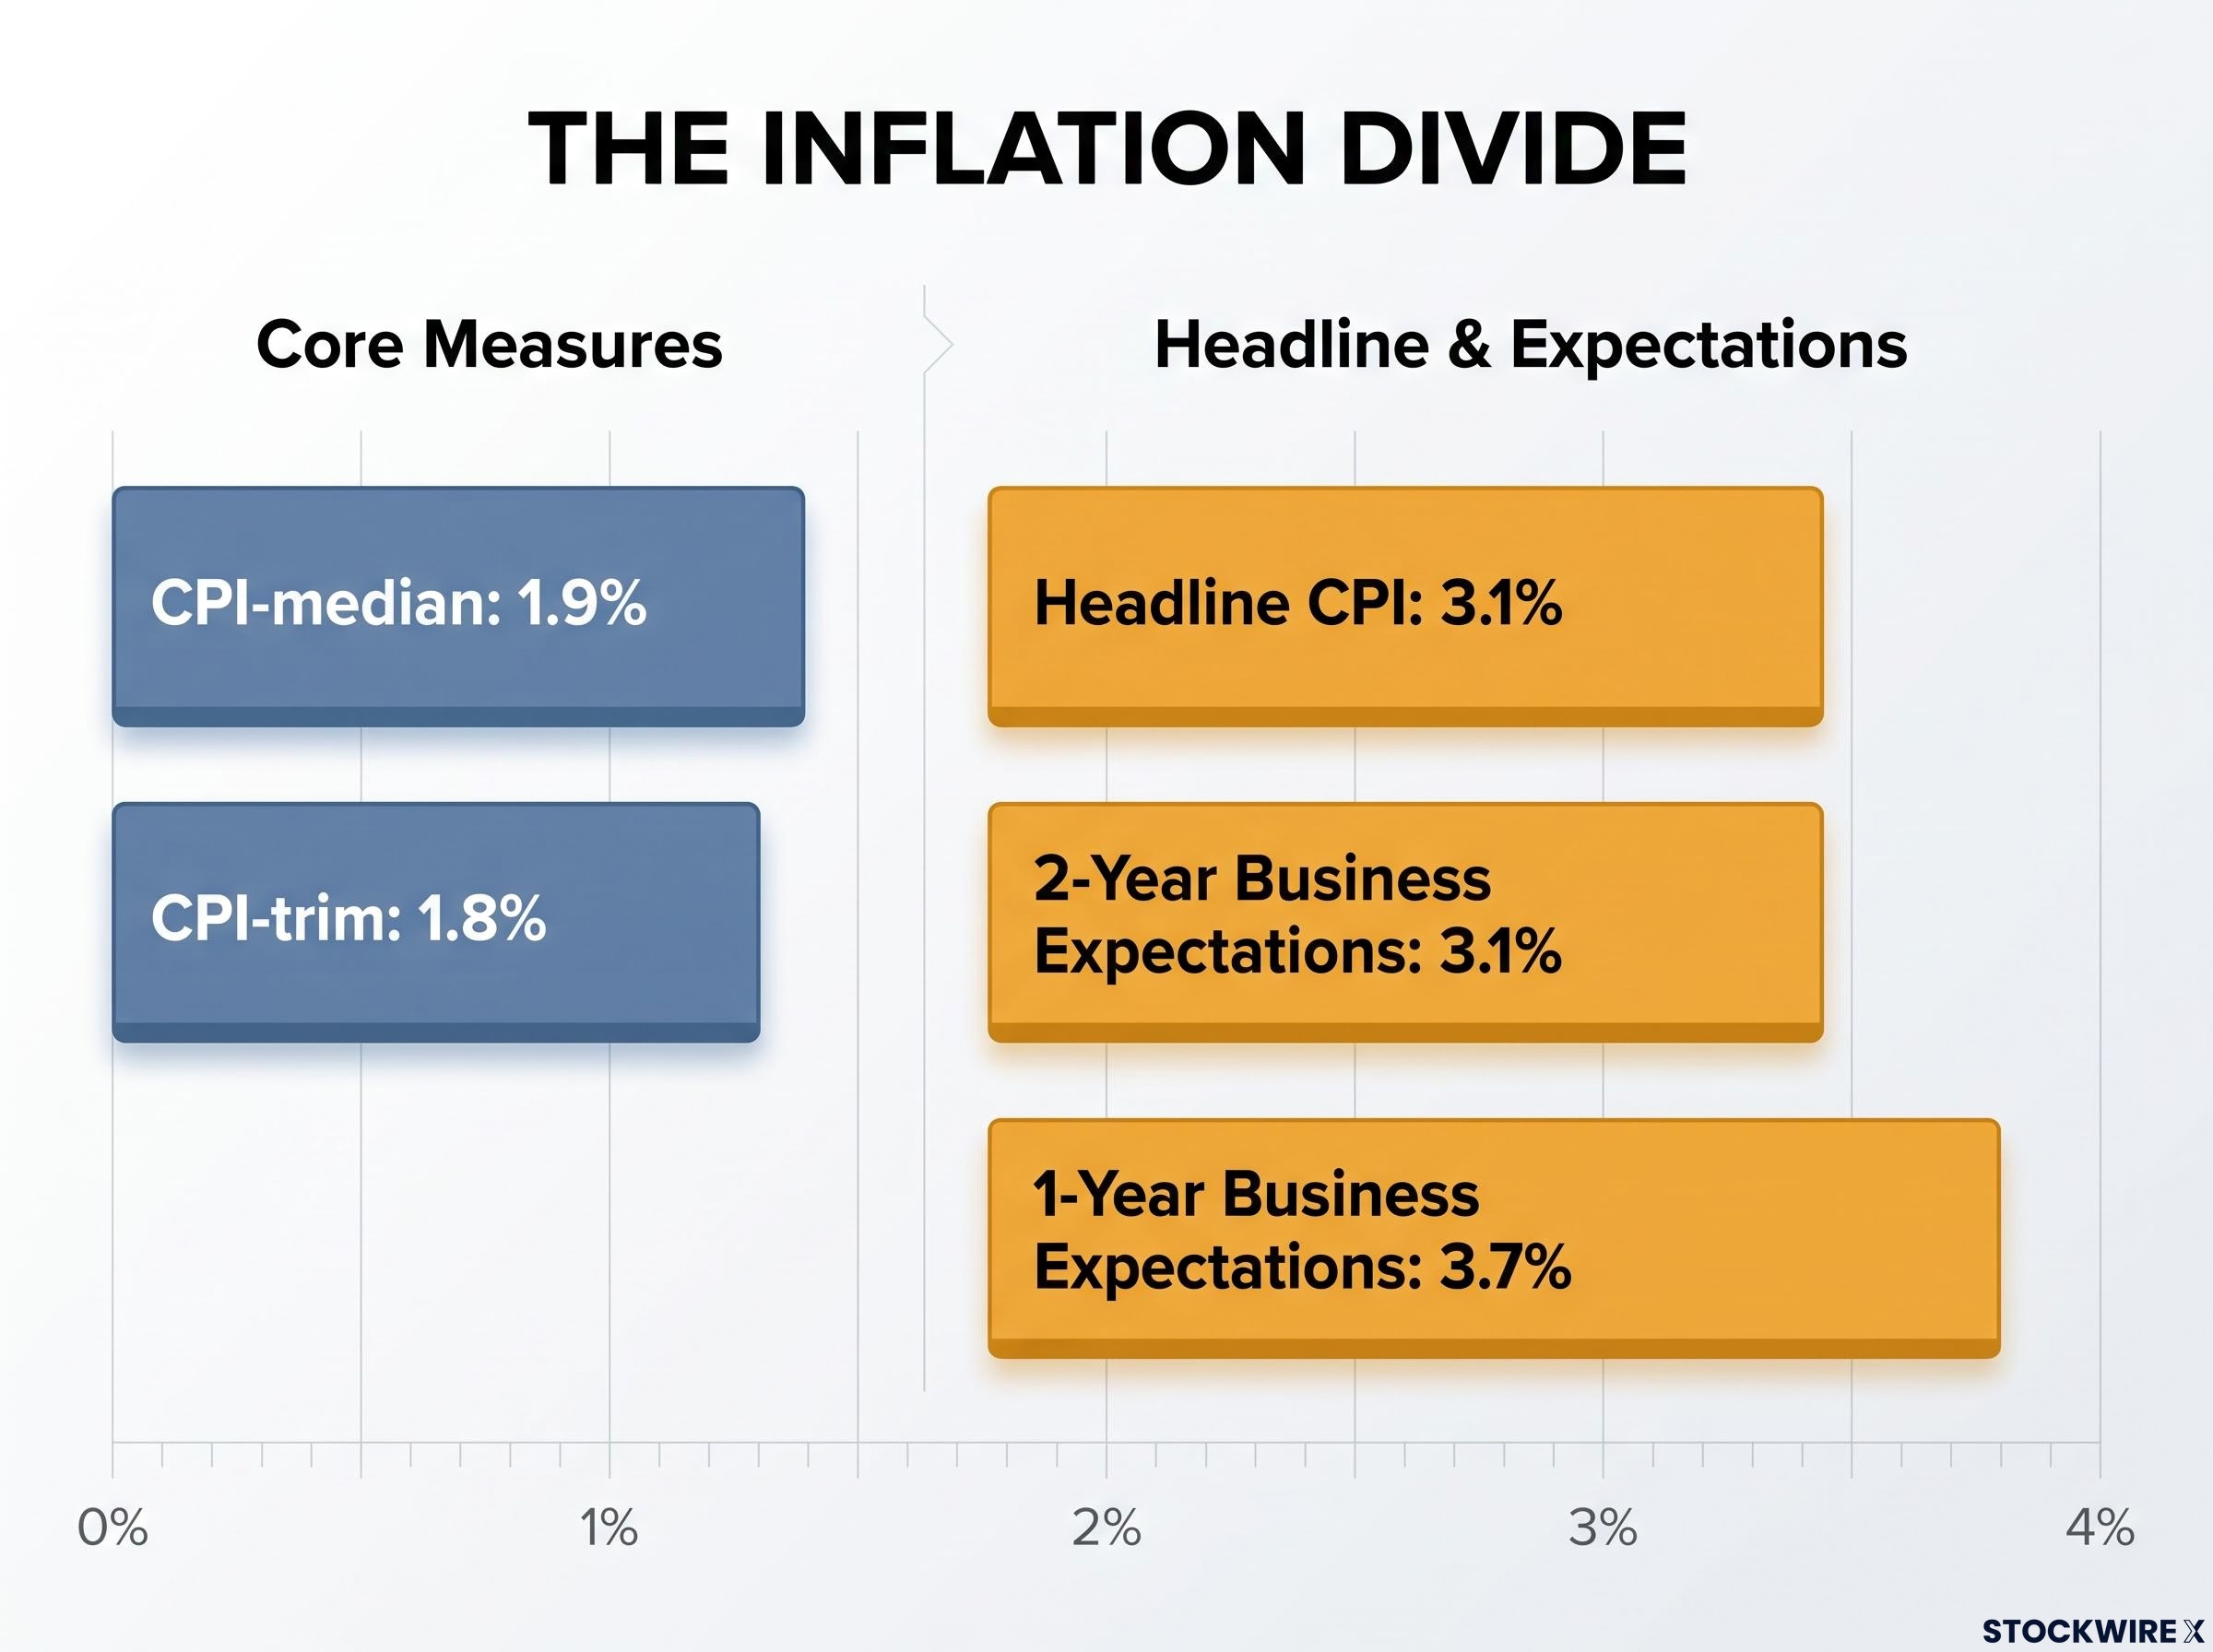
Core inflation sits close to target. September CPI-median came in at 1.9% and CPI-trim at 1.8%, according to Statistics Canada data reported by Reuters. CPI-median and CPI-trim are the Bank’s preferred core measures; they strip out the most extreme price moves to show underlying inflation.
Bond markets have also done some tightening already. Bank of Canada data shows the 2-year Government of Canada yield at 3.21% and the 10-year at 3.84% on 16 October (Trading Economics showed 3.96% on 19 October, though the Bank’s series is the primary source).
| Indicator | Latest reading | What it signals |
|---|---|---|
| Future-sales balance of opinion | +42 (from +15 in Q2) | Improvement, mostly recorded before the trade breakdown |
| Hiring intentions | Below historical average | Little labour market cushion for a hike |
| CPI-median / CPI-trim | 1.9% / 1.8% | Underlying inflation at or below target |
| 2-year / 10-year yield | 3.21% / 3.84% | Borrowing costs already higher without a policy move |
Weak hiring plus core inflation at or below 2% tells you a hike would land on households and firms with little room to absorb it. That is why many economists see waiting as the lower-regret move, and why variable-rate and renewing borrowers have reason to hope for patience.
History adds weight. The Bank hiked through 2018, then held from October 2018 as trade uncertainty intensified.
Why the survey timing matters
Timing caveat Roughly three-quarters of Q3 survey interviews took place before Canada-U.S. trade talks collapsed on 21 August 2026.
Since then, the U.S. has imposed 50% tariffs on about US$20 billion of Canadian goods, and Canadian counter-tariffs took effect from 8 September. Firms interviewed after the breakdown reported weaker sentiment and export expectations, so the headline improvement overstates current conditions.
That cuts both ways. The economy is likely softer than the +42 figure suggests, which strengthens the cautious case, but the survey is also a weaker guide to where things stand now.
When big ASX news breaks, our subscribers know first
What is pushing the Bank toward acting sooner?
Governor Tiff Macklem changed the conversation in Bangkok.
“Quite a bit higher” is how Macklem described the Bank’s coming inflation revision relative to its July outlook, speaking at the IMF and World Bank meetings.
He added that if oil stays near US$100 per barrel, inflation could drift gradually toward 3%. He then posed the question that matters: does inflation return to target on its own, or are higher rates needed to get it there?
Headline CPI already ran at 3.1% year-on-year in September, well above core measures near 1.9%. Taken alone, that gap looks like an energy story the Bank can tolerate.
Business expectations complicate it. RBC Economics reports one-year business inflation expectations at 3.7% in September and two-year expectations at 3.1%. 41% of firms expect inflation above 3% over two years, down from 44% in Q2 but still elevated.
That is where the worry sits. Calm core CPI matters less if firms are already planning price increases around a higher number.
Markets repriced fast. Odds of a 25 basis point October hike rose to about 75%-80%, from roughly 30%-35% before Macklem spoke and the CPI print landed (some intraday reports reached 87%, though about 80% is the figure more consistently reported).
That jump tells you traders now treat Macklem’s reaction function, meaning how he responds to incoming data, as the key variable. A hold on 28 October would be a genuine surprise rather than the default.
Our earlier report on how the Bank of Canada rate hike odds doubled after Macklem’s signal traces the repricing in more detail, including what moved the market first.
Where the forecasters split
| Institution | Stance | Timing |
|---|---|---|
| BMO (Douglas Porter) | Moved toward a hike call | Pre-emptive action favoured |
| Desjardins (Randall Bartlett) | Reportedly switched to hike | October |
| CIBC | Hikes brought forward | 2.50% in Q1 2027 |
| KPMG | Hold in October | Hike possible in December |
| TD Economics | Hold | 2.25% through 2028 |
| Scotiabank | Hawkish | 3.25% by Q2 2027 |
For you, this map shows how much tightening may already sit in bond yields and fixed mortgage rates. Much of an October hike is priced in; a hold is not.
How can weak growth and rising inflation expectations coexist?
It seems contradictory. If hiring is soft and the economy is fragile, how can prices still threaten to run hot?
The answer is that some shocks raise costs and cut demand at the same time. Four channels are doing that work in Canada now:
- Tariff pass-through: The Bank’s earlier analysis reportedly assumed about 75% of tariff costs pass through to consumer prices within six quarters, making the effect slow but persistent.
- Energy: Higher oil lifts fuel, transport and production costs while squeezing household budgets.
- Bond yields: Higher yields raise some fixed mortgage and corporate borrowing rates before the overnight rate moves.
- Mortgage renewals: Borrowers rolling off pandemic-era lows face larger payments and trim discretionary spending.
The Bank has seen this before. In July 2019 it assessed that tariffs could reduce global GDP by 0.6% by end-2021, treating them as both a cost shock and an uncertainty shock.
Look through or lean against?
Central banks generally look through one-off price jumps, meaning they let them pass without raising rates, as long as inflation expectations stay anchored. They tighten if the shock spreads into wages, services and expectations.
The dovish reading sees a relative price shock, a single jump in some prices that weak demand will contain. The hawkish reading sees repeated price resets and rising expectations entrenching it. The Q3 survey supports both: core CPI is near target, yet expectations are firm and many firms plan to pass on costs.
Why bond yields matter
This is the crux of the “need to hike less” argument. If markets have already pushed borrowing costs up, the Bank may get tightening for free, though that same squeeze weighs on housing, investment and spending.
The upshot is that higher prices at the checkout and weaker job security can arrive together. The Bank’s choice between those two risks directly shapes your mortgage and borrowing costs.
What does RBC’s base case mean, and why do risks lean earlier?
RBC economists Claire Fan and Abbey Xu expect a cautious Bank.
RBC base case Hold through the rest of 2026, with gradual hikes beginning in 2027. Risks lean toward earlier action, possibly at next week’s meeting.
Their reasoning rests on the fragile recovery and tighter financial conditions offsetting inflation risks. Soft core CPI and limited broad pass-through of energy costs argue against hurrying, and a separate consumer survey points to weaker spending intentions ahead.
Yet the base case is not sturdy. It sits against roughly 80% market pricing for an October hike, while the Reuters and Bloomberg consensus still leans to a hold.
The trade-off is insurance versus damage. Waiting could force sharper tightening later if expectations drift; hiking now could lock in economic harm if the shock fades on its own.
These signals would decide which way it breaks:
- Wages and services prices: Evidence of energy and tariff costs spreading here would bring a hike forward.
- Business inflation expectations: Further firming above 3.7% would strengthen the insurance case.
- Post-breakdown data: Weak hiring and spending after 21 August would support delay.
- Bond yields: A further rise would do more of the Bank’s work and reduce pressure to act.
For you, this means planning around a hold as the central scenario while treating 28 October as a live risk for variable-rate payments and fixed-rate quotes.
What the decision changes, and what it does not
The October call is asymmetric. Core inflation and weak hiring argue for patience, while Macklem’s communication, energy prices and business expectations argue for insurance tightening.
Whichever way the Bank moves, RBC’s broader path of gradual tightening from 2027 and a data-dependent framework remain the anchor. A hike would bring that path forward; a hold would not remove it.
Your watchlist is short: core CPI, hiring, post-breakdown survey data and bond yields. Note that figures cited are as reported and not independently confirmed.
These statements are speculative and subject to change based on market developments. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.