

Strong start to FY27 puts Data#3 well ahead of expectations
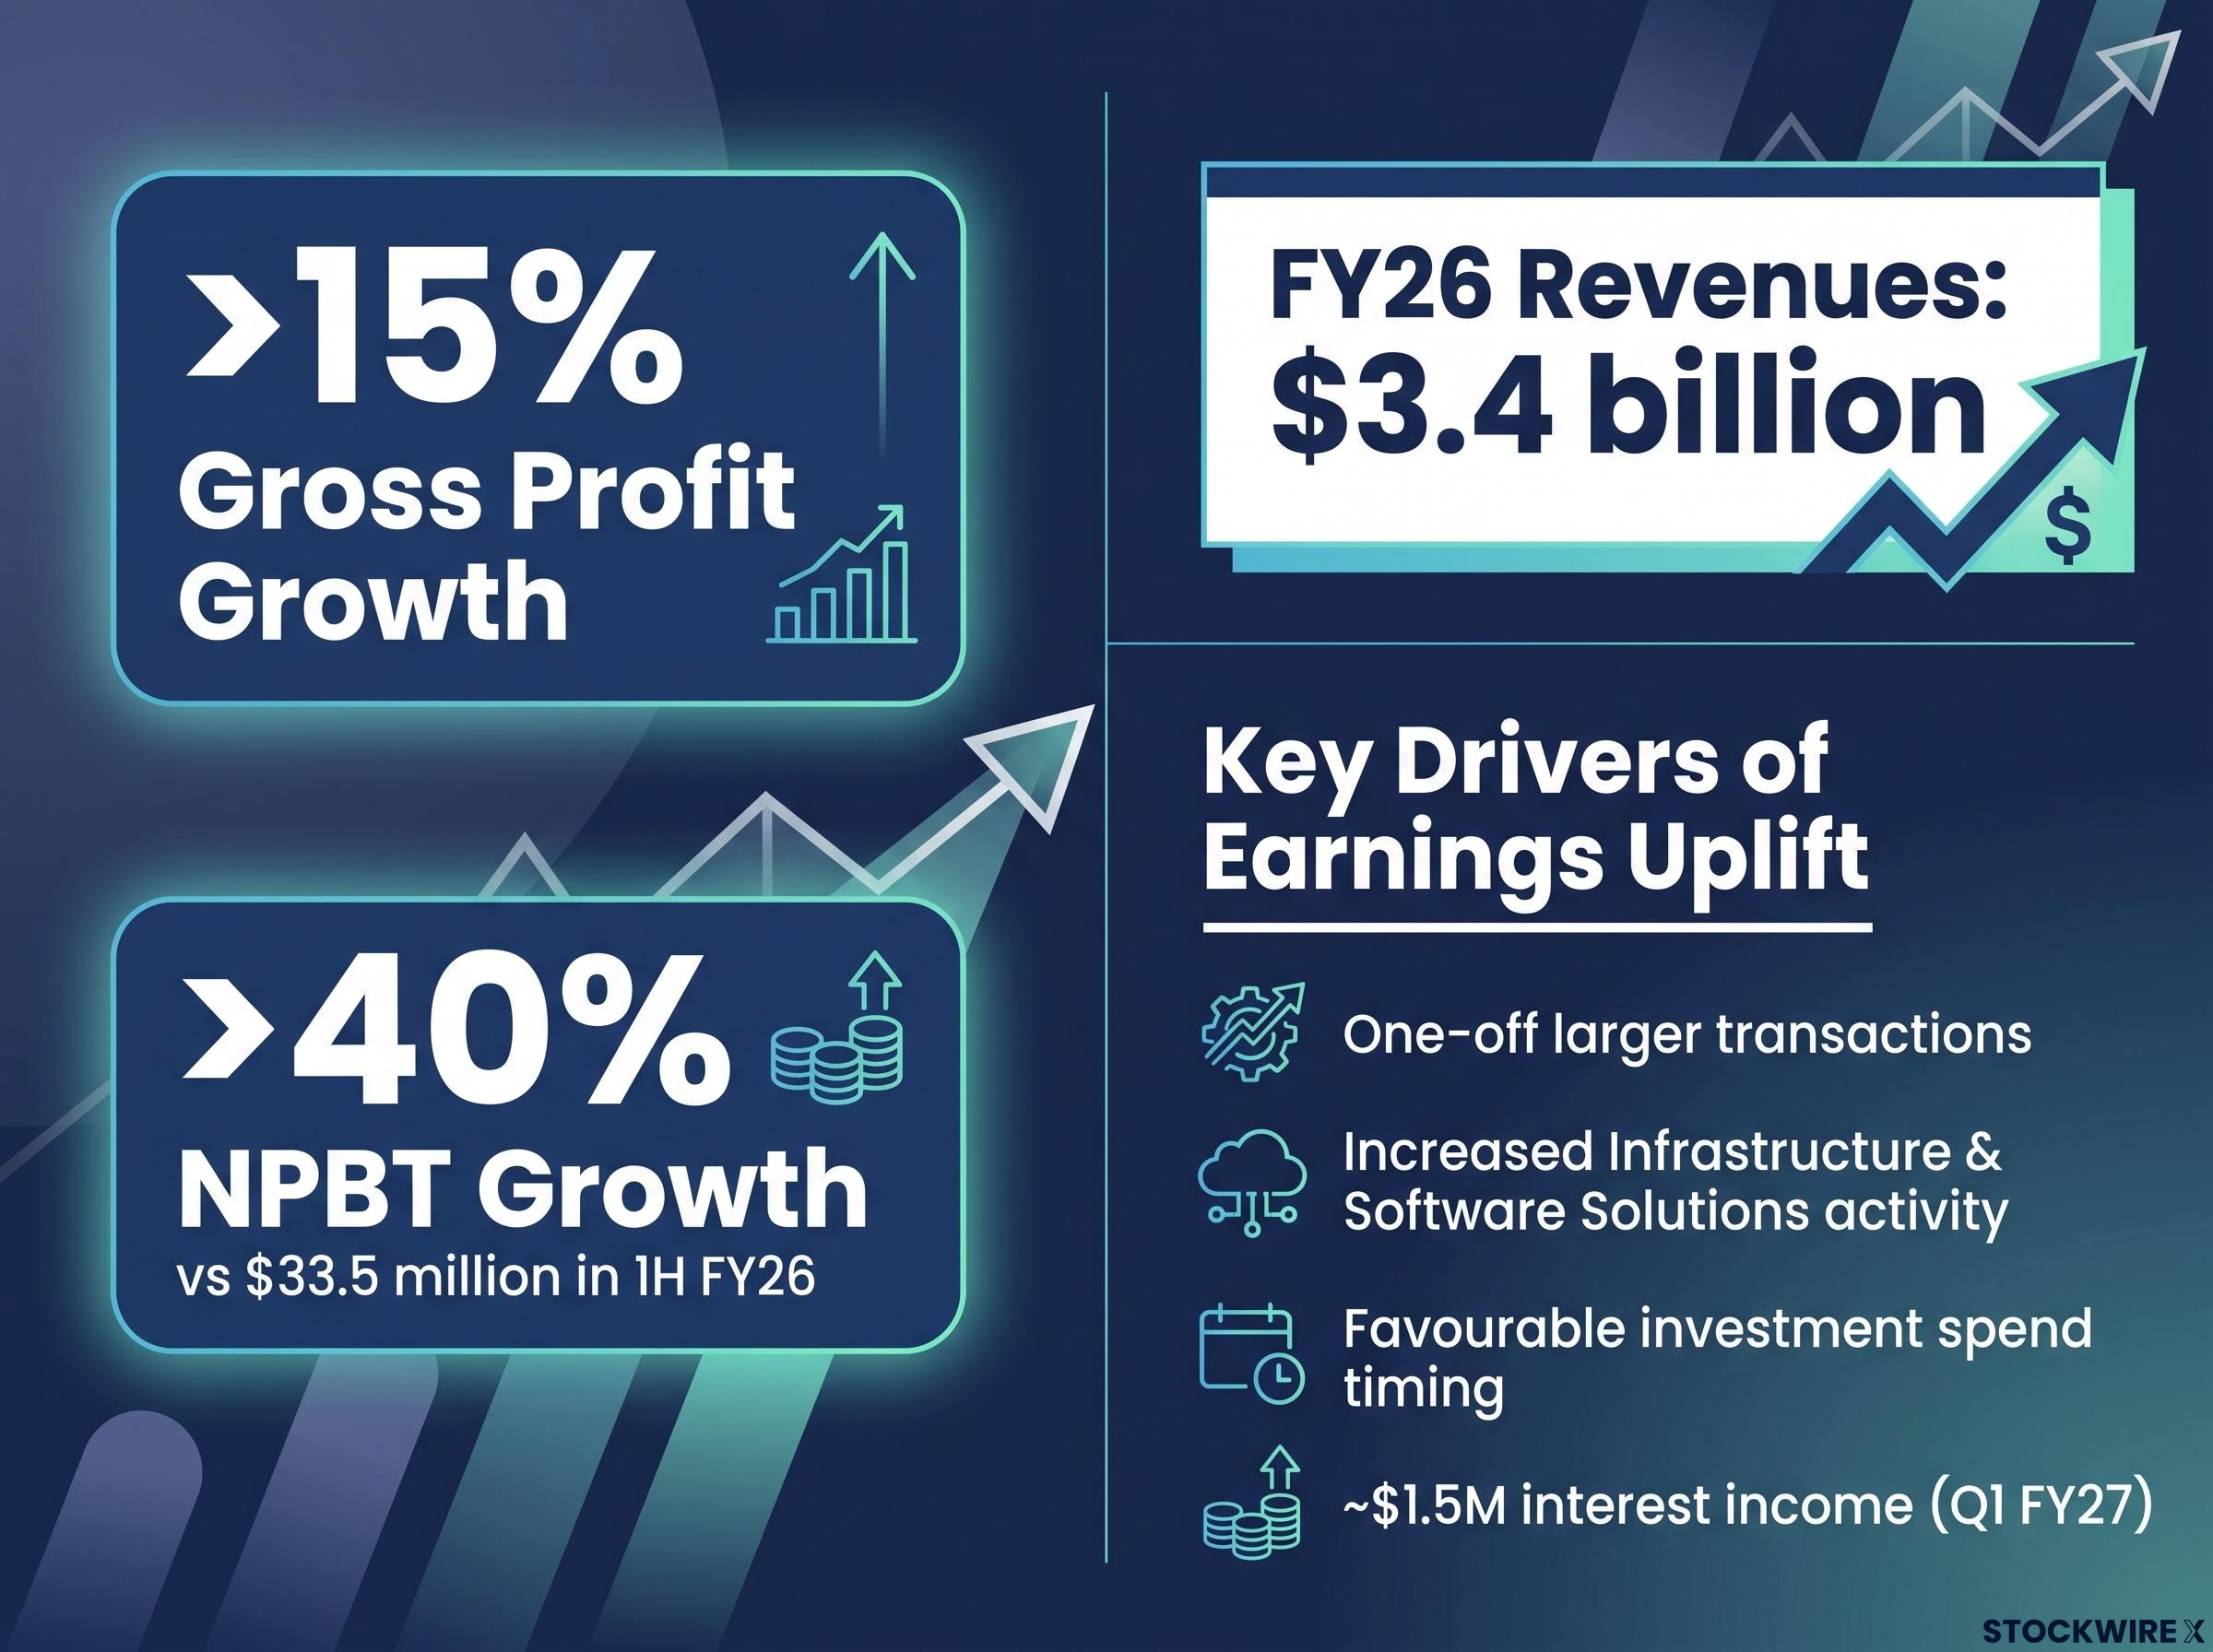
Data#3 Limited (ASX: DTL) has guided to a material earnings upgrade for the first half of FY27, with gross profit expected to grow more than 15% and net profit before tax (NPBT) expected to grow more than 40% on the prior corresponding period. The announcement, issued ahead of the company’s 28 October 2026 AGM, confirms a strong start to the financial year for Australia’s leading IT services and solutions provider, which reported revenues of $3.4 billion in FY26.
The prior period comparative for NPBT is $33.5 million (1H FY26), which was itself impacted by previously announced Microsoft incentive changes. The final interim result remains subject to execution and timing of forecast business through to 31 December 2026, as well as completion of the interim accounts and audit review.
When big ASX news breaks, our subscribers know first
What’s driving the earnings uplift
Data#3 identified four key factors contributing to the stronger-than-expected first-half performance:
- One-off, larger transactions contributing to the period
- Increased activity across Infrastructure and Software Solutions
- Favourable timing of planned investment spend
- Approximately $1.5 million of interest income above expectation, driven by favourable cash flow timing in Q1 FY27
First-half skew: what investors should understand
While the result reflects genuine business momentum, Data#3 has been transparent in flagging that not all of the first-half strength is recurring in nature. The company has explicitly noted that net profit before tax is expected to be skewed to the first half for FY27, given the benefit of significant and non-recurring items in 1H combined with current forecasts for the second half.
Importantly, this disclosure should be read as a transparency positive rather than a concern. Management is proactively setting expectations for a softer second half relative to the first, avoiding the risk of investors extrapolating the 1H run-rate across the full year.
Data#3 guidance
“We expect to deliver sustained earnings growth for the full year as planned.”
The underlying message is clear: 1H FY27 reflects a combination of genuine operational improvement and some timing and one-off benefits. Full-year growth remains on track, and investors should assess the result in that context when interim financials are released in February.
Understanding IT services earnings: why gross profit and NPBT guidance matters
In an IT services and solutions business like Data#3, gross profit is a particularly meaningful metric. Unlike a simple revenue figure, gross profit reflects the margin retained after cost of goods and vendor pricing, making it a direct indicator of business quality, product mix, and the company’s ability to add value beyond pure product resale.
NPBT, or net profit before tax, provides a cleaner view of underlying earnings performance. It captures operating leverage and cost discipline without the distortion of tax-rate movements, making it the preferred measure for assessing period-on-period progress.
It is worth noting that the 1H FY26 comparison base was depressed by the previously announced Microsoft incentive changes, which compressed earnings in that period. The growth reported against that base is genuine, though some of it reflects a recovery from an atypically impacted prior period rather than entirely organic acceleration.
The Data#3 FY26 record results confirmed NPBT of $78.8 million on gross sales of $3.4 billion, with recurring gross sales comprising 70% of total revenue, establishing the earnings base against which the current 1H FY27 upgrade guidance is measured.
Taken together, the combination of >15% gross profit growth and >40% NPBT growth signals both stronger revenue quality and improved operating leverage across the business in the current period.
Key dates and what comes next for DTL investors
With interim results still three months away, investors have a near-term catalyst at the AGM to gauge management’s tone and any additional commentary on trading conditions.
| Event | Date | What to Expect | Why It Matters |
|---|---|---|---|
| 2026 AGM Business Update | 28 October 2026 | Management to provide business update | First live commentary post this guidance release |
| 1H FY27 Results Release | 22 February 2027 | Full interim financials | Confirms gross profit, NPBT and one-off transaction detail |
| Interim Dividend Announcement | 22 February 2027 | Dividend declared | Income investors: watch payout ratio vs prior period |
Data#3 is a well-established operator in the Australian technology sector, with more than 48 years of experience and $3.4 billion in FY26 revenue. The company employs more than 1,400 staff across 12 locations in Australia and Fiji, delivering integrated solutions spanning cloud, modern workplace, security, data and analytics, and connectivity through consulting, project services, and support services.
Don’t Miss the Next ASX Tech Winner
Get FREE breaking ASX technology news delivered to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers who stay ahead of the market the moment news breaks. Click the “Free Alerts” button at StockWire X to start receiving alerts today.