

AUCyber formalises $1 million working capital facility with 5G Networks
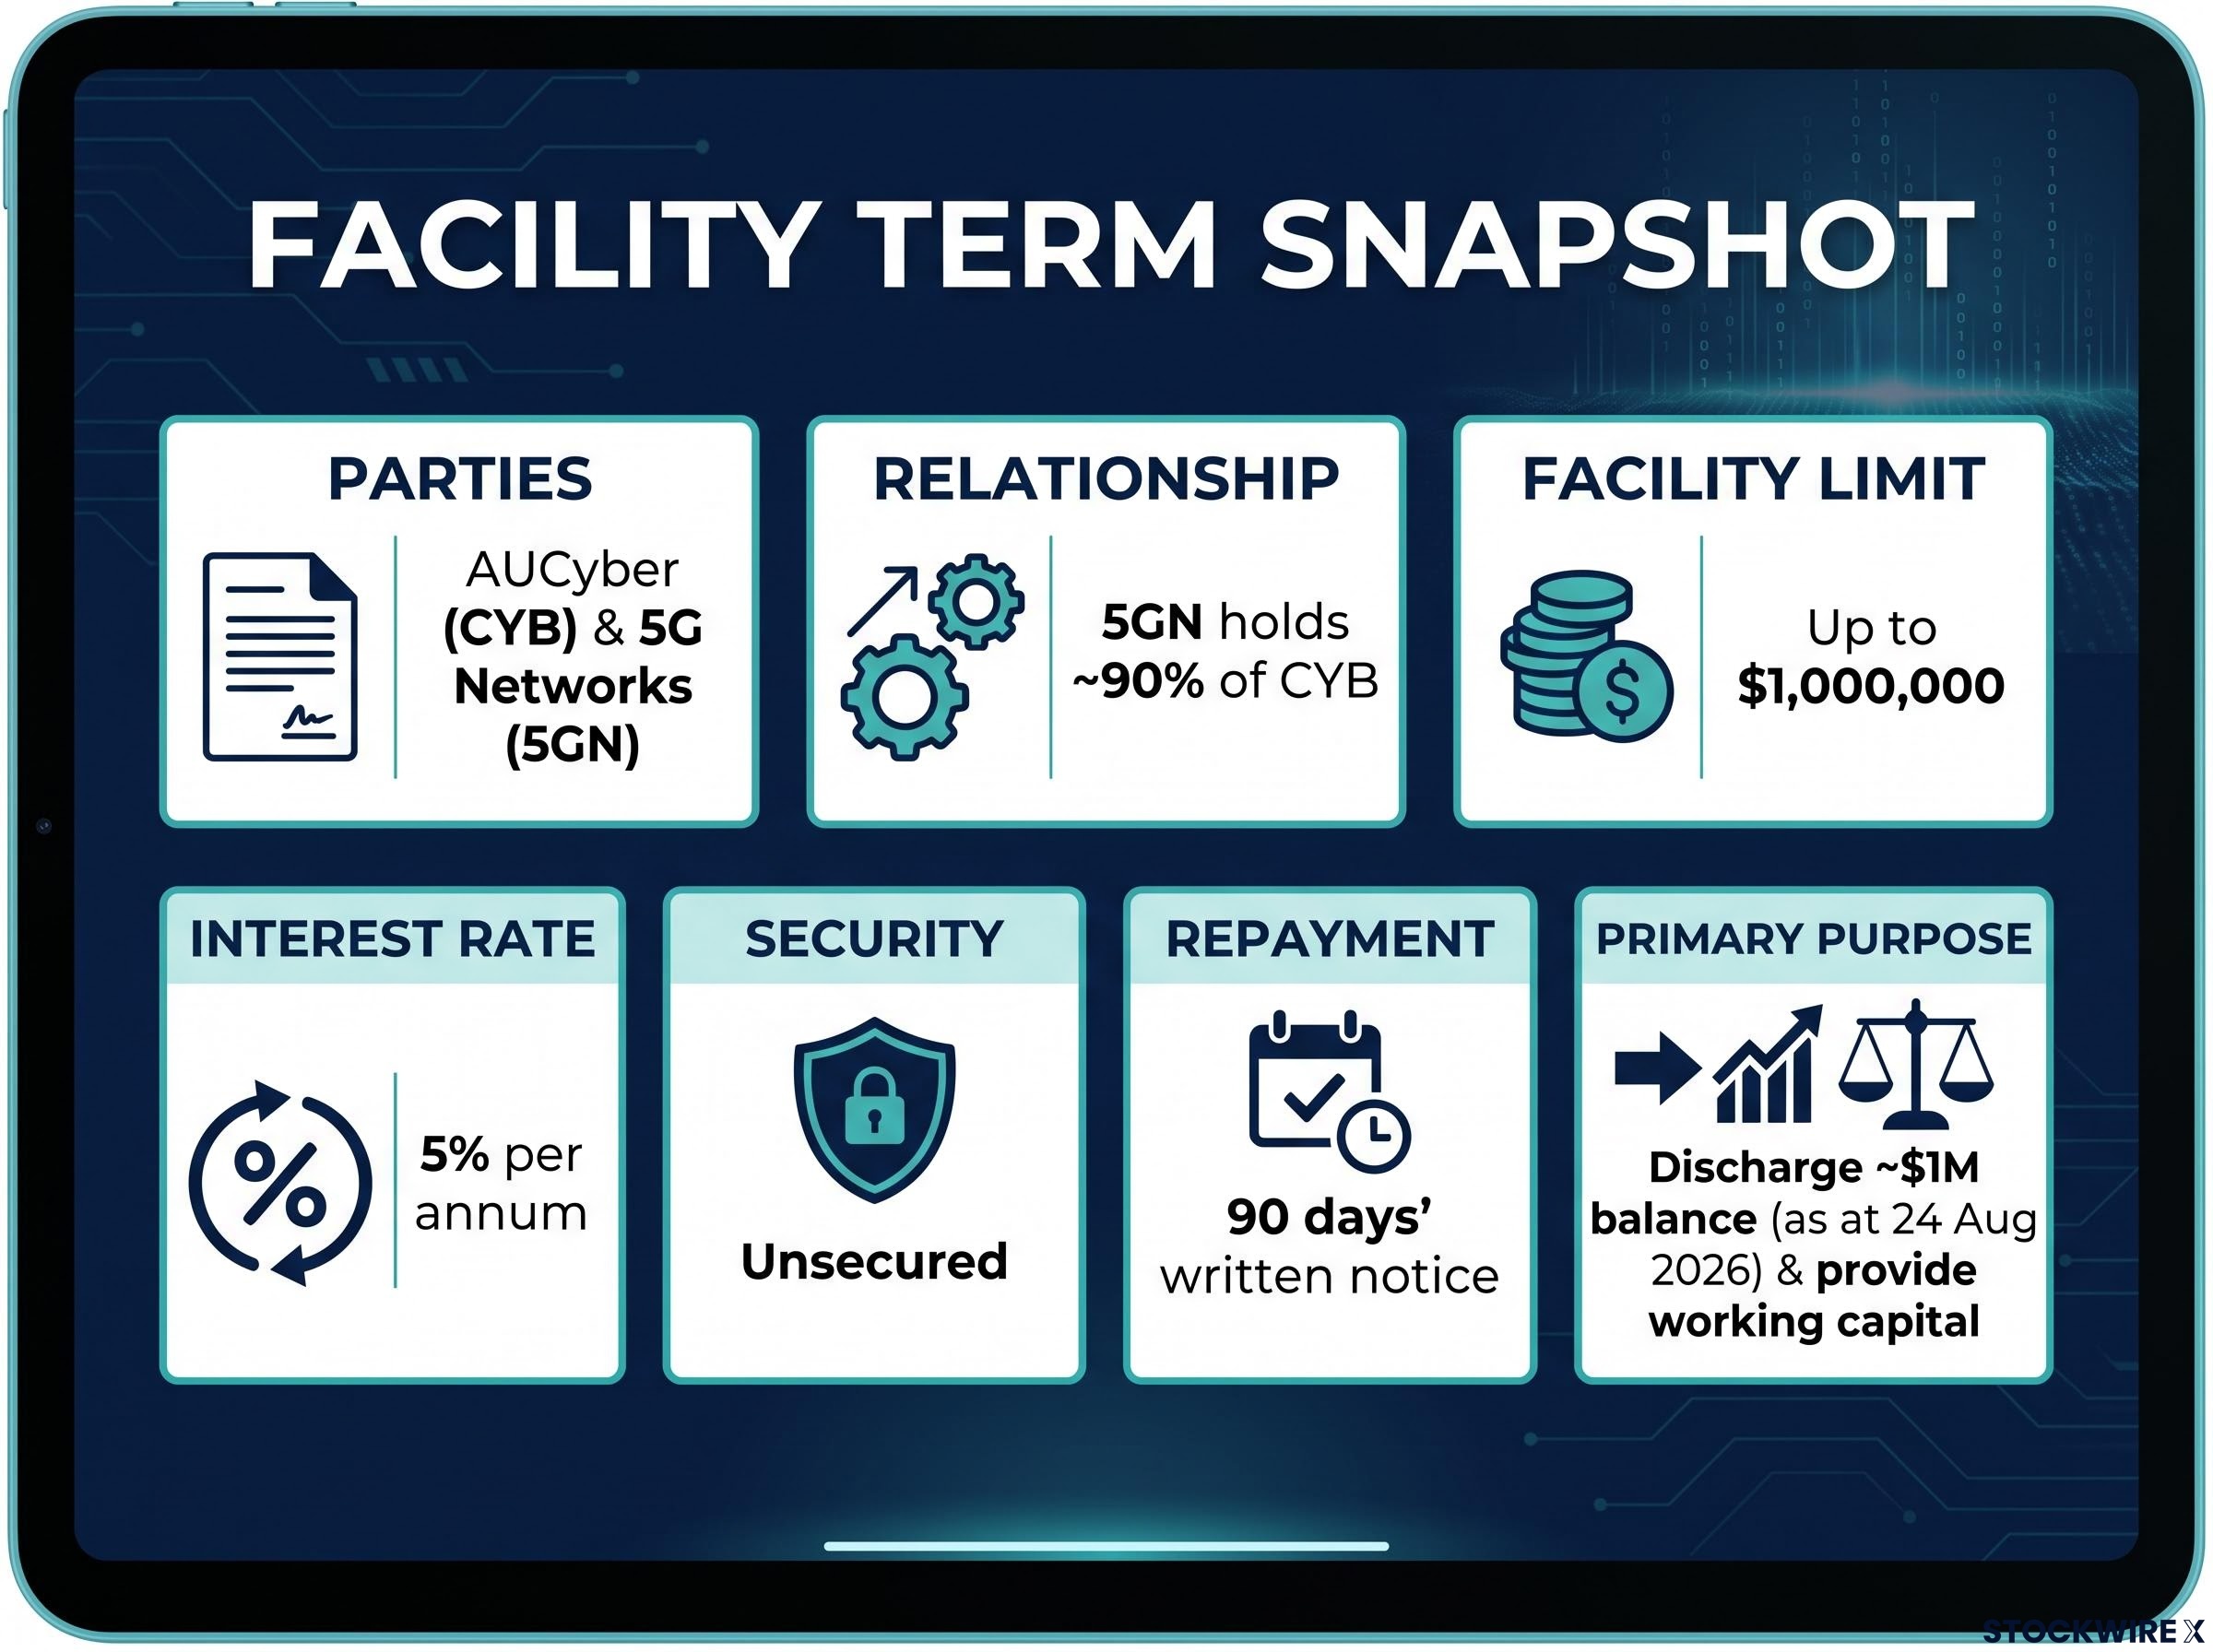
AUCyber Limited (ASX: CYB) has entered into a Loan Facility Deed dated 17 September 2026 with 5G Networks Limited (5GN), its controlling shareholder holding approximately 90% of CYB’s issued shares. The unsecured, revolving facility of up to $1,000,000 is intended to formalise the existing intercompany funding position between the two entities and provide CYB with additional working capital.
The existing intercompany balance owed by CYB to 5GN stood at approximately $1,000,000 as at 24 August 2026. The facility carries no fees or security requirements, with an interest rate of 5% per annum, benchmarked to the Bank Bill Swap Rate (BBSW) for the 6-month term at 15 September 2026.
The facility arrives at a critical moment for CYB’s balance sheet: the company closed FY26 with a working capital shortfall of ($0.2m) against current liabilities of $5.4m, making the formalisation of a structured revolving credit line a material step toward near-term liquidity management.
Key terms of the facility are summarised below.
| Term | Detail |
|---|---|
| Facility limit | $1,000,000, unsecured and revolving |
| Purpose | To discharge the existing intercompany balance owing by CYB to 5GN (approximately $1,000,000 as at 24 August 2026) and provide additional working capital |
| Interest rate | 5% per annum, benchmarked to BBSW (6-month term, 15 September 2026) |
| Repayment | Repayable on 90 days’ written notice from 5GN; amounts may be drawn, repaid, and redrawn during the availability period |
| Security | None. The facility is unsecured. |
When big ASX news breaks, our subscribers know first
What is a revolving loan facility and why does it matter for CYB?
A revolving loan facility functions as a flexible credit line rather than a one-time lump sum. Unlike a term loan, where funds are advanced once and repaid on a fixed schedule, a revolving facility allows the borrower to draw funds, repay them, and draw again as needed during the availability period.
For CYB, this structure provides ongoing access to working capital without committing to a fixed debt obligation. Formalising what was previously an informal intercompany balance converts that arrangement into a structured, documented facility with defined terms, improving corporate governance and balance sheet transparency. Minority shareholders benefit from the clarity that comes with a properly documented, arm’s-length agreement rather than an undocumented intercompany position.
Board confirms arm’s-length terms — no shareholder approval required
The CYB Board assessed the facility under Chapter 2E of the Corporations Act 2001 (Cth) and determined that the financial benefits provided to 5GN, including the interest rate, repayment terms, unsecured nature, and absence of fees or security, meet the arm’s-length test under s.210 of the Act. As a result, CYB shareholder approval under s.208 is not required.
The Board’s assessment took into account comparable arm’s-length lending terms, CYB’s funding requirements, and the alternative financing options available to the company. The Board also confirmed that ASX Listing Rule 10.1 does not apply to the facility as structured, given it is unsecured and does not involve the acquisition or disposal of a substantial asset by either party. The announcement notes this position would need to be reassessed if any security interest, guarantee, asset transfer, or other collateral arrangement were introduced in future.
Stay Ahead on ASX Tech and Finance News
Big News Blast delivers FREE breaking ASX announcements directly to your inbox within minutes of release, complete with in-depth analysis already done. Join 20,000+ subscribers who never miss a market-moving update. Click the “Free Alerts” button at StockWire X to get started today.