

AVADA lifts FY26 revenue to $209.8m as transformation gathers pace
In its FY26 results presentation, AVADA Group reported total statutory revenue of $209.8m for the financial year ended 30 June 2026, from $183.1m in FY25. Management attributed the growth to expansion across Queensland and New South Wales, new customers, and entry into new regional markets.
Adjusted EBITDA, excluding impairments, edged higher to $13.1m (FY25: $12.8m). The company recorded a net loss after tax of $15.2m, a modest improvement on the prior year’s $15.6m loss.
That headline loss, however, was driven by a $15.0m non-cash impairment of Victorian intangibles. On an underlying basis, net profit after tax and amortisation (NPATA) improved to $5.4m, up from $3.0m in FY25. Management positioned FY26 as a year of financial recovery and business transformation.
When big ASX news breaks, our subscribers know first
FY26 financial and operational performance
Revenue growth was underpinned by activity in Queensland and NSW, the addition of new customers, and the company’s move into new regional markets. Management acknowledged that trading conditions remained challenging throughout the year.
Contributing headwinds included price competition and union labour mandates in Victoria and NSW, weather conditions that reduced volumes, a decrease in NZ government projects, and absorbed H2 fuel cost escalation.
Gross margin softened to 18.6% (FY25: 20.7%), while Adjusted EBITDA margin eased to 6.2% (FY25: 7.0%). The company framed these movements as a function of mobilisation costs in new regions and one-off business-strengthening costs, positioning the group for FY27 growth.
The clearest signal of improving underlying profitability was NPATA growing from $3.0m in FY25 to $5.4m in FY26.
The H1 FY26 results, which showed $101.5m in revenue and an adjusted EBITDA margin of 7.0% despite mobilisation costs, established the trajectory that the full-year figures have now confirmed.
| Metric (Adjusted) | FY26 | FY25 |
|---|---|---|
| Total revenue | $210.6m | $183.1m |
| Gross profit | $39.2m | $37.9m |
| Adjusted EBITDA | $13.1m | $12.8m |
| NPATA | $5.4m | $3.0m |
Operational KPIs trending up
Operating metrics showed improving productivity across the fleet and workforce:
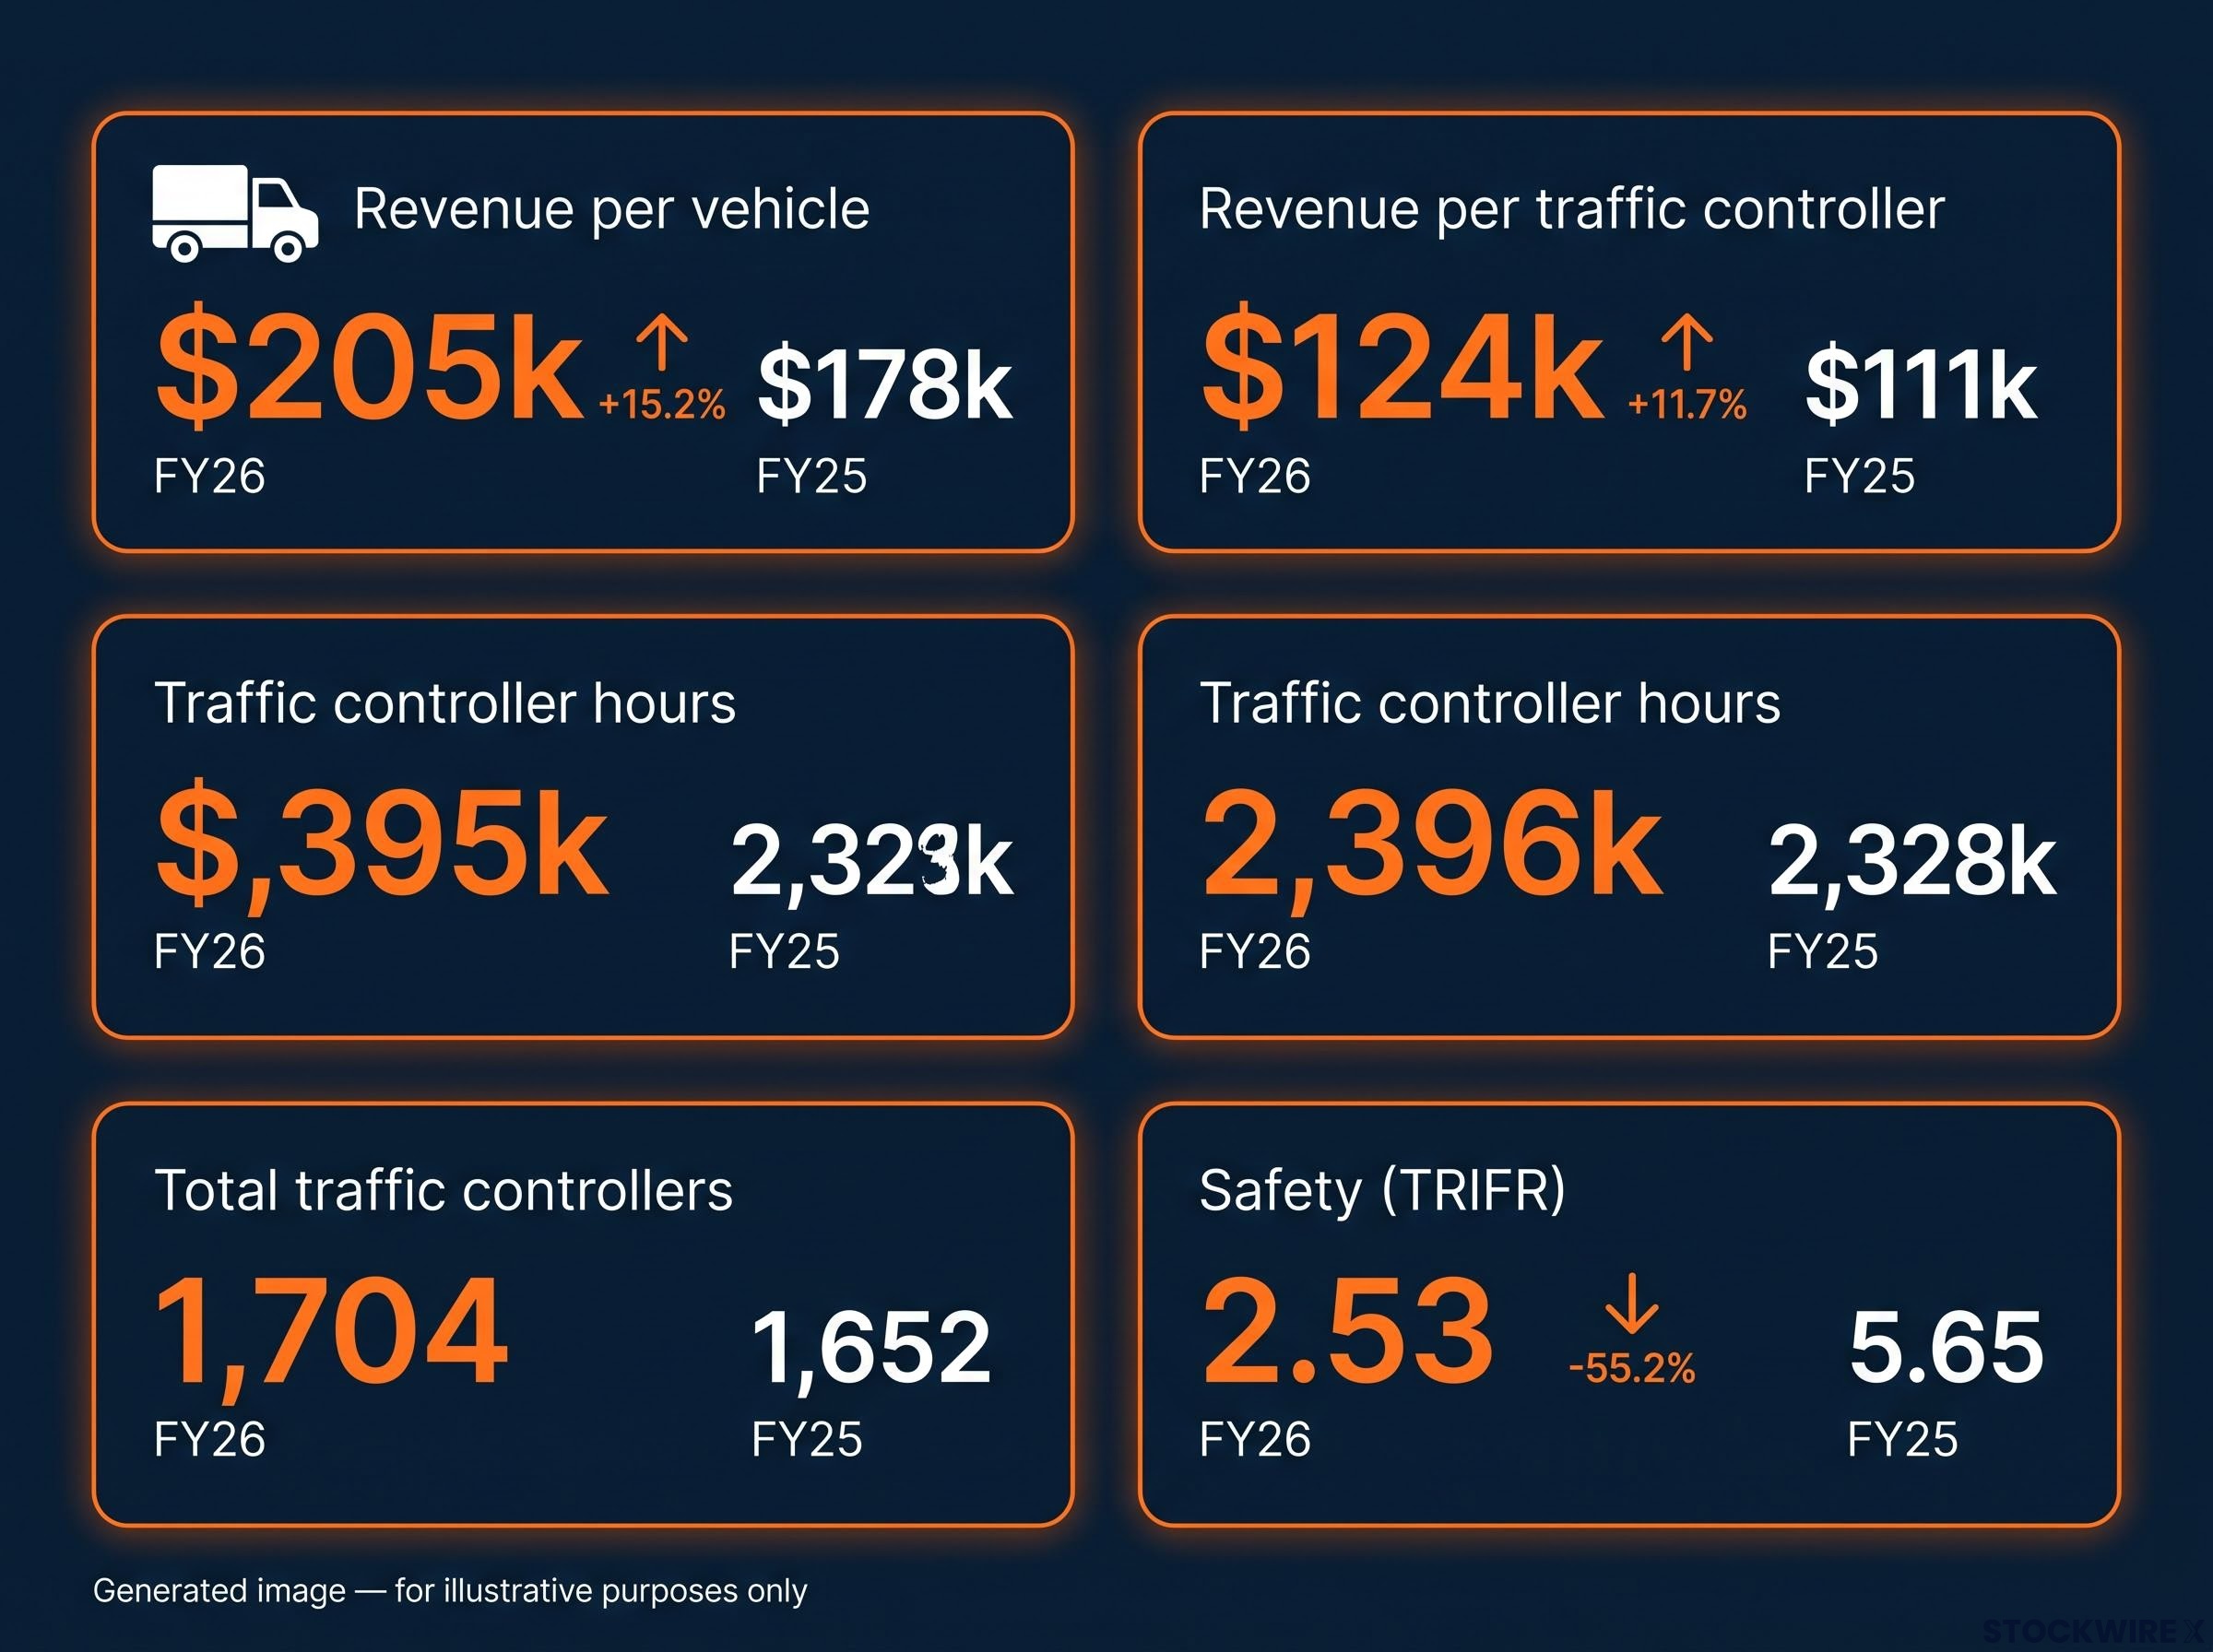
- Revenue per vehicle: $205k, up 15.2% from $178k
- Revenue per traffic controller: $124k, up 11.7% from $111k
- Traffic controller hours: 2,396k (FY25: 2,328k)
- Traffic controllers: 1,704 (FY25: 1,652)
The productivity gains per asset and per worker suggest the transformation is translating into efficiency, not simply top-line growth.
What traffic management means for investors
AVADA provides traffic management and control services for infrastructure, construction, and maintenance projects across Australia and New Zealand. The model is tied closely to government infrastructure spending pipelines, giving it an essential-services character.
The company’s operating KPIs offer a window into efficiency. Revenue per vehicle and revenue per traffic controller measure how well AVADA utilises its assets and workforce. Rising figures indicate better utilisation of the same resource base.
A non-cash impairment is an accounting write-down of an asset’s carrying value, in this case Victorian intangibles. It reduces reported profit but does not drain cash from the business.
For that reason, investors may look through the statutory loss to the underlying cash-generative measures such as Adjusted EBITDA and NPATA, which both improved year on year.
Balance sheet strengthened and banking facilities expanded
Management described FY26 as a year of financial recovery, having completed a borrowings renewal that supports longer-term growth. Key balance sheet movements included:
- Current assets rose 27.6% to $50.0m, driven by increased revenue activity
- Net current assets improved to $11.6m (FY25: $5.1m), reflecting a stronger working capital position
- New CBA facilities were completed in April 2026, lifting the working capital limit from $17.5m to $20m
- Total assets declined to $97.8m (FY25: $107.4m), largely due to the $15.0m Victorian impairment
- Net assets reduced to $23.7m (FY25: $38.7m), again driven by the impairment
The CBA debt refinancing completed in March 2026 replaced a $40m term loan with $42.6m in new facilities, extending maturities and increasing covenant headroom ahead of the regional expansion programme.
The improved liquidity and expanded facilities provide additional capacity to fund FY27 growth and regional expansion.
Leadership transformation and the 2032 Olympics opportunity
AVADA strengthened its leadership bench during the year, appointing a new EGM Strategic Execution and Operations and a new Commercial Manager, and establishing a new Leadership Forum to align strategic priorities.
Management outlined several outcomes from the business transformation programme:
- Improved workforce and vehicle fleet productivity
- Enhanced governance of contract management, capital allocation and resource deployment
- Strengthened resource planning and financial reporting systems
- New customers, markets, and projects in new locations
A notable strategic development was AVADA’s engagement as the head contractor for projects with the Games Independent Infrastructure and Coordination Authority (GIICA), supporting early works infrastructure preparation for the 2032 Olympic Games.
AVADA is partnering with GIICA for the 2032 Olympic Games as principal contractor, providing Traffic Management and auxiliary works.
FY27 outlook and next steps
Management pointed to positive underlying demand drivers, citing a substantial pipeline of infrastructure development and maintenance projects. Expansion of NSW and Queensland projects into new regions is expected to drive year-on-year results.
The transformation programme is continuing, aimed at building a solid operating platform and delivering further efficiency improvements. Principal contractor status with GIICA, providing Traffic Management and auxiliary works ahead of the 2032 Olympic Games, anchors the forward growth outlook.
On safety, the Total Recordable Injury Frequency Rate (TRIFR) improved to 2.53 (FY25: 5.65), a 55.2% improvement that the company attributed to investment in critical risk management and physical and mental health systems.
AVADA enters FY27 with expanded banking facilities, improved productivity metrics, and a marquee infrastructure pipeline underpinning its growth ambitions.
Don’t Miss the Next ASX Industrials Mover
Big News Blast delivers FREE breaking ASX announcements straight to your inbox within minutes of release, complete with in-depth analysis so the work is already done. Join 20,000+ investors who stay ahead of the market the moment news breaks. Click the “Free Alerts” button at Big News Blast to start receiving alerts today.