

BetMakers delivers 205% EBITDA surge as FY26 discipline pays off
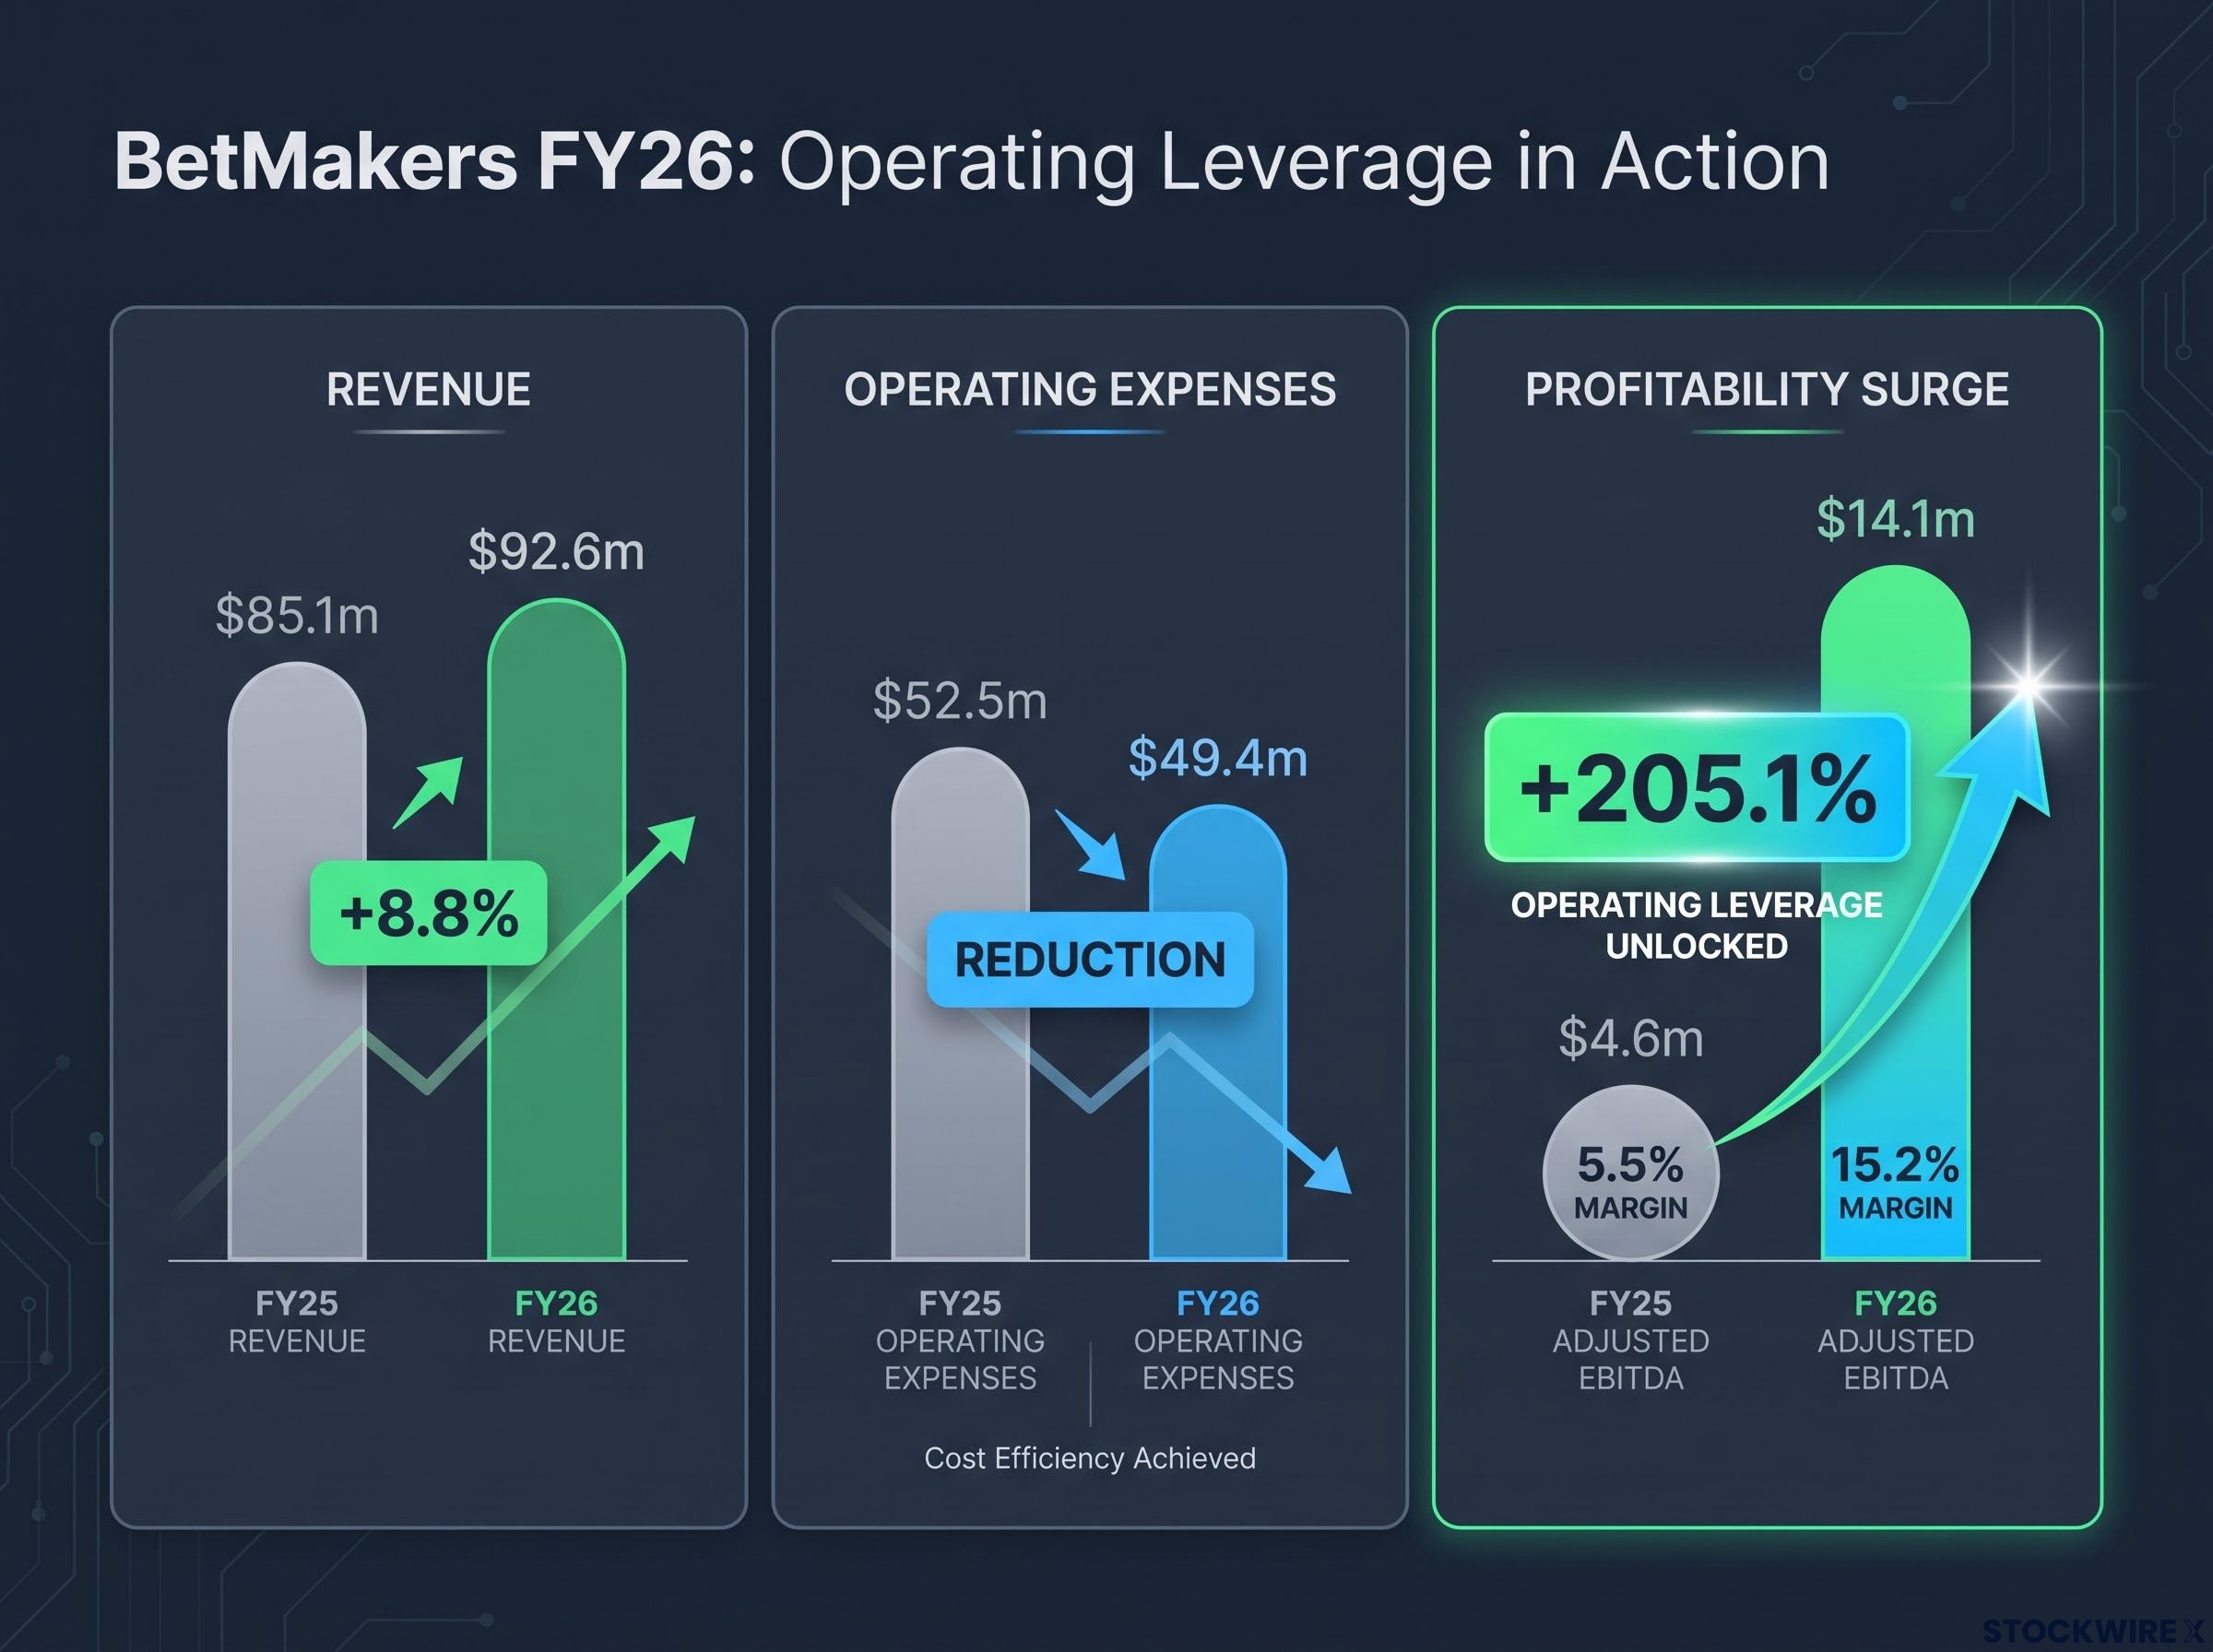
BetMakers Technology Group reported revenue of $92.6 million for the full year ended 30 June 2026 (FY26), up 8.8% (11.2% on a constant currency basis) on FY25’s $85.1 million. The standout result was margin expansion, with Adjusted EBITDA lifting 205.1% to $14.1 million from $4.6 million.
That translated into an Adjusted EBITDA margin of 15.2%, up from 5.5% in FY25. A binding scheme of arrangement with Tabcorp Holdings Limited, announced separately, is now also in play and is covered further below.
When big ASX news breaks, our subscribers know first
FY26 financial results at a glance
The following table summarises the key financial metrics reported for the completed reporting period.
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue | $92.6m | $85.1m | +8.8% (11.2% CC) |
| Adjusted Gross Margin | 66.9% | 64.1% | — |
| Adjusted EBITDA | $14.1m | $4.6m | +205.1% |
| Adjusted EBITDA Margin | 15.2% | 5.5% | — |
| Operating Expenses | $49.4m | $52.5m | −$3.1m |
A few points add context to the headline figures:
-
Operating expenses fell to 53.3% of revenue (from 61.7%), reflecting the full-year benefit of FY25 restructuring plus additional FY26 cost optimisation.
-
The Adjusted Gross Margin includes an adjustment for a $1.3m inventory write-off; the unadjusted Gross Margin was 65.5%.
-
Net loss after tax (NLAT) narrowed sharply to $5.2 million, from $25.3 million in FY25.
What drove the margin expansion
The result reflected operating leverage in action, with revenue scaling while the cost base contracted. Management attributed the outcome to four operational pillars executed through the year.
-
Digital growth — the Apollo platform provided a foundation for core digital revenue growth domestically and internationally, with the expanding customer network opening further content distribution opportunities.
-
Technology execution — continuous improvement of the Apollo platform and further progress on GTX enhanced performance and lowered costs for B2B customers.
-
AI and efficiency — the Company continued embedding artificial intelligence and machine learning tools across its product suite and internal workflows to strengthen efficiency.
-
GT Vegas integration — the successful integration of GT Vegas (formerly LVDC) delivered material technology and cost synergies.
CEO Jake Henson
“Our financial performance confirms the power of our technology-led model, focused growth strategy and operating discipline. By scaling revenue to $92.6 million while strictly managing costs, we achieved a 15.2% Adjusted EBITDA margin, validating our technology investments and setting a strong trajectory for FY27.”
Understanding operating leverage — why it matters for investors
BetMakers offers a clear illustration. Revenue rose 8.8%, yet Adjusted EBITDA jumped 205.1% because operating expenses actually fell, from $52.5 million to $49.4 million. The FY25 restructuring benefits flowing through a full period contributed to this outcome.
BetMakers 1H FY26 results had already flagged the margin inflection, with the company posting $6.0 million Adjusted EBITDA on revenue of $46.1 million in the first half as tier-1 partnerships with CrownBet and Stake came online.
The $0.24 Tabcorp scheme of arrangement
Separately, on 10 August 2026, BetMakers entered into a binding Scheme Implementation Deed (SID) with Tabcorp Holdings Limited (ASX: TAH). Under the deal, Tabcorp has agreed to acquire 100% of the issued shares in BetMakers by way of a scheme of arrangement under Part 5.1 of the Corporations Act 2001 (Cth), subject to the terms and conditions of the SID.
Under the Scheme, BetMakers shareholders will be entitled to receive $0.24 cash for each BetMakers share (“Cash Consideration”), unless they make a valid election to receive part or all of their consideration in new Tabcorp shares (“Mixed / Scrip Election Consideration”). Eligible shareholders may elect to receive 25%, 50%, 75% or 100% of their Scheme Consideration in new Tabcorp shares.
The aggregate scrip election is capped at 25% of the total Scheme Consideration (“Maximum Scrip Consideration”) and will be subject to a pro rata scale-back if valid elections exceed that cap.
The BetMakers Board unanimously recommends that shareholders vote in favour of the Scheme, in the absence of a Superior Proposal and subject to an Independent Expert concluding that the Scheme is in the best interests of shareholders. Directors intend to vote all shares in which they have a relevant interest, representing approximately 10% of shares on issue, in favour. Fuller detail is contained in the ASX announcement released on 10 August 2026.
FY27 outlook and strategic priorities
BetMakers stated it enters FY27 with an optimised operating base, a strong pipeline and a technology roadmap. Management set out three strategic priorities for the year ahead.
-
Technology-led growth in digital revenues domestically and internationally, plus expansion of content revenues and products.
-
Operating discipline and cost base optimisation to drive further operating leverage, including embedding AI tools to automate workflows.
-
Expansion in Adjusted EBITDA and Adjusted EBITDA margin, to be driven by revenue growth and operating leverage.
CEO Jake Henson
“The start to FY27 has been strong, with 1H FY27 expected to continue to demonstrate the strength of BetMakers’ upgraded technology and expanded product suite.”
As a closing housekeeping point, the Company scheduled an investor webinar for 10.30am AEST on 1 September 2026, featuring Executive Chairman Matt Davey, CEO Jake Henson and CFO Carl Henschke.
Don’t Miss the Next Consumer Tech Winner on ASX
Big News Blast delivers FREE breaking ASX news straight to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ subscribers who stay ahead of the market the moment announcements drop. Click the “Free Alerts” button at StockWire X to get started today.